

|
시장보고서
상품코드
1982305
식품 식이섬유 시장 기회, 성장 요인, 업계 동향 분석 및 예측(2026-2035년)Food Fibers Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 식품 식이섬유 시장은 2025년 305억 달러로 평가되었고 CAGR은 7.7%를 나타낼 것으로 보이며, 2035년까지 638억 달러에 이를 것으로 추정됩니다.

소비자들이 건강, 웰빙, 예방 영양에 더 큰 비중을 두면서 식품 섬유 산업은 강력한 성장세를 보이고 있습니다. 소화기 건강과 전반적인 웰빙에 대한 인식이 높아짐에 따라 소비자들은 식이섬유가 풍부한 제품을 일상 식단에 포함시키려 하고 있습니다. 그 결과, 세계의 시장에서 식이섬유가 강화된 식품 및 음료에 대한 수요가 지속적으로 증가하고 있습니다. 대사 및 심혈관 질환을 포함한 생활습관병에 대한 우려가 커지면서 구매 행태에도 더욱 큰 영향을 미치고 있습니다. 소비자들은 체중 관리, 혈당 수치 균형 유지, 장기적인 건강 증진을 지원하는 식이 솔루션을 적극적으로 찾고 있습니다. 이러한 선제적 영양 관리로의 전환은 식품 제조업체들이 식이섬유가 풍부한 혁신적인 기능성 제품을 개발하도록 동기를 부여하고 있습니다. 기능성 식품 및 음료 부문은 광범위한 영양 산업 내에서 핵심 성장 동력으로 부상하며, 섬유질 기반 원료의 전략적 중요성을 강화하고 있습니다. 지속적인 제품 개발과 소매 유통망의 확대는 글로벌 식품 섬유 시장의 성장 궤도를 더욱 공고히 하고 있습니다.
| 시장 범위 | |
|---|---|
| 시작 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 시작 시장 규모 | 305억 달러 |
| 예측 금액 | 638억 달러 |
| CAGR | 7.7% |
수용성 식이섬유 부문은 2025년 47억 달러의 매출을 기록했으며, 2026년부터 2035년까지 연평균 성장률(CAGR) 8.2%로 성장할 것으로 예상됩니다. 이 부문의 성장은 소화 균형 유지, 콜레스테롤 관리, 혈당 조절에 도움이 되는 수용성 식이섬유에 대한 인식이 높아짐에 따라 주도되고 있습니다. 제조사들은 건강 지향적 솔루션에 대한 소비자 수요를 충족시키기 위해 기능성 식품, 음료 및 건강보조식품에 수용성 식이섬유를 첨가하고 있습니다. 동시에, 소화되지 않는 식이섬유는 규칙적인 배변 기능을 촉진하고 전반적인 장 건강을 유지하는 데 기여한다는 점에서 주목받고 있습니다.
베이커리, 시리얼, 스낵 부문은 2025년에 128억 달러를 차지하고 2035년까지 연평균 복합 성장률(CAGR) 7.3%를 나타낼 것으로 예측됩니다. 이 부문은 생산자들이 일상 식품의 식감을 향상시키고, 안정성을 높이며, 영양가를 증진하기 위해 식이섬유를 첨가함에 따라 시장 주도권을 유지하고 있습니다. 또한 식품 섬유는 유제품 대체품 및 식물성 제형에서 바람직한 농도와 구조적 특성을 제공함으로써 혁신을 뒷받침합니다. 영양보충제 부문에서는 식이섬유를 활용해 소화기 건강에 이점을 제공하고, 소비자 선호도에 부합하는 맞춤형 웰니스 블렌드를 개발하고 있습니다.
북미의 식품 식이섬유 시장은 2025년 107억 달러에 이르고, 예측기간을 통해 꾸준한 성장이 예상됩니다. 이 지역의 시장 확대는 소화기 건강, 체중 관리, 예방적 식습관에 대한 소비자 인식의 고조에 힘입고 있습니다. 섬유질이 풍부한 기능성 식품, 음료 및 보충제에 대한 강력한 수요는 잘 구축된 소매 유통망과 식이섬유 섭취의 장기적인 건강 이점에 대한 인식 확산에 의해 더욱 강화되고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
- 생태계 분석
- 공급자의 상황
- 이익률
- 각 단계의 부가가치
- 밸류체인에 영향을 주는 요인
- 혁신
- 업계에 미치는 영향요인
- 성장 촉진요인
- 업계의 잠재적 위험 및 과제
- 시장 기회
- 성장 가능성 분석
- 규제 상황
- 북미
- 유럽
- 아시아태평양
- 라틴아메리카
- 중동 및 아프리카
- Porter's Five Forces 분석
- PESTEL 분석
- 가격 동향
- 지역별
- 섬유유형별
- 향후 시장 동향
- 기술 및 혁신 동향
- 현재의 기술 동향
- 신흥 기술
- 특허 동향
- 무역 통계(주 : 무역 통계는 주요 국가에서만 제공됨)
- 주요 수입국
- 주요 수출국
- 지속가능성과 환경면
- 지속가능한 대처
- 폐기물 감축 전략
- 생산의 에너지 효율
- 환경 배려형 이니셔티브
제4장 경쟁 구도
- 소개
- 기업의 시장 점유율 분석
- 지역별
- 북미
- 유럽
- 아시아태평양
- 라틴아메리카
- 중동 및 아프리카
- 지역별
- 기업 매트릭스 분석
- 주요 시장 기업의 경쟁 분석
- 경쟁 포지셔닝 매트릭스
- 주요 발전
- 합병 및 인수
- 제휴 및 협업
- 신제품 발매
- 사업 확대 계획
제5장 시장 추계 및 예측 : 섬유유형별(2022-2035년)
- 수용성 식이섬유
- 펙틴 및 검
- 베타글루칸 및 특수 섬유
- 기타 수용성 식이섬유
- 불용성 식이섬유
- 셀룰로오스 및 변성 셀룰로오스
- 밀기울과 곡물 식이섬유
- 과일 및 채소 기반 식이섬유
- 프리바이오틱스 섬유
- 이눌린
- 레지스턴트 스타치
- FOS
- GOS
- 기타 프리바이오틱스 섬유
- 기능성 섬유/엔지니어링 섬유
- 폴리덱스트로스
- 저항성 말토덱스트린
- 신규 엔지니어링 섬유
제6장 시장 추계 및 예측 : 용도별(2022-2035년)
- 베이커리, 시리얼, 스낵
- 빵 및 베이커리 제품
- 조식용 시리얼 및 스낵
- 과자 및 과자
- 기타
- 유제품 및 식물 유래 제품
- 유제품
- 요구르트 및 발효유 제품
- 치즈 및 가공 유제품
- 기타 유제품
- 식물 유래 유제품 대체품
- 식물 유래 우유
- 식물 유래 요구르트
- 식물 유래 치즈 및 기타 유제품 대체품
- 유제품
- 음료
- 기능성 음료 및 스포츠 드링크
- 주스 및 기능성 워터
- 기타 식이섬유 강화 음료
- 영양 보조 식품
- 분말 및 캡슐
- 프리바이오틱스/장내 환경 및 건강 보충제
- 체중 관리 및 대사 건강 보충제
제7장 시장 추계 및 예측 : 최종 용도별(2022-2035년)
- 식품 및 음료 업계
- 영양 보조 식품 및 기능성 식품
- 의료 및 임상 영양
- 스포츠 및 퍼포먼스 영양
- 동물 및 반려동물용 영양
- 기타
제8장 시장 추계 및 예측 : 지역별(2022-2035년)
- 북미
- 미국
- 캐나다
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양
- 라틴아메리카
- 브라질
- 멕시코
- 아르헨티나
- 기타 라틴아메리카
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카
- 아랍에미리트(UAE)
- 기타 중동 및 아프리카
제9장 기업 프로파일
- Archer Daniels Midland Company(ADM)
- Cargill, Incorporated
- Ingredion Incorporated
- Tate &Lyle PLC
- BENEO GmbH
- Roquette Freres
- Kerry Group
- International Flavors and Aromas Other
- J Rettenmaier & Sohne GmbH Co KG
- Nexira Inc.
The Global Food Fibers Market was valued at USD 30.5 billion in 2025 and is estimated to grow at a CAGR of 7.7% to reach USD 63.8 billion by 2035.
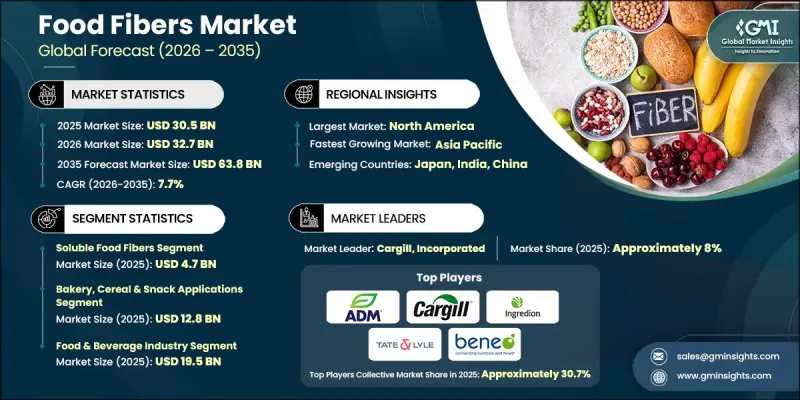
The food fibers industry is witnessing strong expansion as consumers place greater emphasis on health, wellness, and preventive nutrition. Increasing awareness about digestive health and overall well-being is encouraging individuals to incorporate fiber-rich products into their daily diets. As a result, demand for fiber-fortified foods and beverages continues to rise across global markets. Growing concerns related to lifestyle-associated health conditions, including metabolic and cardiovascular disorders, are further influencing purchasing behavior. Consumers are actively seeking dietary solutions that support weight management, balanced blood sugar levels, and long-term health outcomes. This shift toward proactive nutrition is motivating food manufacturers to develop innovative functional products enriched with dietary fibers. The functional food and beverage segment has emerged as a key growth engine within the broader nutrition industry, reinforcing the strategic importance of fiber-based ingredients. Continuous product development and increasing retail availability are further strengthening the growth trajectory of the global food fibers market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $30.5 Billion |
| Forecast Value | $63.8 Billion |
| CAGR | 7.7% |
The soluble food fibers segment generated USD 4.7 billion in 2025 and is expected to grow at a CAGR of 8.2% between 2026 and 2035. Growth in this segment is driven by rising recognition of soluble fibers for supporting digestive balance, cholesterol management, and glycemic control. Manufacturers are incorporating soluble fibers into functional foods, beverages, and dietary supplements to meet consumer demand for health-oriented solutions. At the same time, indigestible food fibers are gaining attention for their role in promoting regular bowel function and maintaining overall gut wellness.
The bakery, cereal, and snack applications segment accounted for USD 12.8 billion in 2025 and is projected to grow at a CAGR of 7.3% through 2035. This segment maintains market leadership as producers integrate dietary fibers to enhance texture, improve stability, and increase nutritional value in everyday food products. Food fibers also support innovation in dairy alternatives and plant-based formulations by contributing to desirable consistency and structural properties. In the dietary supplements category, fibers are utilized to deliver digestive health benefits and to formulate targeted wellness blends aligned with consumer preferences.
North America Food Fibers Market reached USD 10.7 billion in 2025 and is anticipated to experience steady growth over the forecast period. Regional expansion is supported by heightened consumer awareness regarding digestive health, weight management, and preventive dietary practices. Strong demand for fiber-enriched functional foods, beverages, and supplements is reinforced by well-established retail distribution networks and growing education about the long-term health benefits of dietary fiber consumption.
Major companies operating in the Global Food Fibers Market include Cargill, Incorporated; Archer Daniels Midland Company (ADM); Ingredion Incorporated; Tate & Lyle PLC; Roquette Freres; Kerry Group; BENEO GmbH; J Rettenmaier & Sohne GmbH + Co KG; Nexira Inc.; and International Flavors and Aromas. Companies in the Food Fibers Market are strengthening their competitive position through product innovation, strategic partnerships, and expansion into high-growth regions. Leading players are investing in research and development to create customized fiber solutions tailored to specific functional and nutritional needs. Collaboration with food and beverage manufacturers is accelerating the integration of advanced fiber ingredients into new product launches. Firms are also focusing on clean-label formulations and sustainable sourcing practices to align with evolving consumer expectations.
Table of Contents
Chapter 1 Methodology
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Fiber Type
- 2.2.3 Application
- 2.2.4 End use
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
- 2.4.2 Critical success factors
- 2.5 Future Outlook and Strategic Recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By fiber type
- 3.8 Future market trends
- 3.9 Technology and Innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (Note: the trade statistics will be provided for key countries only)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and Environmental Aspects
- 3.12.1 Sustainable Practices
- 3.12.2 Waste Reduction Strategies
- 3.12.3 Energy Efficiency in Production
- 3.12.4 Eco-friendly Initiatives
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Fiber Type, 2022- 2035 (USD Billion, Kilo Tons)
- 5.1 Key trends
- 5.2 Soluble fibers
- 5.2.1 Pectins and gums
- 5.2.2 Beta-glucan and specialized fibers
- 5.2.3 Other soluble fibers
- 5.3 Insoluble fibers
- 5.3.1 Cellulose and modified cellulose
- 5.3.2 Wheat bran and cereal fibers
- 5.3.3 Fruit and vegetable fibers
- 5.4 Prebiotic fibers
- 5.4.1 Inulin
- 5.4.2 Resistant starch
- 5.4.3 FOS
- 5.4.4 GOS
- 5.4.5 Other prebiotic fibers
- 5.5 Functional fibers/engineered fibers
- 5.5.1 Polydextrose
- 5.5.2 Resistant maltodextrin
- 5.5.3 Novel engineered fibers
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Billion, Kilo Tons)
- 6.1 Key trends
- 6.2 Bakery, Cereal & Snack Applications
- 6.2.1 Bread and Bakery Products
- 6.2.2 Breakfast Cereals and Snacks
- 6.2.3 Confectionary and Sweet Products
- 6.2.4 Others
- 6.3 Dairy & Plant-Based Applications
- 6.3.1 Dairy Products
- 6.3.1.1 Yogurt & Fermented Dairy
- 6.3.1.2 Cheese & Processed Dairy Products
- 6.3.1.3 Other Dairy Products
- 6.3.2 Plant-Based Dairy Alternatives
- 6.3.2.1 Plant-Based Milks
- 6.3.2.2 Plant-Based Yogurts
- 6.3.2.3 Plant-Based Cheese & Other Dairy Replacements
- 6.3.1 Dairy Products
- 6.4 Beverages
- 6.4.1 Functional & Sports Drinks
- 6.4.2 Juices & Enhanced Waters
- 6.4.3 Other Fiber-Fortified Beverages
- 6.5 Dietary Supplements
- 6.5.1 Powders & Capsules
- 6.5.2 Prebiotic / Gut and Health Supplements
- 6.5.3 Weight Management & Metabolic Health Supplements
Chapter 7 Market Estimates and Forecast, By End Use, 2022 - 2035 (USD Billion, Kilo Tons)
- 7.1 Key trends
- 7.2 Food & Beverage Industry
- 7.3 Dietary Supplements & Nutraceuticals
- 7.4 Medical & Clinical Nutrition
- 7.5 Sports & Performance Nutrition
- 7.6 Animal & Pet Nutrition
- 7.7 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Billion, Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East & Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East & Africa
Chapter 9 Company Profiles
- 9.1 Archer Daniels Midland Company (ADM)
- 9.2 Cargill, Incorporated
- 9.3 Ingredion Incorporated
- 9.4 Tate & Lyle PLC
- 9.5 BENEO GmbH
- 9.6 Roquette Freres
- 9.7 Kerry Group
- 9.8 International Flavors and Aromas Other
- 9.9 J Rettenmaier & Sohne GmbH + Co KG
- 9.10 Nexira Inc.


