

|
시장보고서
상품코드
2109149
광업용 재제조 부품 시장 기회, 성장 촉진요인, 업계 동향 분석 및 예측(2026-2035년)Mining Remanufacturing Components Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 광업용 재제조 부품 시장은 2025년에 64억 달러 규모로 평가되었고, CAGR 7.3%로 성장하여 129억 달러에 이를 것으로 예측됩니다.
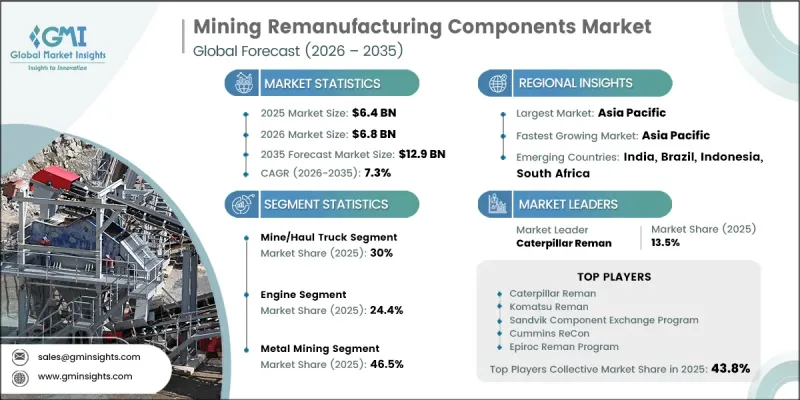
시장 확장을 뒷받침하는 주요 요인 중 하나는 신품 순정 부품에 비해 광업용 재제조 부품이 제공하는 상당한 비용상의 이점입니다. 인증을 받은 재생 제품은 동등한 가동 성능과 신뢰성을 확보하면서 상당한 비용 절감과 보증 지원을 제공하기 때문에 유지보수 비용 절감을 목표로 하는 광업 사업자에게 점점 더 매력적인 선택지가 되고 있습니다. 설비의 수명을 연장하고 총 소유 비용을 절감하려는 경향이 강해짐에 따라, 각 광업 기업들은 장기적인 유지보수 및 재고 전략에 재생산 부품을 도입하고 있습니다. 또한, 순환형 경제의 원칙과 기업의 지속가능성 노력에 대한 관심이 높아짐에 따라 광업 부문 전반에서 재생산 부품에 대한 수요가 확대되고 있습니다. 상태 모니터링 기술과 예측 유지보수 시스템의 보급은 적절한 시기의 부품 교체와 계획적인 재생을 가능하게 하여, 설비의 수명 주기 관리를 더욱 혁신하고 있습니다. 각 광업 기업이 대규모 광업 사업에서 비용 효율성, 운영 신뢰성 및 지속 가능한 자산 관리를 우선시함에 따라, 이러한 동향은 광업용 재제조 부품 시장의 기회를 지속적으로 확대되고 있습니다.
| 시장 범위 | |
|---|---|
| 시작 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 시작 금액 | 64억 달러 |
| 예측 금액 | 129억 달러 |
| CAGR | 7.3% |
광산 및 운반 트럭 부문은 2025년에 30%의 점유을을 차지했으며, 2026년부터 연평균 성장률(CAGR) 7.9%를 나타낼 것으로 전망됩니다. 이 부문이 주도적인 위치를 유지하고 있는 이유는 운반 트럭이 가혹한 조건에서 가동되어 주요 기계 시스템의 마모가 가속화되기 때문입니다. 주요 어셈블리를 새 부품으로 교체하려면 막대한 설비 투자가 필요하기 때문에 광산 운영사는 설비의 성능을 회복하면서도 유지보수 비용을 대폭 절감할 수 있는 재제조 부품의 도입을 추진하고 있습니다. 차량의 가동률 향상과 설비 가동률을 극대화해야 할 필요성이 높아짐에 따라, 이 부문에서 재생산에 대한 견조한 수요는 앞으로도 지속될 것으로 전망됩니다.
금속 광업 부문은 2025년에 46.5%의 점유율을 차지했습니다. 이러한 성장은 광물 자원에 대한 전 세계적 수요 증가와 산업 발전 및 확대되는 인프라 수요를 뒷받침하는 광업 프로젝트에 대한 지속적인 투자에 의해 주도되고 있습니다. 설비 가동률 향상, 자재 처리량 증가, 그리고 유지보수 주기 단축으로 인해 재생 엔진, 유압 시스템, 변속기, 최종 구동 장치 및 기타 주요 부품에 대한 수요가 증가하고 있습니다. 각 광산 기업이 운영 비용을 절감하면서 설비의 생산성 향상에 주력하는 가운데, 금속 광업 사업 전반에 걸쳐 재생 솔루션에 대한 수요는 계속해서 강세를 보이고 있습니다.
중국의 광업용 재제조 부품 시장은 46%의 점유율을 차지하며, 2025년에는 9억 7,710만 달러 시장 규모를 기록했습니다. 중국의 선도적 지위는 광업의 광범위한 규모와 다양한 자원 채굴 활동에 투입되는 중장비 광산 기기의 막대한 도입 대수에 의해 뒷받침되고 있습니다. 지속적인 생산 일정, 높은 설비 가동률, 그리고 기계의 수명 연장이 점점 더 중요시됨에 따라 재생 부품에 대한 수요는 계속해서 증가하고 있습니다. 각 광산 기업들은 운영 신뢰성 향상, 유지보수 비용 절감, 그리고 장기적인 자산 성과 극대화를 도모하기 위해 재제조 부품을 설비 유지보수 전략에 점점 더 많이 도입하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 규모 및 예측 : 구성 요소별(2022-2035년)
제6장 시장 규모 및 예측 : 기기 유형별(2022-2035년)
제7장 시장 규모 및 예측 : 소유 형태 및 서비스 모델별(2022-2035년)
제8장 시장 규모 및 예측 : 광업 유형별(2022-2035년)
제9장 시장 규모 및 예측 : 지역별(2022-2035년)
제10장 기업 개요
KTH 26.08.20The Global Mining Remanufacturing Components Market was valued at USD 6.4 billion in 2025 and is estimated to grow at a CAGR of 7.3% to reach USD 12.9 billion by 2035.
One of the primary factors supporting market expansion is the significant cost advantage offered by remanufactured mining components compared with newly manufactured original equipment parts. Certified remanufactured products deliver comparable operational performance and reliability while providing substantial savings and warranty support, making them an increasingly attractive option for mining operators seeking to reduce maintenance expenses. The growing preference for extending equipment life and lowering total ownership costs has encouraged mining companies to incorporate remanufactured components into long-term maintenance and inventory strategies. In addition, the increasing focus on circular economy principles and corporate sustainability initiatives is strengthening demand for remanufacturing solutions across the mining sector. The wider adoption of condition monitoring technologies and predictive maintenance systems is further transforming equipment lifecycle management by enabling timely component replacement and planned remanufacturing. These developments continue to expand opportunities for the mining remanufacturing components market, as mining companies prioritize cost efficiency, operational reliability, and sustainable asset management across large-scale mining operations.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.4 Billion |
| Forecast Value | $12.9 Billion |
| CAGR | 7.3% |
The mine/haul truck segment accounted for 30% share in 2025 and is anticipated to register a 7.9% CAGR between 2026 and 2035. The segment maintains its leading position because haul trucks operate under demanding conditions that accelerate wear across critical mechanical systems. Replacing major assemblies with newly manufactured components requires significant capital investment, encouraging mining operators to adopt remanufactured alternatives that restore equipment performance while substantially reducing maintenance costs. Increasing fleet utilization and the need to maximize equipment availability continue to support strong demand for remanufactured components within this segment.
The metal mining segment held a 46.5% share in 2025. Growth is being driven by increasing global demand for mineral resources and continued investments in mining projects that support industrial development and expanding infrastructure requirements. Higher equipment utilization, greater material processing volumes, and more frequent maintenance cycles are increasing the need for remanufactured engines, hydraulic systems, transmissions, final drives, and other essential components. As mining companies focus on improving equipment productivity while controlling operating costs, demand for remanufactured solutions continues to strengthen across metal mining operations.
China Mining Remanufacturing Components Market accounted for 46% share, generating USD 977.1 million in 2025. The country's leadership is supported by the extensive scale of its mining industry and the large installed base of heavy mining equipment operating across multiple resource extraction activities. Continuous production schedules, high equipment utilization, and growing emphasis on extending machinery service life continue to increase demand for remanufactured components. Mining companies are increasingly integrating remanufacturing into fleet maintenance strategies to improve operational reliability, reduce maintenance expenditures, and maximize long-term asset performance.
Major companies operating in the global mining remanufacturing components market include Caterpillar Reman (Cat Reman), Komatsu Reman, Sandvik Component Exchange Program, Cummins ReCon, Epiroc Reman Program, H-E Parts International (HEPI), Liebherr Reman, Volvo CE Component Exchange, Bell Equipment ReMan, and Swanson Industries. Companies operating in the mining remanufacturing components market are strengthening their market position through investments in remanufacturing capacity, advanced refurbishment technologies, and expanded service capabilities. Leading participants focus on improving component quality, extending product life, and enhancing operational performance to meet evolving customer requirements. Strategic partnerships with mining companies, distributors, and equipment service providers help broaden market reach and strengthen long-term customer relationships. Businesses also prioritize digital condition monitoring, predictive maintenance solutions, and efficient inventory management to support timely component replacement and reduce equipment downtime. In addition, companies continue expanding regional service networks, increasing production capabilities, and investing in sustainable remanufacturing processes to improve operational efficiency, support circular economy objectives, and reinforce their competitive presence across the global mining industry.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Equipment Type
- 2.2.4 Ownership & Service Model
- 2.2.5 Mining Industry Type
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin analysis
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Cost Advantage of Remanufactured Components (25-60% Lower vs. New OEM Parts) Driving Adoption Among Mining Operators
- 3.2.1.2 Growing OEM Inventory Shortages & Extended Lead Times for New Components Accelerating Reman Demand
- 3.2.1.3 Rising Sustainability & Circular Economy Mandates Across Mining Corporations
- 3.2.1.4 Increasing Mining Activity Globally Driven by Critical Mineral & Energy Transition Demand
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Persistent Quality Perception Gap Mining Operators' Reluctance to Trust Remanufactured Parts Over New OEM Components
- 3.2.2.2 OEM Intellectual Property Restrictions Limiting Independent Remanufacturers' Access to Critical Component Designs
- 3.2.3 Market opportunities
- 3.2.3.1 Electrification of Mining Equipment - Emerging Reman Opportunity for Electric Drivetrain & Power Electronics Components
- 3.2.3.2 Digital & AI-Powered Reman Diagnostics - Opportunity to Standardize Quality & Reduce Costs at Scale
- 3.2.3.3 Expanding Mining Operations in Emerging Economies (Africa, Latin America, Southeast Asia) - Underserved by OEM Service Networks
- 3.2.3.4 Growth of Lease/Rental Fleet Models Driving Demand for Managed Component Lifecycle Services
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.1.1 Advanced Inspection & Non-Destructive Testing (NDT)
- 3.4.1.2 Automated Precision Machining & Component Restoration
- 3.4.1.3 Digital Condition Monitoring & Predictive Diagnostics
- 3.4.1.4 Reverse Engineering & Component Requalification
- 3.4.2 Emerging technologies
- 3.4.2.1 AI-Driven Defect Detection & Quality Inspection
- 3.4.2.2 Additive Manufacturing (Metal 3D Printing) for Component Restoration
- 3.4.2.3 Digital Twin-Based Lifecycle Prediction & Remanufacturing Planning
- 3.4.2.4 Generative AI for Remanufacturing Process Optimization
- 3.4.1 Current technological trends
- 3.5 Pricing Analysis (Driven by primary research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 U.S. EPA Tier 4 Final (Non-road Diesel Emissions Standards)
- 3.6.1.2 California Air Resources Board (CARB) Emissions Standards
- 3.6.1.3 Mine Safety and Health Administration (MSHA) Regulations
- 3.6.1.4 Canadian Environmental Protection Act (CEPA)
- 3.6.2 Europe
- 3.6.2.1 EU Stage V Emission Standards (Non-road Mobile Machinery)
- 3.6.2.2 EU Circular Economy Action Plan
- 3.6.2.3 Critical Raw Materials Act (EU 2024/1252)
- 3.6.2.4 REACH Regulation
- 3.6.2.5 NIS2 Directive
- 3.6.3 Asia Pacific
- 3.6.3.1 China Non-road Mobile Machinery Emission Standards (China IV)
- 3.6.3.2 Mines and Minerals (Development and Regulation) Act
- 3.6.3.3 Bharat Stage CEV V Emission Norms
- 3.6.3.4 Work Health and Safety (Mines) Regulations
- 3.6.3.5 National Clean Air Agreement / Off-road diesel regulations
- 3.6.3.6 Mine Health and Safety Act
- 3.6.3.7 National Environmental Management Act (NEMA)
- 3.6.4 Latin America
- 3.6.4.1 Chile Environmental Framework Law
- 3.6.4.2 Mexico LGEEPA Environmental Law
- 3.6.4.3 Peru Mining Environmental Regulations
- 3.6.5 Middle East & Africa
- 3.6.5.1 Saudi Mining Investment Law (Vision 2030 framework)
- 3.6.5.2 South Africa POPIA
- 3.6.5.3 South African Mine Health and Safety Act
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Patent analysis (Driven by primary research)
- 3.10 Cost breakdown analysis
- 3.11 Trade data analysis (Driven by Paid Research)
- 3.11.1 Import/export volume & value trends
- 3.11.2 Key trade corridors & tariff impact
- 3.12 Capacity & Production Landscape (Driven by Primary Research)
- 3.12.1 Installed Remanufacturing Capacity by Region & Key Producer
- 3.12.2 Capacity Utilization Rates & Expansion Pipelines
- 3.13 Impact of AI and Generative AI on the Market
- 3.13.1 AI Driven Disruption of Existing Business Models
- 3.13.2 GenAI Use Cases and Adoption Roadmap by Segment
- 3.13.3 Risks Limitations and Regulatory Considerations
- 3.14 Infrastructure & Deployment Landscape (Driven by Primary Research)
- 3.14.1 Deployment Penetration by Region & Buyer Segment
- 3.14.2 Scalability Constraints & Infrastructure Investment Trends
- 3.15 Sustainability and environmental aspects
- 3.15.1 Sustainable practices
- 3.15.2 Waste reduction strategies
- 3.15.3 Energy efficiency in production
- 3.15.4 Eco-friendly Initiatives
- 3.15.5 Carbon footprint considerations
- 3.16 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.16.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.16.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.16.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis (value and volume), 2022-2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Top 10 Company production & sales analysis, 2022-2035
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans and funding
- 4.7 Company tier benchmarking
- 4.7.1 Tier classification criteria & qualifying thresholds
- 4.7.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 (USD Mn, Units)
- 5.1 Key trends
- 5.2 Engine
- 5.3 Hydraulic Cylinder
- 5.4 Axle
- 5.5 Transmission
- 5.6 Differential
- 5.7 Torque Converter
- 5.8 Final Drive
- 5.9 Others
Chapter 6 Market Estimates & Forecast, By Equipment Type, 2022 - 2035 (USD Mn, Units)
- 6.1 Key trends
- 6.2 Hydraulic Excavator
- 6.3 Mine/Haul Truck
- 6.4 Wheel Loader
- 6.5 Wheel Dozer
- 6.6 Crawler Dozer
- 6.7 Drilling Rig
- 6.8 Others
Chapter 7 Market Estimates & Forecast, By Ownership & Service Model, 2022 - 2035 (USD Mn, Units)
- 7.1 Key trends
- 7.2 Contractor-Owned
- 7.3 Lease/Rental
Chapter 8 Market Estimates & Forecast, By Mining Industry Type, 2022 - 2035 (USD Mn, Units)
- 8.1 Key trends
- 8.2 Coal Mining
- 8.3 Metal Mining
- 8.4 Other Minerals
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 (USD Mn, Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 US
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Russia
- 9.3.7 Norway
- 9.3.8 Netherlands
- 9.3.9 Sweden
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.4.6 Singapore
- 9.4.7 Thailand
- 9.4.8 Indonesia
- 9.4.9 Vietnam
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
- 9.6.4 Turkey
Chapter 10 Company Profiles
- 10.1 Global Players
- 10.1.1 Caterpillar Reman
- 10.1.2 Komatsu Reman
- 10.1.3 Hitachi Construction Machinery Reman
- 10.1.4 Liebherr Reman
- 10.1.5 Epiroc Reman Program
- 10.1.6 Sandvik
- 10.1.7 Volvo CE Component Exchange
- 10.1.8 Cummins ReCon
- 10.1.9 Bosch Rexroth Reman
- 10.1.10 ZF REMAN (ZF Aftermarket)
- 10.1.11 Dana Certified Reman
- 10.1.12 Allison Transmission Genuine ReMan
- 10.1.13 BorgWarner Reman Solutions
- 10.1.14 Danfoss Power Solutions Reman
- 10.1.15 Detroit Diesel Remanufacturing (DDR)
- 10.1.16 Bell Equipment ReMan
- 10.2 Regional Players
- 10.2.1 H-E Parts International (HEPI)
- 10.2.2 Swanson Industries
- 10.2.3 Kymera International
- 10.2.4 R. Moore & Sons (RMS)
- 10.2.5 Centranz
- 10.2.6 Mine System Solutions (MSS)
- 10.2.7 OEM Remanufacturing (OEM Reman)
- 10.2.8 Swanson Industries Latin America


