

|
시장보고서
상품코드
2109215
항공기 페이로드 및 미션 관리 시스템 시장 : 시장 기회, 성장 촉진요인, 산업 동향 분석, 예측(2026-2035년)Aircraft Payload and Mission Management Systems Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 항공기 페이로드 및 미션 관리 시스템 시장은 2025년에 39억 달러로 평가되었고, CAGR 6.9%로 성장할 전망이며, 2035년까지 77억 달러에 이를 것으로 추정되고 있습니다.
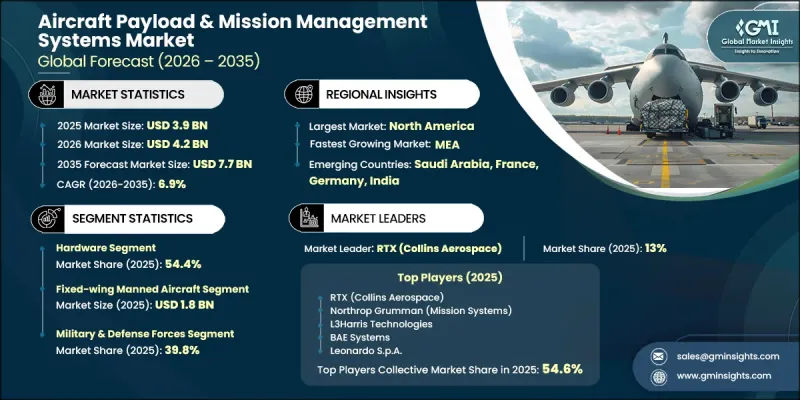
시장 확대는 군용기 현대화를 위한 투자 증가, 첨단 공중 정보 수집 능력에 대한 수요 증가, 그리고 복잡한 미션 운영을 효율적으로 관리해야 할 필요성이 높아짐에 따라 견인되고 있습니다. 방위 기관들은 통합된 미션 기술을 통해 처리 속도 향상, 연계 강화, 그리고 작전 상황 인식 향상을 가능하게 하는 시스템을 점점 더 우선시하고 있습니다. 무인 항공기 플랫폼 및 자율 시스템의 도입 확대는 유연한 탑재체 및 미션 관리 솔루션에 대한 수요를 더욱 강화하고 있습니다. 또한, 모듈식이며 확장성이 뛰어난 미션 아키텍처의 채택으로 인해 진화하는 국방 요구 사항에 대응할 수 있는 첨단 시스템의 개발이 촉진되고 있습니다. 실시간 정보·감시·정찰(ISR) 능력의 활용 확대 역시 군이 데이터 관리 및 의사 결정의 효율성 향상을 추구하는 가운데 시장 성장을 가속화하고 있습니다. 인공지능(AI) 및 자동화된 운용 기능의 통합은 분석 속도 향상, 대응 능력 강화, 미션 효율성 제고를 가능하게 하여 항공기 미션 수행 방식을 혁신하고 있습니다. 이러한 동향에 따라 항공기 페이로드 및 미션 관리 시스템 시장은 차세대 방위 항공 인프라의 핵심 구성 요소로서의 입지를 확립해 가고 있습니다.
| 시장 범위 | |
|---|---|
| 개시 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 초기 시장 규모 | 39억 달러 |
| 예측액 | 77억 달러 |
| CAGR | 6.9% |
군용기의 현대화가 진행됨에 따라 통합형 인텔리전스 및 센서 데이터 관리 솔루션에 대한 수요가 증가하고 있는 것이 시장 발전을 뒷받침하는 주요 요인으로 작용하고 있습니다. 현대 작전 환경에서는 여러 정보원에서 대량의 정보를 수집, 처리, 조정, 전달할 수 있는 첨단 항공기 탑재 시스템이 요구되고 있습니다. 미션 관리 플랫폼에 지능형 기술과 자율 기능을 통합함으로써 작전 효율이 향상되고, 항공기를 통한 미션 계획 및 실행 방식이 변화하고 있습니다.
2025년에는 하드웨어 부문이 시장 점유율의 54.4%를 차지하며 계속해서 주도적인 위치를 유지했습니다. 이 부문의 우위는 항공기 미션 운영을 가능하게 하는 데 있어 하드웨어 구성 요소가 수행하는 필수적인 역할에 의해 뒷받침되고 있습니다. 이러한 구성 요소는 페이로드 조정, 센서 데이터 통합, 미션 제어, 통신 관리 및 안전한 정보 교환에 필요한 기능을 제공합니다. 신뢰성이 높고 고성능인 미션 시스템에 대한 수요 증가는 군용 항공기 용도를 위한 첨단 하드웨어 솔루션에 대한 투자를 지속적으로 견인하고 있습니다.
2025년, 유인 고정익기 부문 시장 규모는 18억 달러에 달했습니다. 이 부문의 성장은 첨단 군용기 플랫폼 전반에 걸친 미션 관리 기술의 광범위한 도입에 힘입은 것입니다. 지속적인 기체 현대화 프로그램, 항공전자 장비 업그레이드, 그리고 기내 운용 능력 향상으로 인해 통합 페이로드 및 미션 관리 시스템의 도입이 확대되고 있습니다. 미션 조정 강화, 감시 능력 향상, 그리고 운용상의 유연성 확대에 대한 요구가 계속해서 이 부문 내 수요를 뒷받침하고 있습니다.
2025년, 북미의 항공기 페이로드 및 미션 관리 시스템 시장은 36.9%의 점유율을 차지했습니다. 이 지역의 성장은 진행 중인 군용기 현대화 이니셔티브, 첨단 정보 수집 및 감시 능력의 도입 확대, 그리고 방위 항공 플랫폼에 대한 첨단 미션 시스템의 지속적인 통합에 힘입고 있습니다. 이 지역의 방위 기관들은 첨단 페이로드 및 미션 관리 기술을 통해 작전 상황 파악, 안전한 통신 능력, 실시간 미션 조정 능력 향상에 주력하고 있으며, 이것이 시장의 지속적인 확장에 기여하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법 및 범위
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추산 및 예측 : 제공별(2022-2035년)
제6장 시장 추산 및 예측 : 제품 유형별(2022-2035년)
제7장 시장 추산 및 예측 : 미션 용도별(2022-2035년)
제8장 시장 추산 및 예측 : 최종 사용자별(2022-2035년)
제9장 시장 추산 및 예측 : 지역별(2022-2035년)
제10장 기업 개요
AJY 26.08.20The Global Aircraft Payload & Mission Management Systems Market was valued at USD 3.9 billion in 2025 and is estimated to grow at a CAGR of 6.9% to reach USD 7.7 billion by 2035.
Market expansion is driven by increasing investments in military aircraft modernization, rising demand for advanced airborne intelligence capabilities, and the growing requirement for efficient management of complex mission operations. Defense organizations are increasingly prioritizing systems that enable faster processing, improved coordination, and enhanced operational awareness through integrated mission technologies. The rising deployment of unmanned aerial platforms and autonomous systems is further strengthening demand for flexible payload and mission management solutions. In addition, the adoption of modular and scalable mission architectures is encouraging the development of advanced systems that can support evolving defense requirements. The increasing use of real-time intelligence, surveillance, and reconnaissance capabilities is also accelerating market growth as military forces seek improved data management and decision-making efficiency. Integration of artificial intelligence and automated operational features is transforming airborne mission execution by enabling faster analysis, improved responsiveness, and enhanced mission effectiveness. These trends are positioning the aircraft payload & mission management systems market as a critical component of next-generation defense aviation infrastructure.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.9 Billion |
| Forecast Value | $7.7 Billion |
| CAGR | 6.9% |
The increasing modernization of military aircraft and growing demand for integrated intelligence and sensor data management solutions are major factors supporting market development. Modern operational environments require advanced airborne systems capable of collecting, processing, coordinating, and distributing large volumes of information from multiple sources. The integration of intelligent technologies and autonomous capabilities within mission management platforms is improving operational efficiency and changing the approach to airborne mission planning and execution.
The hardware segment accounted for 54.4% share in 2025, maintaining its leading position. The segment's dominance is supported by the essential role of hardware components in enabling airborne mission operations. These components provide the necessary capabilities for payload coordination, sensor data integration, mission control, communication management, and secure information exchange. Increasing demand for reliable and high-performance mission systems continues to drive investments in advanced hardware solutions for military aviation applications.
The fixed-wing manned aircraft segment generated USD 1.8 billion in 2025. Growth in this segment is supported by the widespread implementation of mission management technologies across advanced military aircraft platforms. Continued fleet modernization programs, avionics upgrades, and improvements in airborne operational capabilities are increasing adoption of integrated payload and mission management systems. The need for enhanced mission coordination, improved surveillance capabilities, and greater operational flexibility continues to support demand within this segment.
North America Aircraft Payload & Mission Management Systems Market accounted for 36.9% share in 2025. Regional growth is supported by ongoing military aircraft modernization initiatives, increasing adoption of advanced intelligence and surveillance capabilities, and continued integration of sophisticated mission systems into defense aviation platforms. Defense organizations in the region are focusing on improving operational awareness, secure communication capabilities, and real-time mission coordination through advanced payload and mission management technologies, contributing to sustained market expansion.
Major companies operating in the global aircraft payload & mission management systems market include L3Harris Technologies, Northrop Grumman, RTX (Collins Aerospace), BAE Systems, Thales Group, Leonardo S.p.A., Lockheed Martin, Elbit Systems, Saab AB, Hensoldt AG, IAI, Airbus Defence & Space, Mercury Systems, Curtiss-Wright, General Atomics Aeronautical Systems, Inc. (GA-ASI), Sierra Nevada Corporation (SNC), Kratos Defense & Security Solutions, and Textron Systems. Companies operating in the aircraft payload & mission management systems market are strengthening their market presence through continuous innovation, strategic partnerships, and advanced system development. Leading players are investing in research and development to enhance mission capabilities, improve data processing efficiency, and integrate advanced technologies into airborne platforms. Companies are also focusing on modular system designs that provide flexibility, scalability, and compatibility with evolving defense requirements. Strategic collaborations with defense agencies, aircraft manufacturers, and technology providers help accelerate product deployment and expand global reach. In addition, organizations are increasing investments in lifecycle support services, modernization programs, and advanced manufacturing capabilities to improve customer relationships and maintain competitive advantage.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Offering trends
- 2.2.2 Product type trends
- 2.2.3 Mission application trends
- 2.2.4 End-user trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing military aircraft modernization and avionics upgrades
- 3.2.1.2 Growing need for real-time ISR and multi-sensor data fusion
- 3.2.1.3 Rapid adoption of unmanned and autonomous aerial platforms
- 3.2.1.4 Increasing adoption of modular and open mission system architectures
- 3.2.1.5 Rising defense expenditure and investment in advanced airborne mission capabilities
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost and complexity of advanced mission system integration
- 3.2.2.2 Cybersecurity and interoperability challenges in connected mission systems
- 3.2.3 Market opportunities
- 3.2.3.1 Development of AI-enabled autonomous mission management systems
- 3.2.3.2 Expansion of modular open mission systems and software-defined architectures
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Offering, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Hardware
- 5.3 Software
- 5.4 Services
Chapter 6 Market Estimates and Forecast, By Product Type, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Fixed-wing manned aircraft
- 6.3 Rotary-wing aircraft (Helicopters)
- 6.4 Unmanned aerial vehicles (UAVs)
Chapter 7 Market Estimates and Forecast, By Mission Application, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Intelligence, surveillance & reconnaissance (ISR)
- 7.3 Maritime patrol & anti-submarine warfare (ASW)
- 7.4 Electronic warfare (EW)
- 7.5 Airborne command & control (AEW&C/C2)
- 7.6 Search & rescue (SAR)
- 7.7 Border & coastal surveillance
- 7.8 Tactical strike & weapon management
Chapter 8 Market Estimates and Forecast, By End-User, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Military & defense forces
- 8.3 Homeland security & law enforcement
- 8.4 Civil & government agencies
- 8.5 Coast guard
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Russia
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 RTX (Collins Aerospace)
- 10.1.2 Northrop Grumman
- 10.1.3 L3Harris Technologies
- 10.1.4 BAE Systems
- 10.1.5 Leonardo S.p.A.
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Lockheed Martin
- 10.2.1.2 General Atomics Aeronautical Systems, Inc. (GA-ASI)
- 10.2.1.3 Textron Systems
- 10.2.2 Asia Pacific
- 10.2.2.1 Elbit Systems
- 10.2.2.2 IAI
- 10.2.3 Europe
- 10.2.3.1 Thales Group
- 10.2.3.2 Saab AB
- 10.2.3.3 Hensoldt AG
- 10.2.3.4 Airbus Defence & Space
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Mercury Systems
- 10.3.2 Curtiss-Wright
- 10.3.3 Sierra Nevada Corporation (SNC)
- 10.3.4 Kratos Defense & Security Solutions


