

|
시장보고서
상품코드
2121195
실험실 자동화 및 로보틱스 시장 기회, 성장 촉진요인, 업계 동향 분석 및 예측(2026-2035년)Lab Automation and Robotics Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 실험실 자동화 및 로보틱스 시장은 2025년에 72억 달러 규모에 달하고, CAGR 6.9%로 성장하여 2035년까지 137억 달러에 달할 것으로 추정됩니다.
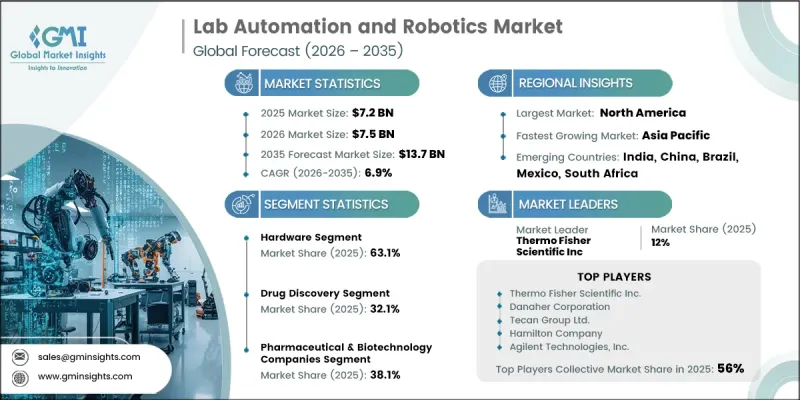
의료 기관, 연구 기관, 생명과학 기업들이 첨단 자동화 기술을 통해 실험실 업무의 현대화를 지속적으로 추진하고 있어, 실험실 자동화 및 로보틱스 업계는 꾸준한 성장을 이루고 있습니다. 실험실 워크플로우의 신속화, 검사 효율 향상, 업무 정확도 향상에 대한 수요가 증가함에 따라 자동화 실험실 시스템의 광범위한 도입이 촉진되고 있습니다. 의료 인프라에 대한 투자 확대, 연구 활동의 활성화, 의약품 개발의 지속적인 확대 또한 시장 성장을 더욱 뒷받침하고 있습니다. 자동화 기술을 통해 검사실은 수작업을 최소화하면서 생산성을 높이고, 워크플로우의 일관성을 높이며, 업무의 복잡성을 줄일 수 있게 됩니다. 로봇 기술, 소프트웨어, 자동화 하드웨어 및 디지털 데이터 관리를 결합한 통합 플랫폼은 검체 처리, 워크플로우 조정, 검사 효율 및 정보 관리를 개선함으로써 검사 업무를 혁신하고 있습니다. 전 세계적으로 진단 검사 건수가 증가함에 따라, 실험실은 일관된 성능을 유지하면서 더 큰 업무 부하를 처리할 수 있는 확장성이 뛰어난 솔루션을 원하고 있으며, 이것이 시장 수요를 지속적으로 가속화하고 있습니다. 질병의 조기 발견, 정밀 의료, 예방 의료에 대한 관심이 높아지고 있는 점도 검사 소요 시간 단축, 자원 활용 극대화, 의료 및 생명과학 분야 전반에 걸친 업무 효율 향상을 실현하는 지능형 실험실 자동화 시스템의 도입을 뒷받침하고 있습니다.
| 시장 범위 | |
|---|---|
| 시작 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 개시 금액 | 72억 달러 |
| 예측 금액 | 137억 달러 |
| CAGR | 6.9% |
2025년에는 하드웨어 부문이 63.1%의 점유율을 차지하며 최대 수익원이 되었습니다. 모든 자동화 워크플로는 실험실 업무를 정확하고 일관성 있게 수행하기 위해 신뢰할 수 있는 물리적 시스템에 의존하고 있기 때문에 하드웨어는 계속해서 실험실 자동화 인프라의 핵심을 이루고 있습니다. 대량 처리 능력이 뛰어난 실험실 업무에 대한 수요 증가, 생산성 향상 및 운영 정확도 개선에 힘입어 의료 기관, 연구 기관 및 생명과학 기업들은 첨단 자동화 장비에 대한 투자를 적극적으로 추진하고 있습니다. 실험실 시설의 지속적인 현대화와 지능형 자동화 기술 도입 확대에 힘입어, 예측 기간 동안 하드웨어에 대한 견조한 수요가 유지될 것으로 전망됩니다.
2025년에는 제약 및 생명공학 기업 부문이 38.1%의 점유율을 차지하며 최대 최종사용자 범주가 되었습니다. 의약품 연구, 바이오의약품 개발, 품질 보증 및 실험실 혁신에 대한 지속적인 투자가 이 부문에서 자동화 실험실 기술의 꾸준한 도입을 뒷받침하고 있습니다. 연구 프로그램이 점점 더 복잡해지고 개발 일정이 더욱 타이트해지는 가운데, 각 기관은 실험실 생산성을 향상시키고, 운영 효율을 최적화하며, 과학적 워크플로우를 가속화하고, 자원 활용을 극대화하기 위해 첨단 자동화 솔루션을 도입하고 있습니다. 생명과학 연구의 지속적인 확대로 인해 향후 몇 년간 이 부문의 주도적 입지가 더욱 공고해질 것으로 예상됩니다.
2025년, 북미의 실험실 자동화 및 로보틱스 시장은 39%의 점유율을 차지했습니다. 이 지역은 의약품 혁신, 생명공학 연구 및 첨단 의료 인프라에 대한 막대한 투자로 인해 계속해서 주도적인 위치를 유지하고 있습니다. 차세대 실험실 기술에 대한 강력한 수요로 인해 각 기관은 연구 생산성, 실험실 효율성 및 운영 성과를 향상시키는 자동화 워크플로우 도입을 확대하고 있습니다. 과학적 발견의 가속화, 데이터 품질 향상, 그리고 복잡한 연구 이니셔티브에 대한 지원이 점점 더 중요시됨에 따라, 이 지역의 각 연구소에서 로봇 공학 및 자동화 기술 도입이 지속적으로 진행되고 있으며, 이는 장기적인 시장 성장을 뒷받침하고 있습니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추정 및 예측 : 구성요소별, 2022-2035년
제6장 시장 추정 및 예측 : 용도별, 2022-2035년
제7장 시장 추정 및 예측 : 최종 용도별, 2022-2035년
제8장 시장 추정 및 예측 : 지역별, 2022-2035년
제9장 기업 개요
KSM 26.09.07The Global Lab Automation and Robotics Market was valued at USD 7.2 billion in 2025 and is estimated to grow at a CAGR of 6.9% to reach USD 13.7 billion by 2035.
The laboratory automation and robotics industry is experiencing steady expansion as healthcare organizations, research institutions, and life sciences companies continue to modernize laboratory operations through advanced automation technologies. Rising demand for faster laboratory workflows, improved testing efficiency, and enhanced operational accuracy is encouraging widespread implementation of automated laboratory systems. Growing investment in healthcare infrastructure, increasing research activities, and the continued expansion of pharmaceutical development are further supporting market growth. Automation technologies enable laboratories to improve productivity while minimizing manual intervention, enhancing workflow consistency, and reducing operational complexity. Integrated platforms that combine robotics, software, automation hardware, and digital data management are transforming laboratory operations by improving sample processing, workflow coordination, testing efficiency, and information management. The increasing volume of diagnostic testing worldwide continues to accelerate market demand as laboratories seek scalable solutions capable of processing larger workloads while maintaining consistent performance. Greater emphasis on early disease detection, precision medicine, and preventive healthcare is also contributing to the adoption of intelligent laboratory automation systems that improve turnaround times, maximize resource utilization, and support higher operational efficiency across healthcare and life sciences environments.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $7.2 Billion |
| Forecast Value | $13.7 Billion |
| CAGR | 6.9% |
The hardware segment accounted for a 63.1% share in 2025, making it the largest revenue-generating segment. Hardware remains the core component of laboratory automation infrastructure because every automated workflow depends on reliable physical systems to perform laboratory operations with precision and consistency. Increasing demand for high-volume laboratory processing, improved productivity, and greater operational accuracy is encouraging healthcare organizations, research laboratories, and life sciences companies to invest in advanced automation equipment. Continued modernization of laboratory facilities and growing implementation of intelligent automation technologies are expected to sustain strong demand for hardware throughout the forecast period.
The pharmaceutical and biotechnology companies segment held a 38.1% share in 2025, representing the largest end-user category. Ongoing investment in pharmaceutical research, biologics development, quality assurance, and laboratory innovation continues to support strong adoption of automated laboratory technologies within this segment. As research programs become increasingly complex and development timelines become more demanding, organizations are implementing advanced automation solutions to improve laboratory productivity, optimize operational efficiency, accelerate scientific workflows, and maximize resource utilization. The continued expansion of life sciences research is expected to reinforce the segment's leading position over the coming years.
North America Lab Automation and Robotics Market accounted for a 39% share in 2025. The region continues to maintain a leading position due to significant investment in pharmaceutical innovation, biotechnology research, and advanced healthcare infrastructure. Strong demand for next-generation laboratory technologies is encouraging organizations to expand the adoption of automated workflows that improve research productivity, laboratory efficiency, and operational performance. Increasing emphasis on accelerating scientific discovery, improving data quality, and supporting complex research initiatives is driving continued deployment of robotics and automation technologies throughout laboratories across the region, strengthening long-term market growth.
Major companies operating in the global lab automation and robotics market include Agilent Technologies, Inc., Becton, Dickinson and Company (BD), Bio-Rad Laboratories, Inc., Danaher Corporation (Beckman Coulter Life Sciences), Eppendorf SE, Hamilton Company, HighRes Biosolutions, Hudson Robotics, Inc., QIAGEN N.V., Revvity, Inc., Roche Diagnostics, Siemens Healthineers AG, SPT Labtech Ltd., Tecan Group Ltd., and Thermo Fisher Scientific Inc. Companies operating in the lab automation and robotics market are strengthening their competitive position by expanding investments in advanced robotics, intelligent automation platforms, artificial intelligence, and digital laboratory management technologies. Market participants are focusing on continuous research and development to enhance automation capabilities, improve software integration, and deliver more flexible laboratory solutions that support evolving customer requirements. Strategic collaborations with pharmaceutical companies, biotechnology firms, healthcare organizations, and research institutions are accelerating product adoption while expanding commercial opportunities. Companies also enhancing cloud connectivity, data analytics, workflow management, and system interoperability to improve laboratory efficiency and customer value.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy and data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy and data integrity commitment
- 1.3 Research trail and confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Component trends
- 2.2.2 Application trends
- 2.2.3 End use trends
- 2.2.4 Regional trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing adoption in drug discovery and development
- 3.2.1.2 Increasing need for optimizing clinical workflow
- 3.2.1.3 Rising investment in healthcare infrastructure
- 3.2.1.4 Rising clinical diagnostic testing volumes
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of robotic systems
- 3.2.2.2 Complex integration with existing laboratory infrastructure
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of precision medicine and genomics research
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by primary research)
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East and Africa
- 3.5 Technology landscape (Driven by primary research)
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies
- 3.6 Future market trends (Driven by primary research)
- 3.7 Impact of AI and Generative AI on the market (Driven by primary research)
- 3.8 Patent analysis
- 3.9 Pricing trend analysis (Driven by primary research)
- 3.10 Porter’s analysis
- 3.11 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 Global
- 4.2.2 North America
- 4.2.3 Europe
- 4.2.4 Asia Pacific
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers and acquisitions
- 4.6.2 Partnerships and collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Component, 2022 – 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 Automated liquid handling systems
- 5.2.2 Robotic arms and collaborative lab robots
- 5.2.3 Automated plate handlers, microplate readers, and washers
- 5.2.4 Automated storage and retrieval systems
- 5.3 Software and informatics
- 5.3.1 LIMS (Laboratory Information Management Systems)
- 5.3.2 Other software and informatics
- 5.4 Services
Chapter 6 Market Estimates and Forecast, By Application, 2022 – 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Drug Discovery
- 6.3 Genomics
- 6.4 Proteomics
- 6.5 Clinical diagnostics
- 6.6 Other applications
Chapter 7 Market Estimates and Forecast, By End Use, 2022 – 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Pharmaceutical & biotechnology companies
- 7.3 Diagnostic labs
- 7.4 Research & academic institutes
- 7.5 Contract research organizations & contract development manufacturing
- 7.6 Other end users
Chapter 8 Market Estimates and Forecast, By Region, 2022 – 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Agilent Technologies, Inc.
- 9.2 Becton, Dickinson and Company (BD)
- 9.3 Bio-Rad Laboratories, Inc.
- 9.4 Danaher Corporation (Beckman Coulter Life Sciences)
- 9.5 Eppendorf SE
- 9.6 Hamilton Company
- 9.7 HighRes Biosolutions
- 9.8 Hudson Robotics, Inc.
- 9.9 QIAGEN N.V.
- 9.10 Revvity, Inc.
- 9.11 Roche Diagnostics
- 9.12 Siemens Healthineers AG
- 9.13 SPT Labtech Ltd.
- 9.14 Tecan Group Ltd.
- 9.15 Thermo Fisher Scientific Inc.


