|
시장보고서
상품코드
2119930
고정식 화재 및 가스 감지 시스템 시장 : 제품 유형별(화재 감지 시스템, 고정식 가스 감지 시스템, 화재 및 가스 제어 시스템, 화재 경보 및 통보 시스템), 감지 기술별, 위험 유형별, 최종사용자별, 지역별 - 세계 예측(-2031년)Fixed Fire & Gas Detection Systems Market by Product (Fire Detection Systems, Fixed Gas Detection Systems, Fire & Gas Control Systems, Fire Alarm & Notification Systems), Detection Technology, Hazard Type, End User, and Region - Global Forecast to 2031 |
||||||

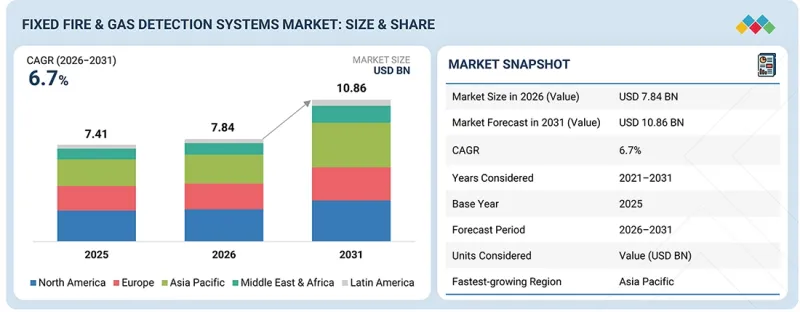
세계의 고정식 화재 및 가스 감지 시스템 시장 규모는 2026년 78억 4,000만 달러에서 2031년에는 108억 6,000만 달러로 성장할 것으로 예상되며, 예측 기간 동안 CAGR은 6.7%가 될 전망입니다.
시장 성장은 산업 안전에 대한 투자 증가, 노후화된 시설의 현대화, 위험이 수반되는 공정 산업의 확대, 노동 안전 규제 강화에 의해 주도되고 있습니다. LNG 인프라, 수소 생산, 탄소 포집 및 저장(CCS), 배터리 제조, 반도체 제조, 대규모 데이터센터에 대한 투자 증가가 첨단 화재 및 가스 감지 시스템에 대한 지속적인 수요를 창출하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) |
| 부문 | 제품, 기술, 위험 유형, 최종사용자 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
AI를 활용한 분석, 산업용 IoT(IIoT), 클라우드 연결, 무선 통신, 예측 유지보수의 통합을 통해 위험을 조기에 감지하고, 오경보를 줄이며, 운영 신뢰성을 높일 수 있게 되었습니다. 그러나 높은 도입 비용, 기존 산업 시스템과의 복잡한 통합, 지속적인 교정 및 유지보수의 필요성 등이, 특히 기존 시설(브라운필드)에서 시장 보급을 위한 과제로 여전히 남아 있습니다.
“초음파식 가스 누출 감지 시스템은 예측 기간 동안 가장 높은 성장률을 기록할 것으로 전망됩니다.”
초음파식 가스 누출 감지 시스템은 센서 주변의 가스 축적에 의존하지 않고, 가압 가스의 누출에 따른 음향 신호를 거의 즉각적으로 감지할 수 있기 때문에 예측 기간 동안 가장 빠르게 성장할 부문이 될 것으로 전망됩니다. 이러한 기능 덕분에 기존 포인트형 가스 감지기로는 감지가 늦어질 수 있는 개방된 공간, 환기가 잘 되는 환경, 풍량이 많은 환경에서도 누출을 더 신속하게 파악할 수 있습니다. 이 기술은 폭발, 화재, 예기치 못한 가동 중단을 방지하기 위해 신속한 누출 감지가 필수적인 해양 플랫폼, LNG 터미널, 수소 생산·저장 시설, 가스 압축 스테이션, 정유소, 석유화학 플랜트, 파이프라인 인프라 등에서 도입이 점점 더 확대되고 있습니다. 또한, 수소, LNG, 이산화탄소 포집 및 저장(CCS), 천연가스 인프라에 대한 투자 확대가 이 기술의 채택을 더욱 촉진하고 있습니다. 아울러 각 제조사는 초음파식 감지기를 IIoT 플랫폼,예지보수, 무선 통신, 사이버 보안 기능, 안전 계장 시스템(SIS)과 통합하고 있으며, 이를 통해 지속적인 모니터링, 원격 자산 관리, 운영 신뢰성 향상이 가능해졌습니다. 이러한 기술적 진보는 예측 기간 동안 각 벤더에게 큰 성장 기회를 가져다줄 것으로 전망됩니다.
“화재·화염 감지는 위험 유형별 시장에서 계속해서 가장 큰 점유율을 차지하고 있습니다.”
화재·화염 감지는 위험한 환경 하에서 인원, 산업 자산, 사업 운영을 보호하는 데 매우 중요한 역할을 하고 있으므로, 예측 기간 동안 최대 점유율을 차지할 것으로 예상됩니다. 화염 감지 시스템은 석유·가스 시설, 화학·석유화학 플랜트, 발전소, 광업 시설, 선박 및 해양 플랫폼,제조 시설, 교통 인프라, 그리고 신흥 수소 프로젝트 등에서 널리 도입되고 있으며, 이러한 장소에서는 안전상의 위험이나 가동 손실을 최소화하기 위해 화재의 조기 감지가 필수적입니다. 자외선(UV), 적외선(IR), UV/IR, 멀티스펙트럼 IR3와 같은 화염 감지 기술의 지속적인 발전으로 감지 속도가 대폭 향상되고, 오경보에 대한 내성이 강화되었으며, 가혹한 환경 조건 하에서의 성능도 개선되었습니다. 통합형 화재·가스 안전 시스템의 도입 확대에 더해, 산업 자동화, 디지털 안전 플랫폼, 규제 준수에 대한 투자 증가가 첨단 화재·화염 감지 솔루션에 대한 수요를 한층 더 끌어올리고 있습니다. 이러한 요인들로 인해, 해당 부문은 예측 기간 동안 시장에서 우위를 유지할 것으로 전망됩니다.
“예측 기간 동안 북미는 고정식 화재 및 가스 감지 시스템 시장을 주도할 것으로 예상됩니다.”
북미는 엄격한 산업 안전 규제, 성숙한 석유·가스 인프라, 첨단 제조 역량, 산업 자동화 기술의 광범위한 도입에 힘입어 예측 기간 동안 최대 지역 시장으로 자리매김할 것으로 예상됩니다. 이 지역에서는 LNG 수출 터미널, 수소 생산 시설, 화학 처리 플랜트, 데이터센터, 중요 인프라 현대화에 대한 투자가 지속적으로 이루어지고 있으며, 이러한 요인들이 지능형 화재 및 가스 감지 시스템의 수요를 견인하고 있습니다. 또한 Honeywell, MSA Safety, Emerson, Teledyne Technologies, Carrier Global, Johnson Controls와 같은 다수의 주요 제조사가 존재한다는 점도 지속적인 제품 혁신과 기술 도입을 뒷받침하고 있습니다.
한편, 아시아태평양은 중국, 인도, 한국, 일본, 동남아시아 전역의 급속한 산업화, 정제 및 석유화학 생산능력 확대, 청정에너지, 수소, 반도체 제조, 인프라 개발에 대한 투자 증가로 인해 가장 높은 성장률을 보일 것으로 예측됩니다. 노동 안전 규제의 강화, 산업 위험 관리에 대한 인식 제고, 스마트 제조 및 디지털 산업 인프라에 대한 투자 확대에 힘입어, 예측 기간 동안 해당 지역 전체에서 첨단 고정식 화재 및 가스 감지 시스템의 도입이 가속화될 것으로 전망됩니다.
본 보고서는 전 세계 고정식 화재 및 가스 감지 시스템 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 각종 요인 분석, 기술·특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 고정식 화재 및 가스 감지 시스템 시장 : 제품별
제10장 고정식 화재 및 가스 감지 시스템 시장 : 기술 유형별
제11장 고정식 화재 및 가스 감지 시스템 시장 : 위험 유형별
제12장 고정식 화재 및 가스 감지 시스템 시장 : 최종사용자별
제13장 고정식 화재 및 가스 감지 시스템 시장 : 지역별
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 부록
KSM 26.09.07The global fixed fire & gas detection systems market is projected to grow from USD 7.84 billion in 2026 to USD 10.86 billion by 2031, registering a CAGR of 6.7% during the forecast period. Market growth is driven by increasing investments in industrial safety, modernization of aging facilities, expansion of hazardous process industries, and stricter occupational safety regulations. Rising investments in LNG infrastructure, hydrogen production, carbon capture and storage (CCS), battery manufacturing, semiconductor fabrication, and large-scale data centers are creating sustained demand for advanced fire and gas detection systems.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Segments | Product, Technology, Hazard Type, and End User |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
The integration of AI-enabled analytics, Industrial Internet of Things (IIoT), cloud connectivity, wireless communication, and predictive diagnostics is enabling faster hazard detection, reduced false alarms, and improved operational reliability. However, high installation costs, complex integration with legacy industrial systems, and ongoing calibration and maintenance requirements continue to present challenges for market adoption, particularly in brownfield facilities.
"Ultrasonic gas leak detection systems are expected to register the highest growth during the forecast period."
Ultrasonic gas leak detection systems are projected to be the fastest-growing segment during the forecast period owing to their ability to detect the acoustic signature of pressurized gas leaks almost instantly, without relying on gas accumulation around the sensor. This capability enables faster leak identification in open, well-ventilated, and high-airflow environments where conventional point gas detectors may experience delayed detection. The technology is increasingly being deployed across offshore platforms, LNG terminals, hydrogen production and storage facilities, gas compressor stations, refineries, petrochemical plants, and pipeline infrastructure where rapid leak detection is essential for preventing explosions, fires, and unplanned shutdowns. Growing investments in hydrogen, LNG, carbon capture and storage (CCS), and natural gas infrastructure are further supporting adoption. Manufacturers are also integrating ultrasonic detectors with Industrial Internet of Things (IIoT) platforms, predictive diagnostics, wireless communication, cybersecurity features, and safety instrumented systems (SIS), enabling continuous monitoring, remote asset management, and improved operational reliability. These technological advancements are expected to create significant opportunities for vendors throughout the forecast period.
"Fire & flame detection continues to account for the largest share of the hazard type segment."
Among hazard types, fire & flame detection is expected to account for the largest share of the global fixed fire & gas detection systems market throughout the forecast period due to its critical role in protecting personnel, industrial assets, and business operations across hazardous environments. Flame detection systems are extensively deployed in oil & gas facilities, chemical and petrochemical plants, power generation stations, mining operations, marine and offshore platforms, manufacturing facilities, transportation infrastructure, and emerging hydrogen projects where early fire detection is essential to minimize safety risks and operational losses. Continuous advancements in ultraviolet (UV), infrared (IR), UV/IR, and multi-spectrum IR3 flame detection technologies have significantly enhanced detection speed, increased immunity to false alarms, and improved performance under harsh environmental conditions. The growing adoption of integrated fire and gas safety systems, combined with increasing investments in industrial automation, digital safety platforms, and regulatory compliance, continues to strengthen demand for advanced fire and flame detection solutions. These factors are expected to help the segment maintain its dominant market position throughout the forecast period.
"North America is expected to dominate the fixed fire & gas detection systems market during the forecast period."
North America is expected to remain the largest regional market for fixed fire & gas detection systems throughout the forecast period, supported by stringent industrial safety regulations, mature oil & gas infrastructure, advanced manufacturing capabilities, and widespread adoption of industrial automation technologies. The region continues to witness investments in LNG export terminals, hydrogen production facilities, chemical processing plants, data centers, and critical infrastructure modernization, driving demand for intelligent fire and gas detection systems. The strong presence of leading manufacturers such as Honeywell, MSA Safety, Emerson, Teledyne Technologies, Carrier Global, and Johnson Controls further supports continuous product innovation and technology adoption. Meanwhile, Asia Pacific is projected to register the fastest growth due to rapid industrialization, expanding refining and petrochemical capacity, increasing investments in clean energy, hydrogen, semiconductor manufacturing, and infrastructure development across China, India, South Korea, Japan, and Southeast Asia. Strengthening workplace safety regulations, rising awareness of industrial risk management, and growing investments in smart manufacturing and digital industrial infrastructure are expected to accelerate deployment of advanced fixed fire & gas detection systems across the region during the forecast period.
Breakdown of Primaries
In-depth interviews were conducted with chief executive officers (CEOs), vice presidents, product managers, safety engineers, system integrators, distributors, and executives from leading organizations operating in the fixed fire & gas detection systems market.
- By Company: Tier 1 -30%, Tier 2 - 45%, and Tier 3 - 25%
- By Designation: C-Level - 50%, Director/Manager Level - 35%, and Others - 15%
- By Region: North America - 50%, Europe - 30%, Asia Pacific - 15%, and the Rest of the World - 5%
The report profiles leading companies offering fixed fire & gas detection systems and provides detailed analysis of their business strategies, product portfolios, recent developments, and competitive positioning. Key companies profiled include Honeywell (US), Siemens (Germany), MSA Safety (US), Drager (Germany), Emerson (US), ABB (Switzerland), Schneider Electric (France), Johnson Controls (Ireland), Carrier Global (US), Bosch Building Technologies (Germany), Yokogawa Electric (Japan), Teledyne Technologies (US), Halma plc (UK), GfG Instrumentation (Germany), ESP Safety (US), International Gas Detectors (UK), Autronica Fire & Security (Norway), New Cosmos Electric (Japan), Nohmi Bosai (Japan), Hochiki Corporation (Japan), Kentec Electronics (UK), Riken Keiki (Japan), NevadaNano (US), Macurco Gas Detection (US), Hanwei Electronics (China), and Beijing AiSense Technology (China). These companies are actively focused on expanding their product portfolios through technological innovation, strategic partnerships, product launches, and acquisitions to strengthen their presence in the global fixed fire & gas detection systems market.
Research Coverage
The report segments the fixed fire & gas detection systems market by product (fire detection systems, fixed gas detection systems, fire & gas control systems, fire alarm & notification systems), technology (electrochemical, catalytic bead, infrared (NDIR), tunable diode laser absorption spectroscopy (TDLAS), photoionization detection (PID), acoustic detection, and others), hazard type (flammable & explosive gas detection, toxic gas detection, oxygen monitoring, fire & flame detection), end user (oil & gas, chemicals & petrochemicals, power generation & energy infrastructure, mining & metals, marine & offshore, manufacturing, water & wastewater treatment, pharmaceuticals & life sciences, transportation, food & beverage, data centers, and others), and region (North America, Europe, Asia Pacific, Middle East & Africa, and Latin America). The report provides detailed analysis of market dynamics, competitive landscape, technology trends, regulatory developments, recent product launches, partnerships, mergers & acquisitions, and strategic initiatives shaping the global fixed fire & gas detection systems market.
Reasons to buy this Report
The report helps technology providers, equipment manufacturers, system integrators, distributors, investors, and end users understand the competitive landscape and identify high-growth opportunities across the fixed fire & gas detection systems market. It provides market sizing and forecasts across multiple segments and regions, detailed company profiles, competitive benchmarking, technology analysis, and strategic insights into key market drivers, restraints, opportunities, and challenges. The study also supports decision-making by highlighting emerging technologies, evolving regulatory requirements, and growth opportunities across industrial safety applications.
The report provides insights on the following pointers:
- Analysis of key drivers (stringent industrial safety regulations and fire protection standards, increasing investments in oil & gas, petrochemicals, and LNG infrastructure, rising focus on worker safety and asset protection across high-risk industries, increasing industrial automation and adoption of integrated safety systems), restraints (high initial installation and system integration costs, complexity of installation in brownfield industrial facilities), opportunities (growing investments in hydrogen and clean energy infrastructure, expansion of hyperscale data centers requiring advanced fire detection), and challenges (growing investments in hydrogen and clean energy infrastructure, expansion of hyperscale data centers requiring advanced fire detection).
- Product Development/Innovation: Provides comprehensive insights into emerging technologies, research & development initiatives, new product launches, and advancements in fixed fire & gas detection systems, including flame detection, gas detection, fire alarm & notification, and integrated safety control solutions.
- Market Development: Delivers detailed analysis of high-growth market segments, key end-use industries, and regional opportunities across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America, enabling stakeholders to identify attractive investment areas.
- Market Diversification: Offers insights into new product innovations, evolving application areas, untapped regional markets, strategic partnerships, mergers & acquisitions, and investments that are shaping the competitive landscape of the fixed fire & gas detection systems market.
- Competitive Assessment: Provides an in-depth analysis of market positioning, product portfolios, recent developments, and growth strategies of leading companies including Honeywell (US), Siemens (Germany), MSA Safety (US), Drager (Germany), Emerson (US), ABB (Switzerland), Schneider Electric (France), Johnson Controls (Ireland), Carrier Global (US), Bosch Building Technologies (Germany), Yokogawa Electric (Japan), Teledyne Technologies (US), Halma plc (UK), GfG Instrumentation (Germany), ESP Safety (US), International Gas Detectors (UK), Autronica Fire & Security (Norway), New Cosmos Electric (Japan), Nohmi Bosai (Japan), Hochiki Corporation (Japan), Kentec Electronics (UK), Riken Keiki (Japan), NevadaNano (US), Macurco Gas Detection (US), Hanwei Electronics (China), and Beijing AiSense Technology (China). The report also provides detailed insights into key market drivers, restraints, opportunities, challenges, and the competitive dynamics influencing the global fixed fire & gas detection systems market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 3.2 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY PRODUCT
- 3.3 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY TECHNOLOGY TYPE
- 3.4 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY END USER
- 3.5 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Stringent industrial safety regulations and fire protection standards
- 4.2.1.2 Increasing investments in oil & gas, petrochemicals, and LNG infrastructure
- 4.2.1.3 Rising focus on worker safety and asset protection across high-risk industries
- 4.2.1.4 Increasing industrial automation and adoption of integrated safety systems
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial installation and system integration costs
- 4.2.2.2 Installation complexity in brownfield industrial facilities
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing investments in hydrogen and clean energy infrastructure
- 4.2.3.2 Expansion of hyperscale data centers requiring advanced fire detection
- 4.2.4 CHALLENGES
- 4.2.4.1 Minimizing false alarms while maintaining high detection accuracy
- 4.2.4.2 Ensuring reliable performance in harsh operating environments
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECASTS
- 5.2.3 TRENDS IN GLOBAL FIRE DETECTION INDUSTRY
- 5.2.4 TRENDS IN GLOBAL GAS DETECTION INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.3.1 RAW MATERIAL & COMPONENT SUPPLIERS
- 5.3.2 SENSOR & TECHNOLOGY PROVIDERS
- 5.3.3 FIRE & GAS DETECTION SYSTEM OEMS
- 5.3.4 DISTRIBUTORS/CHANNEL PARTNERS
- 5.3.5 SYSTEM INTEGRATORS & EPC CONTRACTORS
- 5.3.6 INDUSTRIAL END USERS
- 5.3.7 AFTERMARKET SERVICES, CALIBRATION & MAINTENANCE PROVIDERS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE, BY PRODUCT, 2026
- 5.5.2 INDICATIVE PRICING ANALYSIS OF FIXED FIRE DETECTION SYSTEMS, BY VENDOR, 2026
- 5.6 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 CASE STUDY 1: LANXESS ENHANCES PLANT SAFETY WITH HONEYWELL'S INTEGRATED FIRE & GAS DETECTION SYSTEM
- 5.9.2 CASE STUDY 2: MAJOR LNG TERMINAL IN GUJARAT ENHANCES GAS DETECTION WITH MSA SAFETY'S SENSCIENT ELDS SOLUTION
- 5.9.3 CASE STUDY 3: SCOTTISH WATER IMPROVES CHLORINE SAFETY WITH CROWCON'S FIXED GAS DETECTION SOLUTION
- 5.9.4 CASE STUDY 4: AAR MRO SERVICES STRENGTHENS AIRCRAFT HANGAR FIRE PROTECTION WITH DET-TRONICS FLAME DETECTION SOLUTION
- 5.10 IMPACT OF 2025 US TARIFF - FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRIES/REGIONS
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON VERTICALS
- 5.10.5.1 Oil & gas
- 5.10.5.2 Chemical & petrochemical
- 5.10.5.3 Power generation & energy infrastructure
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.1.1.1 Infrared (IR) & non-dispersive infrared (NDIR) gas detection
- 6.1.1.2 Electrochemical gas detection
- 6.1.1.3 Catalytic bead (pellistor) gas detection
- 6.1.1.4 UV/IR & multi-spectrum infrared (MSIR) flame detection
- 6.1.1.5 Ultrasonic & open path gas leak detection (TDLAS/IR)
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Industrial Internet of Things (IIoT) connectivity
- 6.1.2.2 SCADA & distributed control system (DCS) integration
- 6.1.2.3 AI-based alarm analytics & predictive maintenance
- 6.1.2.4 Edge computing & cloud-based remote monitoring
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Safety instrumented systems (SIS)
- 6.1.3.2 Process automation systems
- 6.1.3.3 Building management systems (BMS)
- 6.1.3.4 Industrial video surveillance & thermal imaging
- 6.1.1 KEY EMERGING TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT-TERM (2026-2028) | SMART DETECTION & DIGITAL SAFETY INTEGRATION
- 6.2.2 MID-TERM (2028-2031) | AUTONOMOUS SAFETY MONITORING & INTELLIGENT INDUSTRIAL PROTECTION
- 6.2.3 LONG-TERM (2031-2036+) | AUTONOMOUS, AI-DRIVEN, & PREDICTIVE SAFETY ECOSYSTEMS
- 6.3 PATENT ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 AI-DRIVEN PREDICTIVE FIRE & GAS RISK MANAGEMENT
- 6.4.2 AUTONOMOUS INDUSTRIAL SAFETY & EMERGENCY RESPONSE
- 6.4.3 HYDROGEN, CARBON CAPTURE, & CLEAN ENERGY SAFETY SYSTEMS
- 6.4.4 DIGITAL TWIN-ENABLED INDUSTRIAL SAFETY MANAGEMENT
- 6.4.5 REMOTE & AUTONOMOUS ASSET PROTECTION FOR CRITICAL INFRASTRUCTURE
- 6.5 IMPACT OF AI/GENERATIVE AI ON FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 6.5.3 CASE STUDY OF AI IMPLEMENTATION IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN FIXED FIRE & GAS DETECTION SYSTEM MARKET
7 REGULATORY LANDSCAPE
- 7.1 REGULATORY LANDSCAPE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS, BY REGION
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Middle East & Africa
- 7.1.2.5 Latin America
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USER INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY PRODUCT
- 9.1 INTRODUCTION
- 9.1.1 BY PRODUCT: FIXED FIRE & GAS DETECTION SYSTEM MARKET DRIVERS
- 9.2 FIRE DETECTION SYSTEMS
- 9.2.1 FIXED FIRE DETECTION SYSTEMS ENABLE EARLY FIRE IDENTIFICATION ACROSS CRITICAL INFRASTRUCTURE
- 9.2.2 FLAME DETECTION SYSTEMS
- 9.2.2.1 UV flame detectors
- 9.2.2.2 IR flame detectors
- 9.2.2.3 UV/IR flame detectors
- 9.2.2.4 Multi-spectrum IR flame detectors
- 9.2.3 SMOKE DETECTION SYSTEMS
- 9.2.3.1 Aspirating smoke detection (ASD) systems
- 9.2.3.2 Point smoke detectors
- 9.2.4 HEAT DETECTION SYSTEMS
- 9.2.5 VIDEO FIRE DETECTION SYSTEMS
- 9.3 FIXED GAS DETECTION SYSTEMS
- 9.3.1 GROWING INVESTMENTS IN PROCESS SAFETY SUPPORT DEMAND FOR FIXED GAS DETECTION SYSTEMS
- 9.3.2 COMBUSTIBLE GAS DETECTION SYSTEMS
- 9.3.3 TOXIC GAS DETECTION SYSTEMS
- 9.3.4 OXYGEN DETECTION SYSTEMS
- 9.3.5 OPEN-PATH GAS DETECTION SYSTEMS
- 9.3.6 ULTRASONIC GAS LEAK DETECTION SYSTEMS
- 9.4 FIRE & GAS CONTROL SYSTEMS
- 9.4.1 INTEGRATED SAFETY ARCHITECTURES DRIVE ADOPTION OF ADVANCED FIRE & GAS CONTROL SYSTEMS
- 9.4.2 FIRE & GAS CONTROLLERS
- 9.4.3 SAFETY LOGIC SOLVERS
- 9.4.4 HUMAN MACHINE INTERFACES (HMIS)
- 9.5 FIRE ALARM & NOTIFICATION SYSTEMS
- 9.5.1 MODERNIZATION OF EMERGENCY COMMUNICATION INFRASTRUCTURE SUPPORTS DEMAND FOR FIRE ALARM & NOTIFICATION SYSTEMS
- 9.5.2 FIRE ALARM PANELS
- 9.5.3 SOUNDERS
- 9.5.4 BEACONS/STROBES
- 9.5.5 NOTIFICATION DEVICES
10 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY TECHNOLOGY TYPE
- 10.1 INTRODUCTION
- 10.1.1 TECHNOLOGY TYPE: FIXED FIRE & GAS DETECTION SYSTEM MARKET DRIVERS
- 10.2 ELECTROCHEMICAL DETECTION
- 10.2.1 HIGH-PRECISION TOXIC GAS MONITORING THROUGH ELECTROCHEMICAL SENSING
- 10.3 CATALYTIC BEAD DETECTION
- 10.3.1 RELIABLE COMBUSTIBLE GAS DETECTION FOR EXPLOSION PREVENTION
- 10.4 TUNABLE DIODE LASER ABSORPTION SPECTROSCOPY (TDLAS)
- 10.4.1 LONG-RANGE OPEN-PATH GAS MONITORING WITH LASER-BASED PRECISION
- 10.5 PHOTOIONIZATION DETECTION (PID)
- 10.5.1 SENSITIVE DETECTION OF VOLATILE ORGANIC COMPOUNDS AND HAZARDOUS VAPORS
- 10.6 ACOUSTIC DETECTION
- 10.6.1 EARLY IDENTIFICATION OF PRESSURIZED GAS LEAKS THROUGH ULTRASONIC SENSING
- 10.7 OTHER TECHNOLOGIES
11 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY HAZARD TYPE
- 11.1 INTRODUCTION
- 11.1.1 HAZARD TYPE: FIXED FIRE & GAS DETECTION SYSTEM MARKET DRIVERS
- 11.2 FLAMMABLE & EXPLOSIVE GAS DETECTION
- 11.2.1 PREVENTING IGNITION RISKS ACROSS HYDROCARBON PROCESSING FACILITIES
- 11.3 TOXIC GAS DETECTION
- 11.3.1 PROTECTING PERSONNEL FROM HAZARDOUS CHEMICAL EXPOSURE
- 11.4 FIRE & FLAME DETECTION
- 11.4.1 RAPID IDENTIFICATION OF FIRE EVENTS TO MINIMIZE ASSET DAMAGE
12 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.1.1 END USER: FIXED FIRE & GAS DETECTION SYSTEM MARKET DRIVERS
- 12.2 OIL & GAS
- 12.2.1 LARGEST INSTALLED BASE FOR INDUSTRIAL FIRE & GAS DETECTION SYSTEMS
- 12.3 CHEMICALS & PETROCHEMICALS
- 12.3.1 MANAGING DIVERSE PROCESS HAZARDS IN CHEMICAL MANUFACTURING
- 12.4 POWER GENERATION & ENERGY INFRASTRUCTURE
- 12.4.1 STRENGTHENING SAFETY ACROSS CONVENTIONAL AND EMERGING ENERGY ASSETS
- 12.5 MINING & METALS
- 12.5.1 MITIGATING FIRE AND GAS RISKS ACROSS EXTRACTION AND PROCESSING OPERATIONS
- 12.6 MARINE & OFFSHORE
- 12.6.1 SUPPORTING SAFETY COMPLIANCE IN OFFSHORE AND MARITIME OPERATIONS
- 12.7 MANUFACTURING
- 12.7.1 IMPROVING INDUSTRIAL SAFETY ACROSS DIVERSE MANUFACTURING ENVIRONMENTS
- 12.8 WATER & WASTEWATER TREATMENT
- 12.8.1 PROTECTING CRITICAL INFRASTRUCTURE FROM TOXIC GAS EXPOSURE
- 12.9 PHARMACEUTICALS & LIFE SCIENCES
- 12.9.1 MAINTAINING PROCESS INTEGRITY IN HIGHLY REGULATED PRODUCTION FACILITIES
- 12.10 TRANSPORTATION
- 12.10.1 ENHANCING SAFETY ACROSS TRANSPORTATION AND TRANSIT INFRASTRUCTURE
- 12.11 FOOD & BEVERAGES
- 12.11.1 SUPPORTING SAFE PRODUCTION AND REFRIGERATION OPERATIONS
- 12.12 DATA CENTERS
- 12.12.1 SAFEGUARDING MISSION-CRITICAL DIGITAL INFRASTRUCTURE
- 12.13 OTHERS
13 FIXED FIRE & GAS DETECTION SYSTEM MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Large installed industrial base and safety system upgrades to sustain market
- 13.2.2 CANADA
- 13.2.2.1 Mining expansion and resource processing investments to increase fixed fire & gas detection requirements
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Established offshore and process industries alongside new hydrogen projects to maintain fixed fire & gas detection demand
- 13.3.2 GERMANY
- 13.3.2.1 Large chemical industry base and hydrogen network buildout to create new fixed fire & gas detection requirements
- 13.3.3 FRANCE
- 13.3.3.1 Large nuclear power base and industrial safety upgrades to maintain fixed fire & gas detection demand
- 13.3.4 ITALY
- 13.3.4.1 Refining and gas infrastructure upgrades to maintain demand as hydrogen projects add new detection requirements
- 13.3.5 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Expanding petrochemical capacity and stronger hazardous chemical safety requirements to increase fixed detection system demand
- 13.4.2 JAPAN
- 13.4.2.1 Aging industrial facilities and new hydrogen applications to support fixed fire & gas detection systems upgrades
- 13.4.3 INDIA
- 13.4.3.1 Rapid refining and petrochemical capacity addition to result in new fixed fire & gas detection installations
- 13.4.4 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 GCC
- 13.5.1.1 Saudi Arabia
- 13.5.1.1.1 Gas production growth and new petrochemical capacity to increase fixed fire & gas detection installations
- 13.5.1.2 UAE
- 13.5.1.2.1 Expansion of chemical production and gas processing facilities to increase fixed fire & gas detection requirements
- 13.5.1.3 Rest of GCC
- 13.5.1.1 Saudi Arabia
- 13.5.2 SOUTH AFRICA
- 13.5.2.1 Oil & gas developments and mineral processing projects to increase fixed fire & gas detection requirements
- 13.5.3 REST OF MIDDLE EAST & AFRICA
- 13.5.1 GCC
- 13.6 LATIN AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Offshore oil production and refinery investments to increase fixed fire & gas detection requirements
- 13.6.2 MEXICO
- 13.6.2.1 Refinery modernization and petrochemical recovery to increase fixed fire & gas detection requirements
- 13.6.3 REST OF LATIN AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2022-2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.5 BRAND/PRODUCT COMPARISON
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Product footprint
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS OF KEY VENDORS
- 14.8.1 COMPANY VALUATION OF KEY VENDORS
- 14.8.2 FINANCIAL METRICS OF KEY VENDORS
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
15 COMPANY PROFILES
- 15.1 INTRODUCTION
- 15.2 MAJOR PLAYERS
- 15.2.1 HONEYWELL
- 15.2.1.1 Business overview
- 15.2.1.2 Products/Solutions/Services offered
- 15.2.1.3 Recent developments
- 15.2.1.3.1 Product launches & enhancements
- 15.2.1.3.2 Deals
- 15.2.1.4 MnM View
- 15.2.1.4.1 Right to win
- 15.2.1.4.2 Strategic choices
- 15.2.1.4.3 Weaknesses and competitive threats
- 15.2.2 SIEMENS
- 15.2.2.1 Business overview
- 15.2.2.2 Products/Solutions/Services offered
- 15.2.2.3 Recent developments
- 15.2.2.3.1 Product launches & enhancements
- 15.2.2.3.2 Deals
- 15.2.2.4 MnM View
- 15.2.2.4.1 Right to win
- 15.2.2.4.2 Strategic choices
- 15.2.2.4.3 Weaknesses and competitive threats
- 15.2.3 JOHNSON CONTROLS
- 15.2.3.1 Business overview
- 15.2.3.2 Products/Solutions/Services offered
- 15.2.3.3 Recent developments
- 15.2.3.3.1 Product launches & enhancements
- 15.2.3.3.2 Deals
- 15.2.3.4 MnM View
- 15.2.3.4.1 Right to win
- 15.2.3.4.2 Strategic choices
- 15.2.3.4.3 Weaknesses and competitive threats
- 15.2.4 EMERSON
- 15.2.4.1 Business overview
- 15.2.4.2 Products/Solutions/Services offered
- 15.2.4.3 Recent developments
- 15.2.4.3.1 Product launches & enhancements
- 15.2.4.3.2 Deals
- 15.2.4.3.3 Expansions
- 15.2.4.4 MnM View
- 15.2.4.4.1 Right to win
- 15.2.4.4.2 Strategic choices
- 15.2.4.4.3 Weaknesses and competitive threats
- 15.2.5 MSA SAFETY INCORPORATED
- 15.2.5.1 Business overview
- 15.2.5.2 Products/Solutions/Services offered
- 15.2.5.3 Recent developments
- 15.2.5.3.1 Product launches & enhancements
- 15.2.5.3.2 Deals
- 15.2.5.4 MnM View
- 15.2.5.4.1 Right to win
- 15.2.5.4.2 Strategic choices
- 15.2.5.4.3 Weaknesses and competitive threats
- 15.2.6 DRAGER
- 15.2.6.1 Business overview
- 15.2.6.2 Products/Solutions/Services offered
- 15.2.6.3 Recent developments
- 15.2.6.3.1 Product launches & enhancements
- 15.2.6.3.2 Deals
- 15.2.7 TELEDYNE TECHNOLOGIES
- 15.2.7.1 Business overview
- 15.2.7.2 Products/Solutions/Services offered
- 15.2.7.3 Recent developments
- 15.2.7.3.1 Product launches & enhancements
- 15.2.7.3.2 Deals
- 15.2.8 SCHNEIDER ELECTRIC
- 15.2.8.1 Business overview
- 15.2.8.2 Products/Solutions/Services offered
- 15.2.8.3 Recent developments
- 15.2.8.3.1 Product launches & enhancements
- 15.2.8.3.2 Deals
- 15.2.9 ABB
- 15.2.9.1 Business overview
- 15.2.9.2 Products/Solutions/Services offered
- 15.2.9.3 Recent developments
- 15.2.9.3.1 Product launches & enhancements
- 15.2.10 CROWCON
- 15.2.10.1 Business overview
- 15.2.10.2 Products/Solutions/Services offered
- 15.2.10.3 Recent developments
- 15.2.10.3.1 Product launches & enhancements
- 15.2.10.3.2 Deals
- 15.2.11 YOKOGAWA
- 15.2.11.1 Business overview
- 15.2.11.2 Products/Solutions/Services offered
- 15.2.11.3 Recent developments
- 15.2.11.3.1 Deals
- 15.2.11.3.2 Other developments
- 15.2.12 ROCKWELL AUTOMATION
- 15.2.12.1 Business overview
- 15.2.12.2 Products/Solutions/Services offered
- 15.2.12.3 Recent developments
- 15.2.12.3.1 Product launches & enhancements
- 15.2.12.3.2 Deals
- 15.2.13 BOSCH BUILDING TECHNOLOGIES
- 15.2.13.1 Business overview
- 15.2.13.2 Products/Solutions/Services offered
- 15.2.13.3 Recent developments
- 15.2.13.3.1 Product launches & enhancements
- 15.2.13.3.2 Deals
- 15.2.13.3.3 Expansions
- 15.2.14 DET-TRONICS
- 15.2.14.1 Business overview
- 15.2.14.2 Products/Solutions/Services offered
- 15.2.14.3 Recent developments
- 15.2.14.3.1 Product launches & enhancements
- 15.2.14.3.2 Deals
- 15.2.1 HONEYWELL
- 15.3 OTHER PLAYERS
- 15.3.1 GFG SAFETY
- 15.3.2 ESP SAFETY
- 15.3.3 INTERNATIONAL GAS DETECTORS (IGD)
- 15.3.4 NOHMI BOSAI LTD.
- 15.3.5 RIKEN KEIKI
- 15.3.6 HANWEI ELECTRONICS
- 15.3.7 GDS CORP.
- 15.3.8 HOCHIKI AMERICA CORPORATION
- 15.3.9 ADVANCED ELECTRONICS
- 15.3.10 HENAN OTYWELL ELECTRONIC TECHNOLOGY CO., LTD.
- 15.3.11 RESPO PRODUCTS
- 15.3.12 PENTAX ENGINEERING PVT. LTD.
- 15.3.13 WATCHGAS
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.2 PRIMARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.3 DATA TRIANGULATION
- 16.4 FACTOR ANALYSIS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS