|
시장보고서
상품코드
2129360
뉴트라슈티컬 원료 시장 예측(-2031년) : 기능별, 성분 유형별, 유래별, 용도별, 지역별Nutraceutical Ingredients Market by Ingredient Type (Functional Proteins, Amino Acids, Probiotics, Others), Application (Human Nutrition, Animal Nutrition), Source (Plant-Based, Animal-Based, Others), Function, and Region - Global Forecast to 2031 |
||||||

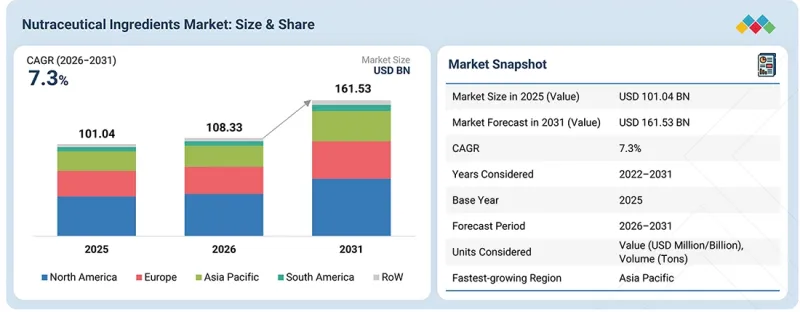
뉴트라슈티컬 원료 시장 규모는 2026년 1,083억 3,000만 달러에서 2031년에는 1,615억 3,000만 달러로, CAGR 7.3%로 확대할 것으로 예측됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만/10억 달러), 톤 |
| 부문 | 기능별, 성분 유형별, 유래별, 용도별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 남미, 기타 지역 |
"스포츠 및 특수 영양 분야에서 아미노산 사용이 확대됨에 따라 시장 성장이 견인될 것으로 예상됩니다."
아미노산은 스포츠 영양 식품, 영양 보조 식품 및 특수 영양 제품, 특히 근육 회복, 신체 능력 향상, 단백질 섭취를 지원하도록 설계된 제품에 점점 더 많이 함유되고 있습니다. 분지쇄 아미노산, 필수 아미노산, 비필수 아미노산 및 특수 아미노산은 광범위한 제품에 이용되고 있으며, 특히 분지쇄 아미노산은 운동 성능과 회복을 목적으로 하는 스포츠 영양 제품에서 널리 사용되고 있습니다. 표준화되고 고순도 형태로 구할 수 있으므로 제조업체는 분말, 캡슐, 정제, 기능성 음료 등의 제품을 개발할 수 있습니다. 또한 발효 기반 생산 기술의 발전으로 아미노산 제조의 효율, 균일성 및 확장성이 향상되어 다양한 배합 요건에 부응하는 원료 공급을 지원하고 있습니다. 스포츠 영양, 활동적인 노화, 특수 영양 제품의 지속적인 개발로 인해 영양 기능성 식품 분야에서 아미노산의 활용 범위는 더욱 확대되고 있습니다.
"시장 성장을 지원하는 동물 유래 뉴트라슈티컬 원료의 확립된 영양적·기능적 이점."
원료별로 보면 동물 유래 부문은 동물 유래 원료의 높은 영양가, 생체 이용률 및 입증된 기능적 이점에 힘입어 뉴트라슈티컬 원료 시장에서 큰 점유율을 차지하고 있습니다. 동물 유래 원료는 관절, 뼈, 근육, 심혈관, 피부, 인지 기능의 건강을 목표로 하는 제품에 사용되는 다양한 고부가가치 영양소 및 생리활성 물질을 제공합니다. 스포츠 영양 분야에서 입증된 사용 실적은 특히 단백질 파우더, 식사 대체품, 회복 음료 등 단백질 기반 제품에 대한 수요를 더욱 부추기고 있습니다. 동물 유래 원료는 영유아 및 생후 초기 영양에서도 중요한 역할을 하고 있으며, 성장과 발육을 지원하도록 설계된 배합에 유단백질이나 특수 성분이 사용되고 있습니다. 또한 의료용 및 특수 영양 분야에서의 활용은 그 영양적 품질과 확립된 과학적 근거에 의해 지원되며, 특히 영양실조, 근육량 감소, 회복, 노화에 따른 영양 요구를 충족시키는 제품에서 두드러집니다. 스포츠, 영유아, 의료, 건강한 노화를 목표로 하는 영양 분야에 걸친 이러한 확립된 용도가 동물 유래 기능성 식품 원료에 대한 수요를 지속적으로 지원하고 있습니다.
"북미는 견고한 소비자 수요와 확립된 영양 보조제 산업 덕분에 뉴트라슈티컬 원료 시장에서 큰 점유율을 차지할 것으로 예상됩니다."
북미는 영양 보충제의 활발한 소비, 예방 의학에 대한 소비자의 높은 인식, 그리고 기능성 영양 제품에 대한 수요 확대에 힘입어 뉴트라슈티컬 원료 시장에서 큰 점유율을 차지할 것으로 예상됩니다. 이 지역에서는 면역, 심장 건강, 소화기 건강, 스포츠 영양, 건강한 노화 등의 용도로 사용되는 영양보조식품 시장이 확립되어 있습니다. 가처분 소득과 의료비 지출이 높아, 프리미엄 웰니스, 영양, 건강 제품에 대한 소비자 구매 의욕을 지원하고 있습니다. 또한 단백질 강화 식품, 프로바이오틱스 제품, 기능성 유제품, 에너지 드링크 및 스포츠 음료, 영양 강화 음료 등을 포함한 확고한 기능성 식품 및 음료 시장이 뉴트라슈티컬 원료에 대한 안정적인 수요를 창출하고 있습니다. 고령화가 진행됨에 따라 관절, 뼈, 인지 기능, 심혈관 및 건강한 노화를 지원하는 제품에 대한 수요가 더욱 높아지는 한편, 활발한 스포츠 및 액티브 영양 산업이 단백질 원료, 아미노산, 기능성 영양 원료의 활용을 지원하고 있습니다.
뉴트라슈티컬 원료 시장의 주요 기업으로는 Cargill, Incorporated(미국), ADM(미국), International Flavors & Fragrances Inc.(미국), BASF SE(독일),글랜비아 PLC(아일랜드), 아르라 푸드 amba(덴마크), dsm-firmenich(네덜란드), 인그레디언 인코포레이티드(미국), 테이트 앤 라일 PLC(영국), 로켓 프레르(프랑스), 어소시에이티드 브리티시 푸드 PLC(영국),Fonterra Co-operative Group Limited(뉴질랜드), Kerry Group PLC(아일랜드), Novonesis Group(덴마크), Balchem Corporation(미국), Ajinomoto Co., Inc.(일본), Divi's Laboratories Limited(인도), Kemin Industries(미국),GELITA AG(독일), BENEO GmbH(독일), Cosucra Groupe Warcoing SA(벨기에), Conagen Inc.(미국), Sarshika Pharmachem LLP(인도), Canurta Naturals USA(미국), EVANIUM(미국) 등이 있습니다.
조사 범위
본 조사 보고서에서는 뉴트라슈티컬 원료 시장을 원료의 유형(기능성 단백질, 오메가-3 지방산, 프로바이오틱스, 프리바이오틱스,식이섬유 및 특수 탄수화물, 비타민 [비타민 A, 비타민 B, 비타민 C, 비타민 D, 비타민 E, 기타], 미네랄 [칼슘, 마그네슘, 철, 아연, 기타 미네랄], 아미노산 [분지쇄 아미노산, 필수 아미노산, 비필수 아미노산, 특수 아미노산], 카로티노이드, 기타 유형) 및원료 출처(식물 유래, 동물 유래, 미생물 유래, 합성), 기능(영양 지원, 소화기 건강, 면역 건강, 심혈관 건강, 뼈·관절 건강, 인지·정신건강, 스포츠·퍼포먼스, 체중 관리, 기타),및 용도(인간용 영양[영양보조식품, 기능성 식품, 기능성 음료, 의료·특수 영양, 영유아·생후 초기 영양], 동물용 영양[반려동물용 영양, 가축용 영양, 수산양식용 영양, 기타 동물용 영양]), 그리고 지역(북미, 유럽,아시아태평양, 남미, 기타 지역)입니다.
이 보고서의 조사 범위에는 뉴트라슈티컬 원료 산업의 성장에 영향을 미치는 주요 요인(촉진요인, 제약 요인, 과제, 기회 등)에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 참여 기업에 대한 철저한 분석을 통해 해당 기업의 사업, 서비스, 주요 전략, 계약, 파트너십, 합의 사항, 제품 출시, 합병 및 인수, 그리고 뉴트라슈티컬 원료 시장과 관련된 최근 동향에 대한 인사이트를 제공합니다. 이 보고서에서는 뉴트라슈티컬 원료 시장의 생태계에서 두각을 보이고 있는 스타트업 기업의 경쟁 분석도 수록하고 있습니다. 또한 본 조사에서는 기술 분석, 생태계 및 시장 매핑, 특허·규제 현황 등 업계 특유의 동향에 대해서도 포괄적으로 다루고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 시장 선도 기업 및 신규 진입 기업에게 뉴트라슈티컬 원료 시장 전체 및 그 하위 부문의 매출에 대한 가장 정확한 추정치를 제공합니다. 이를 통해 이해관계자는 경쟁 구도를 이해하고, 자사의 비즈니스를 더 유리한 위치에 놓으며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻을 수 있습니다. 또한 이 보고서는 이해관계자가 시장 동향을 파악하는 데 도움을 주며, 주요 시장 촉진요인, 제약 사항, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인(영양 보충제 및 타깃형 건강 제품의 보급 확대, 영양 강화 및 기능성이 향상된 식품 및 음료에 대한 수요 증가),제약 요인(영양 강화 및 기능성 배합에 따른 비용 상승, 엄격한 규제 요건 및 건강 표시 제한), 기회(미량영양소 결핍이 광범위하게 퍼져 있음, 영양 강화 및 보충제 섭취의 지속적인 이용, 예방 및 건강한 노화를 위한 영양에 대한 수요 증가),그리고 과제(뉴트라슈티컬 성분의 생체 이용률과 안정성을 높이는 전달 기술의 발전, 식물 유래 및 천연 성분의 편차와 품질관리상 과제)
- 제품 개발/혁신: 뉴트라슈티컬 원료 시장에서의 연구개발 활동 및 신제품 출시에 대한 상세한 분석
- 시장 개발: 다양한 지역의 영양 기능성 성분에 대한 분석을 제공함으로써, 수익성이 높은 시장에 대한 포괄적인 정보를 제공합니다
- 시장 다각화: 뉴트라슈티컬 원료 시장의 제품 조달처, 지역, 최근 동향 및 투자에 관한 포괄적인 정보
- 경쟁 분석: Cargill, Incorporated(미국), ADM(미국), International Flavors & Fragrances Inc.(미국), BASF SE(독일),Glanbia PLC(아일랜드), Arla Foods amba(덴마크), dsm-firmenich(네덜란드), Ingredion Incorporated(미국), Tate & Lyle PLC(영국), Roquette Freres(프랑스), Associated British Foods PLC(영국),Fonterra Co-operative Group Limited(뉴질랜드), Kerry Group PLC(아일랜드), Novonesis Group(덴마크), Balchem Corporation(미국)을 비롯한, 뉴트라슈티컬 원료 시장의 기타 주요 기업
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 규제와 지속가능성의 현황
제7장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제8장 고객 상황과 구매 행동
제9장 뉴트라슈티컬 원료 시장(기능별)
제10장 뉴트라슈티컬 원료 시장(성분 유형별)
제11장 뉴트라슈티컬 원료 시장(유래별)
제12장 뉴트라슈티컬 원료 시장(용도별)
제13장 뉴트라슈티컬 원료 시장(지역별)
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 인접 시장 및 관련 시장
제18장 부록
KSA 26.09.17The nutraceutical ingredients market is projected to grow from USD 108.33 billion in 2026 to USD 161.53 billion in 2031, at a CAGR of 7.3%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion), Volume (Tons) |
| Segments | By Ingredient Type, Application, Source, Function, and Region |
| Regions covered | North America, Asia Pacific, Europe, South America, RoW |
"Expanding use of amino acids in sports and specialized nutrition is expected to drive market growth"
Amino acids are increasingly incorporated into sports nutrition, dietary supplements, and specialized nutrition products, particularly formulations designed to support muscle recovery, physical performance, and protein intake. Branched-chain amino acids, essential amino acids, non-essential amino acids, and specialty amino acids are used across a range of formulations, with branched-chain amino acids particularly common in sports nutrition products targeting exercise performance and recovery. Their availability in standardized and high-purity forms enables manufacturers to develop products in powders, capsules, tablets, and functional beverages. In addition, advances in fermentation-based production are improving the efficiency, consistency, and scalability of amino acid manufacturing, supporting the availability of ingredients for different formulation requirements. The continued development of sports nutrition, active-aging, and specialized nutrition products is further broadening the use of amino acids across nutraceutical applications.
"Established nutritional and functional benefits of animal-based nutraceutical ingredients to support market growth."
By source, the animal-based segment accounts for a significant share of the nutraceutical ingredients market, supported by the high nutritional value, bioavailability, and established functional benefits of animal-derived ingredients. Animal-based sources provide a range of high-value nutrients and bioactive compounds used in products targeting joint, bone, muscle, cardiovascular, skin, and cognitive health. Their established use in sports nutrition is further supporting demand, particularly for protein-based products such as protein powders, meal replacements, and recovery beverages. Animal-derived ingredients also have an important role in infant and early-life nutrition, where dairy proteins and specialized components are used in formulations designed to support growth and development. In addition, their use in medical and specialized nutrition is supported by their nutritional quality and established scientific evidence, particularly in products addressing malnutrition, muscle loss, recovery, and age-related nutritional needs. These established applications across sports, infant, medical, and healthy-aging nutrition continue to sustain demand for animal-based nutraceutical ingredients.
"North America is expected to account for a significant share of the nutraceutical ingredients market due to strong consumer demand and an established nutraceutical industry."
North America is expected to account for a significant share of the nutraceutical ingredients market, supported by strong consumption of dietary supplements, high consumer awareness of preventive healthcare, and growing demand for functional nutrition products. The region has a well-established market for dietary supplements used across immunity, heart health, digestive wellness, sports nutrition, and healthy aging applications. High disposable incomes and healthcare spending support consumer willingness to spend on premium wellness, nutrition, and health products. In addition, the established functional food and beverage market, including protein-fortified foods, probiotic products, functional dairy products, energy and sports drinks, and fortified beverages, creates consistent demand for nutraceutical ingredients. The growing aging population is further increasing demand for products supporting joint, bone, cognitive, cardiovascular, and healthy aging needs, while the strong sports and active nutrition industry supports the use of protein ingredients, amino acids, and functional nutrition ingredients.
In-depth interviews were conducted with chief executive officers (CEOs), directors, and managers from various key organizations operating in the nutraceutical ingredients market.
- By Company Type: Tier 1 - 25%, Tier 2 - 45%, and Tier 3 - 30%
- By Designation: Directors- 35%, C-level - 40%, Others - 25%
- By Region: North America - 20%, Europe - 25%, Asia Pacific - 35%, South America - 15%, and Rest of the World -5%
Prominent companies in the nutraceutical ingredients market include Cargill, Incorporated (US), ADM (US), International Flavors & Fragrances Inc. (US), BASF SE (Germany), Glanbia PLC (Ireland), Arla Foods amba (Denmark), dsm-firmenich (Netherlands), Ingredion Incorporated (US), Tate & Lyle PLC (UK), Roquette Freres (France), Associated British Foods PLC (UK), Fonterra Co-operative Group Limited (New Zealand), Kerry Group PLC (Ireland), Novonesis Group (Denmark), Balchem Corporation (US), Ajinomoto Co., Inc. (Japan), Divi's Laboratories Limited (India), Kemin Industries (US), GELITA AG (Germany), BENEO GmbH (Germany), Cosucra Groupe Warcoing SA (Belgium), Conagen Inc. (US), Sarshika Pharmachem LLP (India), Canurta Naturals USA (US), and EVANIUM (US).
Research Coverage
This research report categorizes the nutraceutical ingredients market, by ingredient type (functional proteins, omega-3 fatty acids, probiotics, prebiotics, fibers & specialty carbohydrates, vitamins [vitamin A, vitamin B, vitamin C, vitamin D, vitamin E, and others], minerals [calcium, magnesium, iron, zinc, other minerals], amino acids [branched-chain amino acids, essential amino acids, non-essential amino acids, specialty amino acids], carotenoids, other types), source (plant-based, animal-based, microbial-based, synthetics), function (nutritional support, digestive health, immune health, cardiovascular health, bone & joint health, cognitive & mental health, sports & performance, weight management, others), and application (human nutrition [dietary supplements, functional foods, functional beverages, medical & specialized nutrition, infant & early-life nutrition], animal nutrition [companion animal nutrition, livestock nutrition, aquaculture nutrition, other animal nutrition]), and region (North America, Europe, Asia Pacific, South America, RoW).
The report's scope encompasses detailed information on the major factors, including drivers, restraints, challenges, and opportunities, which influence the growth of the nutraceutical ingredients industry. A thorough analysis of the key industry players was done to provide insights into their business, services, key strategies, contracts, partnerships, agreements, product launches, mergers & acquisitions, and recent developments associated with the nutraceutical ingredients market. This report provides a competitive analysis of emerging startups in the nutraceutical ingredients market ecosystem. Furthermore, the study covers industry-specific trends, including technology analysis, ecosystem & market mapping, and patent & regulatory landscape, among others.
Reasons to Buy This Report
The report provides market leaders/new entrants with information on the closest approximations of revenue numbers for the overall nutraceutical ingredients and their subsegments. It will help stakeholders understand the competitive landscape and gain more insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of key drivers (increasing adoption of dietary supplements and targeted health products, Growing demand for fortified and functionally enhanced foods and beverages), restraints (higher costs associated with fortification and functional formulation, stringent regulatory requirements and health-claim restrictions), opportunities (widespread micronutrient deficiencies and continued use of fortification and supplementation, growing demand for preventive and healthy aging nutrition), and challenges (advancements in delivery technologies enhancing bioavailability and stability of nutraceutical ingredients, variability and quality-control challenges for botanical and natural ingredients)
- Product Development/Innovation: Detailed insights into research & development activities and new product launches in the nutraceutical ingredients market
- Market Development: Comprehensive information about lucrative markets, by offering analysis of nutraceutical ingredients across varied regions
- Market Diversification: Exhaustive information about product sources, geographies, recent developments, and investments in the nutraceutical ingredients market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, brand/product comparison, and product footprints of leading players such as Cargill, Incorporated (US), ADM (US), International Flavors & Fragrances Inc. (US), BASF SE (Germany), Glanbia PLC (Ireland), Arla Foods amba (Denmark), dsm-firmenich (Netherlands), Ingredion Incorporated (US), Tate & Lyle PLC (UK), Roquette Freres (France), Associated British Foods PLC (UK), Fonterra Co-operative Group Limited (New Zealand), Kerry Group PLC (Ireland), Novonesis Group (Denmark), Balchem Corporation (US) and other players in the nutraceutical ingredients market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 INCLUSIONS AND EXCLUSIONS
- 1.3.2 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN NUTRACEUTICAL INGREDIENTS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN NUTRACEUTICAL INGREDIENTS MARKET
- 3.2 NUTRACEUTICAL INGREDIENTS MARKET, BY INGREDIENT TYPE AND REGION
- 3.3 NUTRACEUTICAL INGREDIENTS MARKET, BY SOURCE
- 3.4 NUTRACEUTICAL INGREDIENTS MARKET, BY INGREDIENT TYPE
- 3.5 NUTRACEUTICAL INGREDIENTS MARKET, BY APPLICATION
- 3.6 NUTRACEUTICAL INGREDIENTS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing adoption of dietary supplements and targeted health products
- 4.2.1.2 Growing demand for fortified and functionally enhanced foods and beverages
- 4.2.1.3 Rising incidence of chronic diseases
- 4.2.2 RESTRAINTS
- 4.2.2.1 High Cost and price volatility of nutraceutical ingredients
- 4.2.2.2 Stringent regulatory requirements and health-claim restrictions
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Widespread micronutrient deficiencies and continued use of fortification and supplementation
- 4.2.3.2 Growing demand for preventive and healthy aging nutrition
- 4.2.3.3 Advancements in delivery technologies enhancing bioavailability and stability of nutraceutical ingredients
- 4.2.4 CHALLENGES
- 4.2.4.1 Variability and quality-control challenges for botanical and natural ingredients
- 4.2.4.2 Supply chain disruptions and availability of nutraceutical raw materials
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN NUTRACEUTICAL INGREDIENTS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC INDICATORS
- 5.3.1 GLOBAL HEALTHCARE EXPENDITURE
- 5.3.2 REAL HOUSEHOLD INCOME
- 5.4 VALUE CHAIN ANALYSIS
- 5.4.1 RAW MATERIAL SOURCING
- 5.4.2 EXTRACTION & PROCESSING
- 5.4.3 INGREDIENT MANUFACTURING & STANDARDIZATION
- 5.4.4 QUALITY ASSURANCE, R&D & REGULATORY
- 5.4.5 COMMERCIALIZATION & DISTRIBUTION
- 5.4.6 INGREDIENT APPLICATION
- 5.5 ECOSYSTEM ANALYSIS
- 5.5.1 DEMAND SIDE
- 5.5.2 SUPPLY SIDE
- 5.6 PRICING ANALYSIS
- 5.6.1 INDICATIVE PRICE TREND AMONG MARKET PLAYERS
- 5.6.2 AVERAGE SELLING PRICE TREND, BY INGREDIENT TYPE
- 5.6.3 AVERAGE SELLING PRICE TREND, BY REGION
- 5.7 TRADE ANALYSIS
- 5.7.1 TRADE ANALYSIS OF HS CODE 2936: PROVITAMINS AND VITAMINS
- 5.7.1.1 Export Trends of HS Code 2936 (2021-2025)
- 5.7.1.2 Import Trends under HS Code 2936 (2021-2025)
- 5.7.1 TRADE ANALYSIS OF HS CODE 2936: PROVITAMINS AND VITAMINS
- 5.8 KEY CONFERENCES & EVENTS
- 5.9 TRENDS IMPACTING CUSTOMERS' BUSINESSES
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 DSM-FIRMENICH SUPPORTED KOREA EUNDAN'S TRANSITION TO ALGAL OMEGA-3
- 5.11.2 KERRY - BC30 PROBIOTIC IN FUNCTIONAL HOT BEVERAGE
- 5.11.3 INGREDION - VITESSENCE PULSE 1853 PEA PROTEIN IN VEGAN BEVERAGE
- 5.12 IMPACT OF US TARIFF - NUTRACEUTICAL INGREDIENTS MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 PRICE IMPACT ANALYSIS
- 5.12.3 IMPACT ON COUNTRY/REGION
- 5.12.3.1 US
- 5.12.3.2 Europe
- 5.12.3.3 Asia Pacific
- 5.12.4 IMPACT ON END-USE INDUSTRIES
6 REGULATORY AND SUSTAINABILITY LANDSCAPE
- 6.1 INTRODUCTION
- 6.2 REGIONAL REGULATIONS AND COMPLIANCE
- 6.2.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 6.2.2 INDUSTRY STANDARDS
- 6.3 SUSTAINABILITY INITIATIVES
- 6.3.1 SUSTAINABLE AND RESPONSIBLE SOURCING
- 6.3.2 RESOURCE EFFICIENCY AND LOW-CARBON MANUFACTURING
- 6.3.3 CIRCULAR ECONOMY AND SUSTAINABLE PRODUCTION
- 6.3.4 CIRCULAR ECONOMY AND FOOD WASTE REDUCTION
- 6.4 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 6.5 CERTIFICATIONS, LABELING, ECO-STANDARDS
7 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 7.1 INTRODUCTION
- 7.2 KEY TECHNOLOGIES
- 7.2.1 ADVANCED EXTRACTION & PURIFICATION TECHNOLOGIES
- 7.2.2 PRECISION FERMENTATION & ADVANCED BIOPROCESSING
- 7.2.3 ENCAPSULATION & ADVANCED DELIVERY SYSTEMS
- 7.3 COMPLEMENTARY TECHNOLOGIES
- 7.3.1 ADVANCED ANALYTICAL & CHARACTERIZATION TECHNOLOGIES
- 7.3.2 NANOTECHNOLOGY & ADVANCED FORMULATION TECHNOLOGIES
- 7.3.3 AUTOMATION, PROCESS MONITORING & DIGITAL MANUFACTURING TECHNOLOGIES
- 7.4 ADJACENT TECHNOLOGIES
- 7.4.1 SYNTHETIC BIOLOGY & BIOINFORMATICS
- 7.4.2 PERSONALIZED NUTRITION & DIGITAL HEALTH TECHNOLOGIES
- 7.4.3 ADVANCED FOOD PROCESSING & 3D FOOD-PRINTING TECHNOLOGIES
- 7.5 TECHNOLOGY/PRODUCT ROADMAP
- 7.5.1 SHORT-TERM | OPTIMIZATION OF EXTRUSION PROCESSES AND CLEAN-LABEL PRODUCT DEVELOPMENT
- 7.5.2 MID-TERM | INTELLIGENT MANUFACTURING AND COMMERCIALIZATION OF NEXT-GENERATION PROTEIN INGREDIENTS
- 7.5.3 LONG-TERM | AUTONOMOUS AI-DRIVEN MANUFACTURING AND SUSTAINABLE PROTEIN INNOVATION
- 7.6 PATENT ANALYSIS
- 7.6.1 LIST OF MAJOR PATENTS
- 7.7 FUTURE APPLICATIONS
- 7.7.1 PERSONALIZED & PRECISION NUTRITION
- 7.7.2 FUNCTIONAL & SPECIALIZED NUTRITION PRODUCTS
- 7.8 IMPACT OF GENERATIVE AI ON NUTRACEUTICAL INGREDIENTS MARKET
- 7.8.1 INTRODUCTION
- 7.8.2 TOP USE CASES AND MARKET POTENTIAL
- 7.8.3 BEST PRACTICES IN NUTRACEUTICAL INGREDIENTS INDUSTRY
- 7.8.4 CASE STUDIES OF AI IMPLEMENTATION IN NUTRACEUTICAL INGREDIENTS MARKET
- 7.8.5 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 7.8.6 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN NUTRACEUTICAL INGREDIENTS MARKET
- 7.9 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.5 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
- 8.6 MARKET PROFITABILITY
9 NUTRACEUTICAL INGREDIENTS MARKET, BY FUNCTION
- 9.1 INTRODUCTION
- 9.2 NUTRITIONAL SUPPORT
- 9.3 DIGESTIVE HEALTH
- 9.4 IMMUNE HEALTH
- 9.5 CARDIOVASCULAR HEALTH
- 9.6 BONE & JOINT HEALTH
- 9.7 COGNITIVE & MENTAL HEALTH
- 9.8 SPORTS & PERFORMANCE
- 9.9 WEIGHT MANAGEMENT
- 9.10 OTHERS (BEAUTY & HEALTHY AGING, ETC.)
10 NUTRACEUTICAL INGREDIENTS MARKET, BY INGREDIENT TYPE
- 10.1 INTRODUCTION
- 10.2 FUNCTIONAL PROTEINS
- 10.2.1 NUTRITIONAL FUNCTIONALITY AND EXPANDING APPLICATIONS
- 10.3 OMEGA-3 FATTY ACIDS
- 10.3.1 GROWING DEMAND FOR CARDIOVASCULAR, COGNITIVE, AND PREVENTIVE NUTRITION
- 10.4 PROBIOTICS
- 10.4.1 EXPANDING APPLICATIONS IN GUT HEALTH AND FUNCTIONAL NUTRITION
- 10.5 PREBIOTICS
- 10.5.1 SUPPORTING GUT MICROBIOME HEALTH AND FUNCTIONAL NUTRITION
- 10.6 FIBERS & SPECIALTY CARBOHYDRATES
- 10.6.1 EXPANDING ROLE IN DIGESTIVE HEALTH AND PRODUCT FORMULATION
- 10.7 VITAMINS
- 10.7.1 ESSENTIAL MICRONUTRIENTS SUPPORTING PREVENTIVE AND SPECIALIZED NUTRITION
- 10.7.2 VITAMIN A
- 10.7.3 VITAMIN B
- 10.7.4 VITAMIN C
- 10.7.5 VITAMIN D
- 10.7.6 VITAMIN E
- 10.7.7 OTHER VITAMINS (MULTIVITAMIN, ETC.)
- 10.8 MINERALS
- 10.8.1 ESSENTIAL MICRONUTRIENTS ACROSS SUPPLEMENTATION, FORTIFICATION, AND SPECIALIZED NUTRITION
- 10.8.2 CALCIUM
- 10.8.3 MAGNESIUM
- 10.8.4 IRON
- 10.8.5 ZINC
- 10.8.6 OTHER MINERALS
- 10.9 AMINO ACIDS
- 10.9.1 EXPANDING ROLE IN TARGETED NUTRITION, SPORTS PERFORMANCE, AND METABOLIC SUPPORT
- 10.9.2 BRANCHED-CHAIN AMINO ACIDS
- 10.9.3 ESSENTIAL AMINO ACIDS
- 10.9.4 NON-ESSENTIAL AMINO ACIDS
- 10.9.5 SPECIALTY AMINO ACIDS
- 10.10 CAROTENOIDS
- 10.10.1 NATURAL PIGMENTS WITH EXPANDING NUTRITIONAL AND FUNCTIONAL APPLICATIONS
- 10.11 OTHER INGREDIENT TYPES
11 NUTRACEUTICAL INGREDIENTS MARKET, BY SOURCE
- 11.1 INTRODUCTION
- 11.2 PLANT-BASED
- 11.2.1 EXPANSION OF PLANT-BASED SUPPLY AND PROCESSING CAPACITY TO DRIVE NUTRACEUTICAL INGREDIENT MARKET GROWTH
- 11.3 ANIMAL-BASED
- 11.3.1 GROWING DEMAND FOR HIGH-PROTEIN AND BIOACTIVE INGREDIENTS TO DRIVE ANIMAL-BASED INGREDIENT GROWTH
- 11.4 MICROBIAL-BASED
- 11.4.1 EXPANSION OF MICROBIAL-DERIVED INGREDIENTS AND FERMENTATION-BASED PRODUCTION TO DRIVE MARKET GROWTH
- 11.5 SYNTHETICS
- 11.5.1 CONSISTENT QUALITY AND SCALABLE PRODUCTION OF SYNTHETIC INGREDIENTS TO SUPPORT MARKET GROWTH
12 NUTRACEUTICAL INGREDIENTS MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 HUMAN NUTRITION
- 12.2.1 DIETARY SUPPLEMENTS
- 12.2.1.1 Dietary supplements remain largest application for nutraceutical ingredients due to their established consumer acceptance
- 12.2.2 FUNCTIONAL FOODS
- 12.2.2.1 Growing health-conscious consumption is driving nutraceutical ingredient adoption in functional foods
- 12.2.3 FUNCTIONAL BEVERAGES
- 12.2.3.1 Demand for convenient wellness products is accelerating nutraceutical ingredient use in beverages
- 12.2.4 MEDICAL & SPECIALIZED NUTRITION
- 12.2.4.1 Rising demand for targeted nutrition is supporting use of specialty nutraceutical ingredients
- 12.2.5 INFANT & EARLY-LIFE NUTRITION
- 12.2.5.1 Greater focus on early-life health is driving demand for high-quality nutraceutical ingredients
- 12.2.1 DIETARY SUPPLEMENTS
- 12.3 ANIMAL NUTRITION
- 12.3.1 COMPANION ANIMAL NUTRITION
- 12.3.1.1 Pet humanization is accelerating demand for nutraceutical ingredients in companion animal nutrition
- 12.3.2 LIVESTOCK NUTRITION
- 12.3.2.1 Reduced reliance on antibiotics is driving nutraceutical adoption in livestock nutrition
- 12.3.3 AQUACULTURE NUTRITION
- 12.3.3.1 Growing aquaculture production is increasing demand for functional nutrition ingredients
- 12.3.4 OTHER ANIMAL NUTRITION
- 12.3.4.1 Specialized animal health needs are creating demand for targeted nutraceutical ingredients
- 12.3.1 COMPANION ANIMAL NUTRITION
13 NUTRACEUTICAL INGREDIENTS MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Strong supplement penetration and rising demand for functional nutrition
- 13.2.2 CANADA
- 13.2.2.1 Growing demand for natural products supports market expansion
- 13.2.3 MEXICO
- 13.2.3.1 Expanding preventive nutrition demand and broadening supplement ecosystem
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 GERMANY
- 13.3.1.1 High food supplement penetration and demand for micronutrients support market growth
- 13.3.2 UK
- 13.3.2.1 Established food supplement use and regulatory support for innovative ingredients support market growth
- 13.3.3 FRANCE
- 13.3.3.1 Established supplement market and growing demand for targeted nutrition support market growth
- 13.3.4 ITALY
- 13.3.4.1 Large supplement product base and broad use of nutritional ingredients support market growth
- 13.3.5 SPAIN
- 13.3.5.1 Established supplement regulation and broad nutritional ingredient applications support market growth
- 13.3.6 REST OF EUROPE
- 13.3.6.1 Expanding food supplement use and regulatory harmonization support market opportunities
- 13.3.1 GERMANY
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Expanding health food formulation and diversification of nutritional products support market growth
- 13.4.2 INDIA
- 13.4.2.1 Large agricultural base and expanding nutraceutical ecosystem support market growth
- 13.4.3 JAPAN
- 13.4.3.1 Rapid population aging and preventive healthcare culture drive demand for functional ingredients
- 13.4.4 AUSTRALIA & NEW ZEALAND
- 13.4.4.1 Strong supplement adoption and export-oriented health product ecosystem support nutraceutical ingredient demand
- 13.4.5 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.5.1.1 Strong supplement penetration and rapid expansion of protein and vitamin ingredients
- 13.5.2 ARGENTINA
- 13.5.2.1 Growing demand for targeted nutrition and specialty nutraceutical ingredients
- 13.5.3 REST OF SOUTH AMERICA
- 13.5.3.1 Emerging consumer awareness and diversification of functional nutrition
- 13.5.1 BRAZIL
- 13.6 REST OF THE WORLD (ROW)
- 13.6.1 MIDDLE EAST
- 13.6.1.1 Rising nutrition-related health needs and preventive healthcare focus
- 13.6.2 AFRICA
- 13.6.2.1 Nutritional needs and food fortification programs create structural ingredient demand
- 13.6.1 MIDDLE EAST
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021-2026
- 14.3 BRAND/PRODUCT COMPARISON
- 14.3.1 CARGILL, INCORPORATED (EPICOR)
- 14.3.2 ADM (FIBERSOL)
- 14.3.3 GLANBIA PLC (FERRIUP)
- 14.3.4 DSM-FIRMENICH (PEPTOPRO)
- 14.3.5 ROQUETTE FRERES (NUTRALYS)
- 14.4 REVENUE ANALYSIS, 2023-2025
- 14.5 COMPANY VALUATION AND FINANCIAL METRICS
- 14.5.1 COMPANY VALUATION
- 14.5.2 EV/EBITDA
- 14.6 MARKET SHARE ANALYSIS, 2025
- 14.7 NUTRACEUTICAL INGREDIENTS MARKET COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.7.5.1 Company footprint
- 14.7.5.2 Region footprint
- 14.7.5.3 Ingredient type footprint
- 14.7.5.4 Source footprint
- 14.7.5.5 Application footprint
- 14.8 COMPANY EVALUATION MATRIX: START-UPS/SMES, 2025
- 14.8.1 PROGRESSIVE COMPANIES
- 14.8.2 RESPONSIVE COMPANIES
- 14.8.3 DYNAMIC COMPANIES
- 14.8.4 STARTING BLOCKS
- 14.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.8.5.1 Key startups/SMEs
- 14.8.5.2 Competitive benchmarking of key startups/SMEs
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 EXPANSIONS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 CARGILL, INCORPORATED
- 15.1.1.1 Business overview
- 15.1.1.2 Products offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.3.2 Deals
- 15.1.1.3.3 Expansions
- 15.1.1.3.4 Other developments
- 15.1.1.4 MnM view
- 15.1.1.4.1 Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 ADM
- 15.1.2.1 Business overview
- 15.1.2.2 Products offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches
- 15.1.2.3.2 Deals
- 15.1.2.3.3 Expansions
- 15.1.2.3.4 Other developments
- 15.1.2.4 MnM view
- 15.1.2.4.1 Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 INTERNATIONAL FLAVORS & FRAGRANCES INC.
- 15.1.3.1 Business overview
- 15.1.3.2 Products offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Product launches
- 15.1.3.3.2 Deals
- 15.1.3.3.3 Expansions
- 15.1.3.3.4 Other developments
- 15.1.3.4 MnM view
- 15.1.3.4.1 Right to win
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 BASF
- 15.1.4.1 Business overview
- 15.1.4.2 Products offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches
- 15.1.4.3.2 Deals
- 15.1.4.3.3 Expansions
- 15.1.4.3.4 Other developments
- 15.1.4.4 MnM view
- 15.1.4.4.1 Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 GLANBIA PLC
- 15.1.5.1 Business overview
- 15.1.5.2 Products offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches
- 15.1.5.3.2 Deals
- 15.1.5.3.3 Expansions
- 15.1.5.3.4 Other developments
- 15.1.5.4 MnM view
- 15.1.5.4.1 Right to win
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 ARLA FOODS AMBA
- 15.1.6.1 Business overview
- 15.1.6.2 Products offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Product launches
- 15.1.6.3.2 Deals
- 15.1.6.3.3 Expansions
- 15.1.6.3.4 Other developments
- 15.1.6.4 MnM view
- 15.1.7 DSM-FIRMENICH
- 15.1.7.1 Business overview
- 15.1.7.2 Products offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches
- 15.1.7.3.2 Deals
- 15.1.7.3.3 Expansions
- 15.1.7.3.4 Other developments
- 15.1.7.4 MnM view
- 15.1.8 INGREDION
- 15.1.8.1 Business overview
- 15.1.8.2 Products offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product launches
- 15.1.8.3.2 Deals
- 15.1.8.3.3 Expansions
- 15.1.8.3.4 Other developments
- 15.1.8.4 MnM view
- 15.1.9 TATE & LYLE
- 15.1.9.1 Business overview
- 15.1.9.2 Recent developments
- 15.1.9.2.1 Product launches
- 15.1.9.2.2 Deals
- 15.1.9.2.3 Expansions
- 15.1.9.2.4 Other developments
- 15.1.9.3 MnM view
- 15.1.10 ROQUETTE FRERES
- 15.1.10.1 Business overview
- 15.1.10.2 Products offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Product launches
- 15.1.10.3.2 Deals
- 15.1.10.3.3 Expansions
- 15.1.10.3.4 Other developments
- 15.1.10.4 MnM view
- 15.1.11 ASSOCIATED BRITISH FOODS PLC
- 15.1.11.1 Business overview
- 15.1.11.2 Products offered
- 15.1.11.3 Recent developments
- 15.1.11.3.1 Product launches
- 15.1.11.3.2 Deals
- 15.1.11.3.3 Expansions
- 15.1.11.3.4 Other developments
- 15.1.11.4 MnM view
- 15.1.12 FONTERRA CO-OPERATIVE GROUP LIMITED
- 15.1.12.1 Business overview
- 15.1.12.2 Products offered
- 15.1.12.3 Recent developments
- 15.1.12.3.1 Product launches
- 15.1.12.3.2 Deals
- 15.1.12.3.3 Expansions
- 15.1.12.3.4 Other developments
- 15.1.12.4 MnM view
- 15.1.13 KERRY GROUP PLC
- 15.1.13.1 Business overview
- 15.1.13.2 Products offered
- 15.1.13.3 Recent developments
- 15.1.13.3.1 Product launches
- 15.1.13.3.2 Deals
- 15.1.13.3.3 Expansions
- 15.1.13.3.4 Other developments
- 15.1.13.4 MnM view
- 15.1.14 NOVONESIS GROUP
- 15.1.14.1 Business overview
- 15.1.14.2 Products offered
- 15.1.14.3 Recent developments
- 15.1.14.3.1 Product launches
- 15.1.14.3.2 Deals
- 15.1.14.3.3 Expansions
- 15.1.14.3.4 Other developments
- 15.1.14.4 MnM view
- 15.1.15 BALCHEM CORP.
- 15.1.15.1 Business overview
- 15.1.15.2 Products offered
- 15.1.15.3 Recent developments
- 15.1.15.3.1 Product launches
- 15.1.15.3.2 Deals
- 15.1.15.3.3 Expansions
- 15.1.15.3.4 Other developments
- 15.1.15.4 MnM view
- 15.1.1 CARGILL, INCORPORATED
- 15.2 OTHER PLAYERS
- 15.2.1 AJINOMOTO CO., INC.
- 15.2.1.1 Business overview
- 15.2.1.2 Products offered
- 15.2.1.3 Recent developments
- 15.2.1.3.1 Deals
- 15.2.1.3.2 Expansions
- 15.2.1.3.3 Other developments
- 15.2.1.4 MnM view
- 15.2.2 DIVI'S LABORATORIES LIMITED
- 15.2.2.1 Business overview
- 15.2.2.2 Products offered
- 15.2.2.3 Recent developments
- 15.2.2.3.1 Deals
- 15.2.2.3.2 Expansions
- 15.2.2.4 MnM view
- 15.2.3 KEMIN INDUSTRIES, INC.
- 15.2.3.1 Business overview
- 15.2.3.2 Products offered
- 15.2.3.3 Recent developments
- 15.2.3.3.1 Product launches
- 15.2.3.3.2 Deals
- 15.2.3.3.3 Other developments
- 15.2.3.4 MnM view
- 15.2.4 GELITA
- 15.2.4.1 Business overview
- 15.2.4.2 Products offered
- 15.2.4.3 Recent developments
- 15.2.4.3.1 Product launches
- 15.2.4.3.2 Deals
- 15.2.4.3.3 Expansions
- 15.2.4.3.4 Other developments
- 15.2.4.4 MnM view
- 15.2.5 BENEO
- 15.2.5.1 Business overview
- 15.2.5.2 Products offered
- 15.2.5.3 Recent developments
- 15.2.5.3.1 Product launches
- 15.2.5.3.2 Deals
- 15.2.5.3.3 Expansions
- 15.2.5.3.4 Other developments
- 15.2.5.4 MnM view
- 15.2.6 COSUCRA
- 15.2.7 CONAGEN, INC.
- 15.2.8 SARSHIKA PHARMACHEM LLP
- 15.2.9 CANURTA NATURALS USA
- 15.2.10 EVANIUM
- 15.2.1 AJINOMOTO CO., INC.
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 List of major secondary sources
- 16.1.1.2 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key data from primary sources
- 16.1.2.2 Key industry insights
- 16.1.2.3 Breakdown of primaries
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 BOTTOM-UP APPROACH
- 16.2.2 TOP-DOWN APPROACH
- 16.2.2.1 Approach to estimate market size using top-down analysis
- 16.2.3 SUPPLY-SIDE ANALYSIS
- 16.2.4 DEMAND-SIDE ANALYSIS
- 16.3 DATA TRIANGULATION
- 16.4 RESEARCH ASSUMPTIONS
- 16.5 RESEARCH LIMITATIONS AND RISK ASSESSMENT
17 ADJACENT & RELATED MARKETS
- 17.1 INTRODUCTION
- 17.2 LIMITATIONS
- 17.3 PROTEIN INGREDIENTS MARKET
- 17.3.1 MARKET DEFINITION
- 17.3.2 MARKET OVERVIEW
- 17.4 NUTRACEUTICAL GUMMIES MARKET
- 17.4.1 MARKET DEFINITION
- 17.4.2 MARKET OVERVIEW
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS