
|
시장보고서
상품코드
2130445
PTFE막 시장 : 유형별, 기술별, 형태별, 용도별, 지역별 예측(-2031년)PTFE Membranes Market by Type (Hydrophobic, Hydrophilic), Technology (RO, MF, NF, UF), Form (Spiral, Tubular, Plate and Frame, Hollow Fiber), Application (Industrial Filtration, Water & Wastewater Treatment), and Region - Global Forecast to 2031 |
||||||

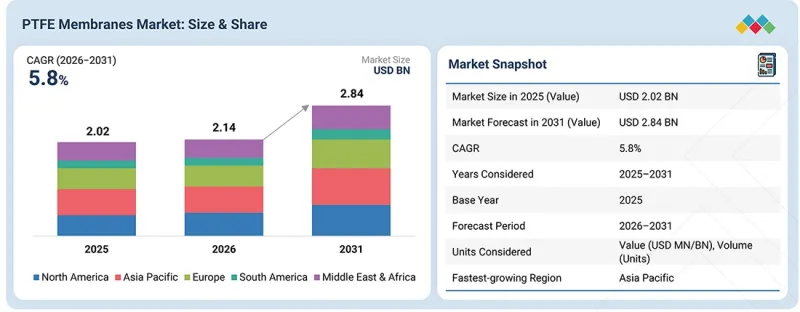
PTFE막 시장 규모는 2026년 21억 4,000만 달러에서 2031년까지 28억 4,000만 달러에 이를 것으로 예상되고 예측 기간 중 연평균 복합 성장률(CAGR)은 5.8%를 나타낼 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2025-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 대상 단위 | 금액(100만/10억 달러) 수량(개) |
| 부문 | 유형별, 기술별, 형태별, 용도별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 중동 및 아프리카, 남미 |
PTFE 막 시장은 제약, 생명공학, 반도체, 전자, 산업용, 헬스케어, 수처리 등 각 분야에서 신뢰성이 높고 효율적이며 내구성이 뛰어난 여과 장치에 대한 수요가 증가하고 있어 상당한 성장이 예상됩니다. 이 시장의 확대는 산업 및 인프라의 발전은 물론, 최첨단 제조 시설 및 수처리 시설에 대한 설비 투자 증가에 힘입어 주도되고 있습니다.
또한, 제약·생명공학 가공, 반도체 제조, 식품 및 음료 생산 및 화학 처리 분야에서 고순도 여과에 대한 수요 역시 PTFE 멤브레인 수요를 끌어올리고 있습니다. 의료시설, 산업 플랜트 및 중요한 처리 용도에 사용되는 여과 시스템은 안정적으로 가동되어야 하며 가혹한 조건을 견뎌내야 합니다. 게다가 오염 관리 및 공정 효율에 대한 요구가 높아짐에 따라 시장 성장이 더욱 가속화되고 있습니다.
다양한 산업 분야에서 첨단 여과 시스템이 점점 더 많이 도입됨에 따라, 전 세계 PTFE 막 소비량은 계속 증가하고 있습니다.
“예측 기간 동안 PTFE 막 시장에서 유형별로는 소수성 부문이 가장 큰 비중을 차지할 것으로 예측됩니다.”
PTFE 막 시장에서 소수성 막은 뛰어난 내화학성, 낮은 흡습성 및 높은 열안정성 덕분에 가장 큰 시장 점유율을 차지할 것으로 예측됩니다. 이러한 막은 물 및 가스 여과 모두에 널리 사용되고 있습니다. 제약 및 생명공학 공정,산업용 여과, 반도체 제조, 수처리 및 배기 처리 분야에서 폭넓게 활용되고 있습니다. 오염 관리, 무균 가스 여과 및 가혹한 작동 조건 하에서 신뢰할 수 있는 막 성능에 대한 수요가 증가하고 있으며, 이 모든 요소가 다양한 최종 용도 분야에서 소수성 PTFE 막 시장의 성장을 견인하는 주요 요인이 되고 있습니다.
“예측 기간 동안 PTFE 막 시장에서 미세 여과 부문이 가장 큰 기술 부문이 될 것으로 전망됩니다.”
예측 기간 동안, 미세 여과는 뛰어난 여과 성능, 쉬운 조작, 그리고 액체 및 기체에서 부유 물질, 세균, 기타 오염 물질을 동시에 제거할 수 있는 능력 덕분에 PTFE 막 기술 부문을 주도할 것으로 예측됩니다. 미세 여과는 제약 및 생명공학 분야에서 중요한 역할을 할 뿐만 아니라, 식품 및 음료 산업, 상하수도 처리, 전자 산업, 그리고 다양한 산업용 여과 공정에서도 필수적입니다. 고순도 여과, 오염 관리 및 공정 스트림의 효과적인 처리에 대한 수요가 증가함에 따라, 수많은 최종 이용 산업에서 미세 여과용 PTFE 막의 활용이 확대되고 있습니다.
“예측 기간 동안 PTFE 막 시장에서 형태별로는 나선형이 가장 큰 부문이 될 것으로 전망됩니다.”
예측 기간 동안, 형태 부문에서 나선형 구조가 PTFE 막 시장의 최대 점유율을 차지할 것으로 예측됩니다. 이는 컴팩트한 설계 속에서 높은 막 표면적을 확보하여 효율적인 여과와 효과적인 공간 활용을 가능하게 하는 능력 덕분입니다. 나선형 구조는 수처리, 제약, 생명공학 및 높은 처리 능력이 요구되는 기타 산업 분야의 여과 용도로 널리 사용되고 있습니다. 다양한 최종 이용 산업에서 컴팩트한 막 설계와 연속 처리를 갖춘 효율적인 여과 시스템에 대한 수요가 증가함에 따라, 나선형 PTFE 막 구조의 채택이 촉진될 것으로 예측됩니다.
“예측 기간 동안 식품 및 음료 분야는 PTFE 막 시장에서 가장 큰 응용 분야가 될 전망입니다.”
예측 기간 동안 식품 및 음료 응용 분야가 PTFE 막 수요에서 가장 큰 점유율을 차지할 것으로 전망됩니다. 이는 PTFE 막의 뛰어난 내화학성, 열 안정성 및 일관된 여과 성능 덕분입니다. 이러한 막은 식품 및 음료 가공 과정에서 액체 및 기체의 여과, 무균 처리, 정제, 그리고 오염 관리에 활용되고 있습니다. 제품의 순도 향상, 공정 효율 증대, 식품 안전, 그리고 위생적인 제조에 대한 수요가 증가함에 따라 식품 및 음료 업계에서 PTFE 막 솔루션의 활용이 확대될 것으로 예측됩니다.
“예측 기간 동안 아시아태평양은 PTFE 막 시장에서 가장 큰 규모를 차지할 것으로 전망됩니다.”
아시아태평양의 PTFE 막 시장은 2031년까지 매출이 크게 증가할 것으로 전망됩니다. 이러한 예상되는 성장은 주로 산업화, 생산 능력 확대, 의약품 및 생명공학 제품 생산, 그리고 여과 및 수처리 기술에 대한 투자 증가에 의해 주도되고 있습니다.
중국, 인도, 일본, 한국과 같은 주요 국가에서는 반도체 및 전자기기 제조, 의료시설, 화학 처리, 식품 및 음료 산업 등의 분야 확대를 배경으로 PTFE 막에 대한 수요가 증가세를 보이고 있습니다. PTFE 막은 고순도이며 신뢰성이 높은 여과가 필수적인 의약품, 상하수도 처리, 산업용도 등의 업계에서 없어서는 안 될 존재입니다. 또한, 초미세 필터로서의 유효성으로 인해 반도체 제조 공정 및 오염 관리 분야에서의 활용도 증가하고 있습니다.
게다가 이 지역에서는 의약품·화학제품, 반도체, 전자제품 생산에 대한 투자 확대는 물론, 산업 시설 건설, 상하수도 처리 개선, 의료시설 개보수 등이 시장에 긍정적인 영향을 미칠 것으로 예측됩니다. 고성능 운영을 위한 첨단 여과 기술에 대한 수요 증가는 아시아태평양의 PTFE 막 시장 확대를 견인하는 주요 요인이 되고 있습니다.
대상 기업 : Pall Corporation(미국), Cytiva(미국), W. L. Gore & Associates, Inc.(미국), Merck KGaA(미국), Corning Incorporated(미국), Donaldson Company, Inc.(미국),Saint-Gobain(프랑스), Sartorius AG(독일), HYUNDAI MICRO(한국), Sumitomo Electric Industries, Ltd.(일본)가 본 보고서의 대상 기업입니다.
본 조사에서는 PTFE 막 시장의 주요 기업들에 대해 기업 프로파일, 최근 동향 및 주요 시장 전략을 포함한 상세한 경쟁 분석을 수행하고 있습니다.
조사 범위
본 조사 보고서에서는 PTFE 막 시장을 유형(소수성, 친수성), 기술(역삼투, 나노 여과, 한외 여과, 미세 여과), 형태(나선형, 튜브형, 플레이트 및 프레임형, 중공사형),및 용도(전자기기용 여과, 의료 및 제약, 식품 및 음료, 상하수도 처리, 화학 처리, 석유 및 가스, 기타 용도)에 따라 분류하고 있습니다. 본 보고서의 조사 범위에는 PTFE 막 시장의 성장에 영향을 미치는 촉진요인, 제약 요인, 과제 및 기회에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 참여 기업에 대한 상세한 분석을 통해 각 기업의 사업 개요, 제공 제품, 그리고 PTFE 멤브레인 시장과 관련된 합병·인수, 제품 출시, 제휴, 사업 확장 등의 주요 전략에 대한 인사이트를 제공합니다. 또한, 본 보고서에서는 PTFE 막 시장 생태계에서 두각을 나타내고 있는 신생 기업에 대한 경쟁 분석도 다루고 있습니다.
이 보고서를 구매해야 하는 이유
본 보고서는 시장 선도 기업 및 신규 진출기업에게 PTFE 막 시장 전체 및 그 하위 부문의 매출액에 대한 가장 정확한 추정치를 제공합니다. 본 보고서는 이해관계자가 경쟁 구도를 이해하고, 자사의 비즈니스를 더 유리한 위치에 놓을 수 있는 심층적인 인사이트를 얻어 적절한 시장 진출 전략을 수립하는 데 도움이 됩니다. 또한, 시장 동향을 파악하고 주요 시장 성장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다.
- 주요 성장 촉진요인(산업용 여과에 대한 수요 증가, 배출 및 오염을 억제하기 위한 엄격한 환경 규제 도입, 의료 및 제약 업계에서 PTFE 막에 대한 수요 증가) 및 제약 요인(높은 생산 비용, 폴리플루오로비닐리덴(PVDF),폴리에테르설폰(PES), 세라믹 막에 대한 선호)에 대한 분석, 기회(미세 여과 및 벤트 용도, 의료용 액세서리에서의 ePTFE 막 활용 확대, 개발도상국에서의 처리수 수요 증가), 그리고 과제(원자재 가격 변동)에 관한 분석.
- 제품 개발 및 혁신 : PTFE 막 시장의 향후 기술, 연구 개발 활동, 그리고 제품 및 서비스 출시에 관한 상세한 인사이트.
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보. 본 보고서에서는 다양한 지역의 PTFE 막 시장을 분석합니다.
- 시장 다각화 : PTFE 막 시장의 신제품 및 서비스, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보를 제공합니다.
- 경쟁 분석 : Pall Corporation(미국), Cytiva(미국), W. L. Gore & Associates, Inc.(미국), Merck KGaA(미국), Corning Incorporated(미국), Donaldson Company, Inc.(미국),Saint-Gobain(프랑스), Sartorius AG(독일), HYUNDAI MICRO(한국), Sumitomo Electric Industries, Ltd.(일본) 등 주요 기업의 시장 점유율, 성장 전략, 서비스 제공 내용에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 주요 요약
제3장 프리미엄 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 이니셔티브
제8장 고객 현황과 구매 행동
제9장 PTFE막 시장(유형별)
제10장 PTFE막 시장(기술별)
제11장 PTFE막 시장(형태별)
제12장 PTFE막 시장(용도별)
제13장 PTFE막 시장(지역별)
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 부록
KTH 26.09.28The PTFE membranes market is expected to reach USD 2.84 billion by 2031 from USD 2.14 billion in 2026, at a CAGR of 5.8% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2025-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) Volume (Unit) |
| Segments | Type, Technology, Form, Application, and Region |
| Regions covered | North America, Asia Pacific, Europe, Middle East & Africa, and South America |
The PTFE membranes market is projected to grow significantly due to increasing demand for reliable, efficient, and durable filtration equipment across sectors including pharmaceuticals, biotechnology, semiconductors, electronics, industrial applications, healthcare, and water treatment. This market expansion is driven by advancements in industry and infrastructure, along with increased capital investment in cutting-edge manufacturing and water treatment facilities.
The need for high-purity filtration in pharmaceutical and biotechnology processing, semiconductor manufacturing, food and beverage production, and chemical processing has also boosted the demand for PTFE membranes. Filtration systems used in healthcare facilities, industrial plants, and critical processing applications must operate reliably and withstand extreme conditions. Moreover, heightened requirements for contamination control and process efficiency are further propelling market growth.
As advanced filtration systems are increasingly being introduced across various industrial sectors, the global consumption of PTFE membranes continues to rise.
"The hydrophobic segment is projected to be the largest segment, by type, in the PTFE membranes market during the forecast period."
In the PTFE membranes market, hydrophobic membranes are expected to hold the largest share due to their excellent chemical resistance, low moisture absorption, and high thermal stability. These membranes are commonly used in both water and gas filtration. They find extensive applications in pharmaceutical and biotechnology processing, industrial filtration, semiconductor manufacturing, water treatment, and venting. There is rising demand for contamination control, sterile gas filtration, and reliable membrane performance under harsh operating conditions, all of which are key drivers of growth in the hydrophobic PTFE membranes market across various end-use sectors.
"The microfiltration segment is projected to be the largest technology segment in the PTFE membranes market during the forecast period."
During the forecast period, microfiltration is expected to lead the PTFE membrane technology segment due to its superior filtration performance, ease of operation, and ability to simultaneously remove suspended solids, bacteria, and other pollutants from liquids and gases. In addition to its significant role in the pharmaceutical and biotechnology sectors, microfiltration is also essential in the food and beverage industry, water and wastewater treatment, electronics, and various industrial filtration processes. The growing demand for highly pure filtration, contamination control, and effective treatment of process streams is driving the increased use of microfiltration PTFE membranes across numerous end-use industries.
"The spiral segment is projected to be the largest segment, by form, in the PTFE membranes market during the forecast period."
During the forecast period, spiral configurations in the form segment are expected to account for the largest share of the PTFE membranes market. This is due to their ability to provide a high membrane surface area within a compact design, ensuring efficient filtration and effective space utilization. Spiral configurations have been widely used in filtration applications across water treatment, pharmaceuticals, biotechnology, and other industrial sectors requiring high product throughput. The growing demand for efficient filtration systems with compact membrane designs and continuous processing across various end-use industries is expected to drive adoption of spiral PTFE membrane configurations.
"The food & beverage is projected to be the largest application segment in the PTFE membranes market during the forecast period."
During the forecast period, the food & beverage application segment is expected to account for the largest share of PTFE membrane demand. This is due to their high chemical resistance, thermal stability, and consistent filtration performance. These membranes are utilized for liquid and gas filtration, sterile processing, clarification, and contamination control in food and beverage processing. The growing demand for improved product purity, process efficiency, food safety, and hygienic manufacturing is anticipated to drive the increased use of PTFE membrane solutions in the food & beverage industry.
"The Asia Pacific is projected to be the largest region in the PTFE membranes market during the forecast period."
The PTFE membranes market in the Asia Pacific region is projected to experience significant revenue growth by 2031. This anticipated rise is primarily driven by industrialization, the development of manufacturing capacity, the production of pharmaceuticals and biotechnology products, and increased investment in filtration and water treatment technologies.
Key countries like China, India, Japan, and South Korea are driving demand for PTFE membranes, fueled by the expansion of sectors such as semiconductor and electronics manufacturing, healthcare facilities, chemical processing, and the food and beverage industries. PTFE membranes are essential in industries such as pharmaceuticals, water and wastewater treatment, and industrial applications, where high-purity and reliable filtration are crucial. They are increasingly used in semiconductor processing and contamination control due to their effectiveness as ultra-fine filters.
Additionally, the region is expected to benefit from rising investments in the production of pharmaceutical chemicals, semiconductors, and electronic goods, as well as the construction of industrial units, improvements in water and wastewater treatment, and upgrades to healthcare facilities. The growing need for advanced filtration technologies for high-performance operations is a major driver of the expansion of the PTFE membranes market in Asia Pacific.
By Company Type: Tier 1 (40%), Tier 2 (30%), and Tier 3 (30%)
By Designation: Directors (30%), Managers (20%), and Others (50%)
By Region: North America (20%), Europe (10%), Asia Pacific (40%), South America (10%), and the Middle East & Africa (20%)
Companies Covered: Pall Corporation (US), Cytiva (US), W. L. Gore & Associates, Inc. (US), Merck KGaA (US), Corning Incorporated (US), Donaldson Company, Inc. (US), Saint-Gobain (France), Sartorius AG (Germany), HYUNDAI MICRO Co., Ltd. (South Korea), and Sumitomo Electric Industries, Ltd. (Japan) are covered in the report.
The study includes an in-depth competitive analysis of these key players in the PTFE membrane market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the PTFE membranes market based on type (hydrophobic, hydrophilic), technology (reverse osmosis, nanofiltration, ultrafiltration, microfiltration), form (spiral, tubular, plate & frame, hollow fiber), and application (electronics filtration, medical & pharmaceuticals, food & beverage, water & wastewater treatment, chemical processing, oil & gas, other applications). The report's scope covers detailed information regarding drivers, restraints, challenges, and opportunities influencing the growth of the PTFE membranes market. A detailed analysis of the key industry players has been conducted to provide insights into their business overview, products offered, and key strategies, such as mergers, acquisitions, product launches, partnerships, and expansions, associated with the PTFE membranes market. This report covers a competitive analysis of upcoming startups in the PTFE membranes market ecosystem.
Reasons to Buy the Report
The report will provide market leaders/new entrants with the closest approximations of revenue numbers for the overall PTFE membrane market and its subsegments. This report will help stakeholders understand the competitive landscape, gain deeper insights into how to better position their businesses, and plan suitable go-to-market strategies. The report will help stakeholders understand the market pulse and provide information on key drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
- Analysis of key drivers (increasing demand for industrial filtration, implementation of stringent environmental regulations to curb emissions and pollution, and rising demand for PTFE membranes in medical and pharmaceutical industries), restraints (high production cost, preference for polyvinylidene fluoride (PVDF), polyethersulfone (PES), and ceramic membranes), opportunities (rising use of ePTFE membranes in microfiltration and venting applications and medical accessories, and increasing demand for treated water in developing economies), and challenges (volatility in raw material prices).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the PTFE membranes market.
- Market Development: Comprehensive information about profitable markets; the report analyzes the PTFE membranes market across varied regions.
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the PTFE membranes market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players such as Pall Corporation (US), Cytiva (US), W. L. Gore & Associates, Inc. (US), Merck KGaA (US), Corning Incorporated (US), Donaldson Company, Inc. (US), Saint-Gobain (France), Sartorius AG (Germany), HYUNDAI MICRO Co., Ltd. (South Korea), and Sumitomo Electric Industries, Ltd. (Japan), among others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 UNIT CONSIDERED
- 1.3.4.1 Unit
- 1.3.4.2 Volume unit
- 1.4 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING PTFE MEMBRANE MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PTFE MEMBRANE MARKET PLAYERS
- 3.2 PTFE MEMBRANE MARKET, BY TYPE
- 3.3 PTFE MEMBRANE MARKET, BY TECHNOLOGY
- 3.4 PTFE MEMBRANE MARKET, BY FORM
- 3.5 PTFE MEMBRANE MARKET, BY APPLICATION
- 3.6 PTFE MEMBRANE MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising industrial filtration requirements
- 4.2.1.2 Stringent environmental regulations
- 4.2.1.3 Expanding medical and pharmaceutical applications of PTFE membranes
- 4.2.2 RESTRAINTS
- 4.2.2.1 High production cost of PTFE membranes
- 4.2.2.2 Increasing adoption of alternative membrane materials such as PVDF, PES, and ceramic membranes
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rising use of EPTFE membranes in microfiltration, venting applications, and medical accessories
- 4.2.3.2 Increasing demand for treated water in developing countries
- 4.2.4 CHALLENGES
- 4.2.4.1 Volatility in PTFE raw material prices
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN PTFE MEMBRANE MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND TRANSITION TOWARD CONNECT ECOSYSTEM
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 TRANSITION TOWARD CONNECTED ECOSYSTEM
- 4.6 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF SUBSTITUTES
- 5.1.2 BARGAINING POWER OF SUPPLIERS
- 5.1.3 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 THREAT OF NEW ENTRANTS
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 GLOBAL GDP TRENDS
- 5.2.2 TRENDS IN GLOBAL CHEMICAL PROCESSING INDUSTRY
- 5.2.3 TRENDS IN GLOBAL MEDICAL & PHARMACEUTICALS INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF PTFE MEMBRANES, BY REGION, 2023-2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF PTFE MEMBRANES, BY TYPE, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 842129 AND 832139)
- 5.6.2 EXPORT SCENARIO (HS CODE 842129 AND 842139)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 STRENGTHENING PROCESS FILTRATION WITH CHEMICALLY RESISTANT PTFE MEMBRANES
- 5.10.2 STRENGTHENING PHARMACEUTICAL FILTRATION WITH CHEMICALLY RESISTANT PTFE MEMBRANES
- 5.11 IMPACT OF 2025 US TARIFF - PTFE MEMBRANE MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON REGIONS
- 5.11.4.1 North America
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY/EMERGING TECHNOLOGIES
- 6.1.1 TAILORED PTFE PORE STRUCTURES AND ASYMMETRIC MEMBRANES
- 6.1.2 HYDROPHILICALLY MODIFIED PTFE MEMBRANES
- 6.1.3 ADVANCED PTFE NANOFIBROUS AND EPTFE MEMBRANES
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SURFACE MODIFICATION AND ANTIFOULING TECHNOLOGIES
- 6.2.2 PRECISION MEMBRANE PORE AND MODULE ENGINEERING
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 EPTFE-REINFORCED COMPOSITE MEMBRANES FOR FUEL CELLS
- 6.3.2 AI-ASSISTED MEMBRANE DESIGN AND PERFORMANCE OPTIMIZATION
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2026-2027) |OPTIMIZATION & PERFORMANCE ENHANCEMENT
- 6.4.2 MID-TERM (2028-2030) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2031-2035+) | ADVANCED FUNCTIONALITY & SUSTAINABLE INNOVATION
- 6.5 PATENT ANALYSIS
- 6.5.1 LEGAL STATUS OF PATENTS
- 6.5.2 JURISDICTION ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.6.1 ADVANCED PTFE MEMBRANE & HIGH-EFFICIENCY FILTRATION TECHNOLOGIES
- 6.6.2 AUTOMATED MEMBRANE FILTRATION CONTROL & ADVANCED SYSTEM TECHNOLOGIES
- 6.6.3 SMART PTFE MEMBRANE PERFORMANCE MONITORING SYSTEMS
- 6.6.4 DIGITAL MANUFACTURING & MEMBRANE SYSTEM INTEGRATION PLATFORMS
- 6.6.5 ADVANCED MEMBRANE SEPARATION & HIGH-PERFORMANCE FILTRATION TECHNOLOGIES
- 6.7 IMPACT OF AI/GEN AI ON PTFE MEMBRANE MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY PLAYERS IN PTFE MEMBRANE MARKET
- 6.7.3 CASE STUDIES RELATED TO AI IMPLEMENTATION IN PTFE MEMBRANE MARKET
- 6.7.4 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI AND DIGITAL TECHNOLOGY-BASED PTFE MEMBRANES
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 REGULATORY POLICY INITIATIVES
- 7.2.1 SAFETY PROTOCOLS
- 7.2.2 SUSTAINABLE DEVELOPMENT
- 7.2.3 STANDARDIZATION
- 7.2.4 CIRCULAR ECONOMY
- 7.3 SUSTAINABILITY INITIATIVES
- 7.3.1 THERMAL PERFORMANCE, ENVIRONMENTAL COMPLIANCE, AND SAFETY INITIATIVES
- 7.3.1.1 Low-carbon materials and sustainable product strategies
- 7.3.1.2 Application-level efficiency and retrofit opportunities
- 7.3.1 THERMAL PERFORMANCE, ENVIRONMENTAL COMPLIANCE, AND SAFETY INITIATIVES
- 7.4 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.5 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS APPLICATIONS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 PTFE MEMBRANE MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 HYDROPHOBIC
- 9.2.1 EXTENSIVE USE IN STERILE VENTING AND OIL & GAS FILTRATION APPLICATIONS TO FOSTER MARKET GROWTH
- 9.3 HYDROPHILIC
- 9.3.1 RISING USE IN PHARMACEUTICALS INDUSTRY FOR STERILE FILTRATION OF AQUEOUS SOLUTIONS TO DRIVE MARKET
10 PTFE MEMBRANE MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.2 REVERSE OSMOSIS
- 10.2.1 ABILITY TO RESIST DIVERSE PH LEVELS, TEMPERATURES, AND HARSH CHEMICALS TO BOOST DEMAND
- 10.3 MICROFILTRATION
- 10.3.1 POTENTIAL TO WITHSTAND AGGRESSIVE SOLVENTS AND ACIDS IN CHALLENGING ENVIRONMENTS TO SPUR DEMAND
- 10.4 NANOFILTRATION
- 10.4.1 EFFECTIVENESS IN FACILITATING INDUSTRIAL WASTEWATER TREATMENT AND RESOURCE RECOVERY TO SPIKE ADOPTION
- 10.5 ULTRAFILTRATION
- 10.5.1 PROFICIENCY IN REMOVING BACTERIA, VIRUSES, AND OTHER LARGE MOLECULES FROM LIQUIDS TO STIMULATE DEMAND
11 PTFE MEMBRANE MARKET, BY FORM
- 11.1 INTRODUCTION
- 11.2 SPIRAL
- 11.2.1 EXTENSIVE UTILIZATION OF SPIRAL PTFE MEMBRANE IN FOOD & BEVERAGES INDUSTRY TO DRIVE MARKET
- 11.3 TUBULAR
- 11.3.1 GROWING USE IN DAIRY AND WINE INDUSTRIES TO REDUCE BACTERIA IN MILK WHEY TO SUPPORT MARKET GROWTH
- 11.4 PLATE & FRAME
- 11.4.1 INCREASING FILTRATION REQUIREMENTS FROM VARIOUS INDUSTRIES TO ACCELERATE ADOPTION
- 11.5 HOLLOW FIBER
- 11.5.1 EXTENSIVE USE IN BEVERAGES INDUSTRY FOR ULTRAFILTRATION AND MICROFILTRATION OF MEMBRANE SYSTEMS TO DRIVE MARKET
12 PTFE MEMBRANE MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 ELECTRONICS FILTRATION
- 12.2.1 SEMICONDUCTORS
- 12.2.1.1 Extensive use of filtration and purification processes in semiconductor manufacturing to drive market
- 12.2.2 DISPLAYS
- 12.2.2.1 Surging demand for miniaturized devices to facilitate market growth
- 12.2.3 OTHER ELECTRONICS FILTRATION APPLICATIONS
- 12.2.1 SEMICONDUCTORS
- 12.3 MEDICAL & PHARMACEUTICAL
- 12.3.1 ESCALATING USE IN DRUG DELIVERY SYSTEMS AND SURGICAL SUCTION FILTERS TO DETOXIFY CHEMICALS TO PROPEL MARKET
- 12.4 FOOD & BEVERAGE
- 12.4.1 STRINGENT HYGIENE STANDARDS IN FOOD & BEVERAGES INDUSTRY TO FUEL MARKET GROWTH
- 12.5 WATER & WASTEWATER TREATMENT
- 12.5.1 BIOLOGICAL WASTEWATER TREATMENT
- 12.5.1.1 Water reuse initiatives to expand opportunities for PTFE membrane applications
- 12.5.2 MUNICIPAL WATER TREATMENT
- 12.5.2.1 Stringent regulatory frameworks governing water quality to uptick utilization of membrane-based systems
- 12.5.3 OTHER WATER & WASTEWATER TREATMENT APPLICATIONS
- 12.5.1 BIOLOGICAL WASTEWATER TREATMENT
- 12.6 CHEMICAL PROCESSING
- 12.6.1 INCREASING DEMAND IN CHEMICALS INDUSTRY TO BOOST MARKET
- 12.7 OIL & GAS
- 12.7.1 SURGING NEED TO MAXIMIZE CONTAMINANT REMOVAL AND MINIMIZE MAINTENANCE DOWNTIME TO DRIVE MARKET
- 12.8 OTHER APPLICATIONS
13 PTFE MEMBRANE MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Rising demand from pharmaceutical and biotechnology companies to accelerate market growth
- 13.2.2 CANADA
- 13.2.2.1 Elevating demand for meat, poultry, and dairy products to drive market
- 13.2.3 MEXICO
- 13.2.3.1 Growing focus on power generation and transmission infrastructure development to boost demand
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 GERMANY
- 13.3.1.1 Greater emphasis on water reuse and wastewater treatment to spike demand
- 13.3.2 FRANCE
- 13.3.2.1 Stringent environmental regulations and increasing emphasis on water reuse to support market expansion
- 13.3.3 SPAIN
- 13.3.3.1 Increasing industrial activity and water-intensive production processes to create growth opportunities
- 13.3.4 UK
- 13.3.4.1 Expanding pharmaceuticals, chemicals, and water treatment sectors to fuel adoption of PTFE membranes
- 13.3.5 ITALY
- 13.3.5.1 Rapid industrialization and stringent water & wastewater treatment regulations to foster market growth
- 13.3.6 REST OF EUROPE
- 13.3.1 GERMANY
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Growing emphasis on water reuse and pollution control to spike demand
- 13.4.2 INDIA
- 13.4.2.1 Increasing requirements for contamination control and water reuse to reinforce demand
- 13.4.3 JAPAN
- 13.4.3.1 Rising investment in water recycling and treatment technologies to facilitate market growth
- 13.4.4 SOUTH KOREA
- 13.4.4.1 Government initiatives promoting ready-to-eat, specialty, and export-focused food to contribute to market growth
- 13.4.5 AUSTRALIA
- 13.4.5.1 Pressing need to address water scarcity issues and promote water recycling to drive PTFE membrane adoption
- 13.4.6 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 GCC
- 13.5.1.1 Saudi Arabia
- 13.5.1.1.1 Expansion of desalination, wastewater treatment, and industrial water-reuse infrastructure to drive market
- 13.5.1.2 UAE
- 13.5.1.2.1 Presence of multinational players in medical & pharmaceuticals industry to promote market growth
- 13.5.1.3 Kuwait
- 13.5.1.3.1 Continued growth in refining and petrochemical activities due to strong hydrocarbon base to support market growth
- 13.5.1.4 Rest of GCC
- 13.5.1.1 Saudi Arabia
- 13.5.2 SOUTH AFRICA
- 13.5.2.1 Recurring drought conditions and limited freshwater availability, to create PTFE membrane requirement
- 13.5.3 REST OF MIDDLE EAST & AFRICA
- 13.5.1 GCC
- 13.6 SOUTH AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Expanding industrial and water treatment activities to drive market
- 13.6.2 ARGENTINA
- 13.6.2.1 Oil & gas and mining industries to contribute to market growth
- 13.6.3 REST OF SOUTH AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023- 2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.5 PRODUCT COMPARISON
- 14.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2024
- 14.6.1 STARS
- 14.6.2 EMERGING LEADERS
- 14.6.3 PERVASIVE PLAYERS
- 14.6.4 PARTICIPANTS
- 14.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.6.5.1 Company footprint
- 14.6.5.2 Region footprint
- 14.6.5.3 Type footprint
- 14.6.5.4 Technology footprint
- 14.6.5.5 Form footprint
- 14.6.5.6 Application footprint
- 14.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.7.1 PROGRESSIVE COMPANIES
- 14.7.2 RESPONSIVE COMPANIES
- 14.7.3 DYNAMIC COMPANIES
- 14.7.4 STARTING BLOCKS
- 14.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.7.5.1 Detailed list of key startups/SMEs
- 14.7.5.2 Competitive benchmarking of key startups/SMEs
- 14.8 COMPANY VALUATION AND FINANCIAL METRICS
- 14.8.1 FINANCIAL METRICS
- 14.8.2 COMPANY VALUATION
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 EXPANSIONS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 PALL CORPORATION
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Deals
- 15.1.1.3.2 Expansions
- 15.1.1.4 MnM view
- 15.1.1.4.1 Right to win
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses & competitive threats
- 15.1.2 CYTIVA
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Deals
- 15.1.2.3.2 Expansions
- 15.1.2.4 MnM view
- 15.1.2.4.1 Right to win
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses & competitive threats
- 15.1.3 W. L. GORE & ASSOCIATES, INC.
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Products offered
- 15.1.3.3 MnM view
- 15.1.3.3.1 Right to win
- 15.1.3.3.2 Strategic choices
- 15.1.3.3.3 Weaknesses & competitive threats
- 15.1.4 MERCK KGAA
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Expansions
- 15.1.4.4 MnM view
- 15.1.4.4.1 Right to win
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses & competitive threats
- 15.1.5 CORNING INCORPORATED
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 MnM view
- 15.1.5.3.1 Right to win
- 15.1.5.3.2 Strategic choices
- 15.1.5.3.3 Weaknesses & competitive threats
- 15.1.6 DONALDSON COMPANY, INC.
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.6.3.1 Deals
- 15.1.6.3.2 Expansions
- 15.1.6.4 MnM view
- 15.1.7 SAINT-GOBAIN
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 MnM view
- 15.1.8 SARTORIUS AG
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Expansions
- 15.1.8.4 MnM view
- 15.1.9 HYUNDAI MICRO CO., LTD.
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.9.3.1 Product launches
- 15.1.9.3.2 Expansions
- 15.1.9.4 MnM view
- 15.1.10 SUMITOMO ELECTRIC INDUSTRIES, LTD.
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.3.1 Deals
- 15.1.10.4 MnM view
- 15.1.1 PALL CORPORATION
- 15.2 OTHER PLAYERS
- 15.2.1 AGILENT TECHNOLOGIES, INC.
- 15.2.2 COBETTER
- 15.2.3 ENTEGRIS, INC.
- 15.2.4 GVS S.P.A.
- 15.2.5 INTERSTATE SPECIALTY PRODUCTS
- 15.2.6 JINYOU
- 15.2.7 MEISSNER FILTRATION PRODUCTS, INC.
- 15.2.8 MEMBRANE SOLUTIONS (NANTONG)
- 15.2.9 METICLAB CO.,LTD.
- 15.2.10 PHILLIPS SCIENTIFIC INC.
- 15.2.11 PORVAIR FILTRATION GROUP
- 15.2.12 SHANDONG SENRONG NEW MATERIALS CO., LTD.
- 15.2.13 STERLITECH CORPORATION
- 15.2.14 THEWAY MEMBRANES
- 15.2.15 ZEUS COMPANY LLC
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 List of secondary sources
- 16.1.1.2 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key data from primary sources
- 16.1.2.2 Key industry insights
- 16.1.2.3 Breakdown of primary interviews
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.2.1 BOTTOM-UP APPROACH
- 16.2.2 TOP-DOWN APPROACH
- 16.3 DATA TRIANGULATION
- 16.4 STUDY ASSUMPTIONS
- 16.5 RESEARCH LIMITATIONS
- 16.6 1.5 RISK ANALYSIS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS


