
|
시장보고서
상품코드
2132655
투명교정 시장 예측(-2031년) : 재료(폴리우레탄, 글리콜 변성 폴리에틸렌 테레프탈레이트, 다층 열가소성 수지), 연령층(십대, 성인), 판매 채널별(온라인, 오프라인)Clear Aligners Market by Material (Polyurethane, Polyethylene Terephthalate Glycol-modified, Multilayer Thermoplastic), By Age (Teenagers & Adults), By Distribution Channel (Online & Offline) - Global Forecast to 2031 |
||||||

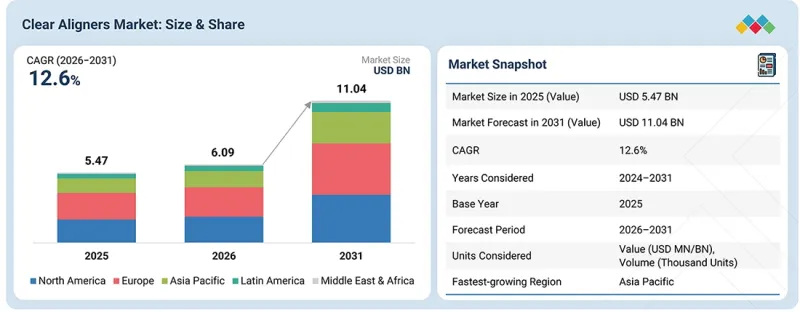
세계의 투명교정 시장 규모는 2026년 60억 9,000만 달러에서 2031년에는 110억 4,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간 중 CAGR은 12.6%에 달할 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) |
| 부문 | 연령층, 판매 채널, 재료, 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카, GCC 국가 |
투명교정 시장은 심미성이 뛰어나고 탈부착이 가능하며, 디지털 계획을 통한 교정 치료에 대한 선호도가 높아짐에 힘입어 꾸준히 성장하고 있습니다. 성인층의 수용도 향상, 눈에 띄지 않는 교정 솔루션에 대한 인지도 제고, 디지털 치과의 지속적인 보급에 힘입어 환자들은 기존의 고정식 교정 장치를 대체할 대안으로 투명교정를 고려하고 있습니다. 취업 연령대의 성인층에서 교정 치료가 확대되는 데 더해, 10대 청소년 및 그보다 더 어린 환자층의 수용도 증가도 대상 환자층을 넓혀 시장의 성장을 지원하고 있습니다.
연령대별로는 성인층이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다.
성인 부문의 성장은 주로 심미성이 뛰어나고 눈에 띄지 않는 교정 치료, 그리고 탈부착이 가능한 장치의 편의성에 대한 강한 수요에 기인합니다. 투명 교정 장치는 고정식 교정 장치로 인한 눈에 띄는 점이나 라이프스타일상의 제약을 피하고자 하는 직장인이나 성인 환자에게 특히 매력적입니다. 한편, 제조사들이 치료 순응도, 치아 맹출, 성장 과정의 치열에 대응한 전용 제품 및 치료 기능을 도입함에 따라 10대 부문의 중요성도 높아지고 있습니다. 임상 현장에서의 수용도가 높아짐에 따라 교정 치과의사들은 더 폭넓은 연령대의 청소년 환자에게 얼라이너를 사용하고 있습니다.
소재별로는 폴리우레탄이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다.
이 시장 부문의 성장은 투명성, 유연성, 내구성, 그리고 맞춤형 교정 장치에 대한 적합성을 모두 갖추고 있기 때문입니다. PETG 및 기타 열가소성 수지도 투명성, 치수 안정성, 확립된 열성형 특성으로 인해 계속해서 사용되고 있지만, 다층 열가소성 수지는 하나의 얼라이너에 서로 다른 재료 특성을 결합할 수 있다는 점에서 주목을 받고 있습니다. 고성능성 폴리머 및 직접 3D 프린팅 방식의 얼라이너 개발이 진행됨에 따라 소재 선택의 폭이 더욱 넓어지고 있으며, 제조사는 적합성, 착용감, 내구성, 치료 성능의 향상을 도모할 수 있게 되었습니다.
판매 채널별로는 오프라인이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다.
치료에는 일반적으로 전문가의 진단, 디지털 스캔 또는 인상 채취, 치료 계획 수립, 얼라이너 착용, 정기적인 임상 관리가 필요하며, 이것이 해당 부문의 성장 요인이 되고 있습니다. 따라서 교정치과 의사나 치과 병원이 여전히 치료 제공의 주요 거점이 되고 있습니다. 한편, 온라인 및 디지털 대응 채널도 온라인 진료, 디지털 증례 제출, 온라인 환자 유치, 원격 모니터링을 통해 그 중요성이 커지고 있습니다. 시장은 완전한 소비자 직접 판매형 치료보다는 온라인과 오프라인을 통합한 모델로 전환되고 있으며, 제조사와 치과 의료 제공자는 전문가의 관리를 유지하면서 디지털 툴을 활용하여 환자와의 접점을 강화하고 있습니다.
지역별로는 미국이 가장 큰 시장 점유율을 차지하고 있습니다.
미국의 투명 교정기 시장은 심미성이 높고 탈부착이 가능한 교정 치료에 대한 선호도 증가, 디지털 계획을 통한 교정 치료의 수용 확대, 교정 치료를 받고 있는 방대한 환자 기반에 힘입어 꾸준히 성장하고 있습니다. 미국 교정치과의사협회(American Association of Orthodontists)는 2025년 경제 및 환자 조사(Economics and Patient Census Study)에서 교정치과 환자 수가 지속적으로 증가하고 있다고 보고했으며, 성인 및 청소년 환자 모두에서 투명 교정 장치에 대한 수용도가 높아지면서 대상 시장이 확대되고 있습니다. 교정 치과의사, 일반 치과의사, DSO(치과 진료소 운영 조직), 그리고 디지털 치과 인프라의 강력한 존재감이 미국내 투명 교정기 치료의 보급을 더욱 지원하고 있습니다.
이 보고서에서는 전 세계 투명 교정기 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추이 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 투명교정 시장 : 재료별
제10장 투명교정 시장 : 연령층별
제11장 투명교정 시장 : 판매 채널별
제12장 투명교정 시장 : 지역별
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSA 26.10.01The global clear aligners market is projected to reach USD 11.04 billion by 2031 from USD 6.09 billion in 2026, at a CAGR of 12.6% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Age Group, Distribution Channel, Material, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa, and GCC Countries |
The clear aligners market is expanding steadily, supported by the growing preference for aesthetic, removable, and digitally planned orthodontic treatments. Increasing acceptance among adults, rising awareness of discreet orthodontic solutions, and continued adoption of digital dentistry are encouraging patients to consider clear aligners as an alternative to conventional fixed braces. The expansion of orthodontic treatment among working-age adults, together with increasing acceptance among teenagers and younger patients, is broadening the addressable patient pool and supporting market growth.
By age group, adults are expected to account for the largest market share in the clear aligners market.
Growth in the adults market segment is mainly due to their strong preference for aesthetically discreet orthodontic treatment and the convenience of removable appliances. Clear aligners are particularly attractive to working professionals and adult patients who may prefer to avoid the visibility and lifestyle limitations associated with fixed braces. At the same time, the teenage segment is gaining importance as manufacturers introduce dedicated products and treatment features addressing compliance, tooth eruption, and growing dentition, while increasing clinical acceptance is encouraging orthodontists to use aligners for a broader range of younger patients.
By material, polyurethane is expected to account for the largest market share in the clear aligners market.
Growth in this market segment stems from its combination of transparency, flexibility, durability, and suitability for customized orthodontic appliances. PETG and other thermoplastic materials continue to be used for their transparency, dimensional stability, and established thermoforming characteristics, while multilayer thermoplastic materials are gaining attention for their ability to combine different material properties in a single aligner. Continued development of advanced polymers and direct 3D-printed aligners is further broadening the material landscape and enabling manufacturers to improve fit, comfort, durability, and treatment performance.
By distribution channel, offline channels are expected to account for the largest market share in the clear aligners market.
Segmental growth is due to the fact that treatment generally requires professional diagnosis, digital scanning or impressions, treatment planning, aligner fitting, and periodic clinical supervision. Orthodontists and dental practices therefore remain the principal points of treatment delivery. Online and digitally enabled channels are nevertheless gaining importance through virtual consultations, digital case submission, online patient acquisition, and remote monitoring. The market is increasingly moving toward integrated online-to-offline models rather than fully direct-to-consumer treatment, with manufacturers and dental providers using digital tools to improve patient engagement while maintaining professional oversight.
The US accounts for the largest market share in the clear aligners market.
The US clear aligners market is expanding steadily, supported by increasing preference for aesthetic and removable orthodontic treatment, growing acceptance of digitally planned orthodontic care, and a large base of patients undergoing orthodontic treatment. The American Association of Orthodontists reported continued growth in orthodontic patient volumes in its 2025 Economics and Patient Census Study, while the increasing acceptance of clear aligners among both adults and younger patients is expanding the addressable market. The strong presence of orthodontists, general dentists, DSOs, and digital dentistry infrastructure further supports adoption of clear aligner treatment in the U.S
A breakdown of the primary participants (supply side) for the clear aligners market referred to for this report is provided below:
- By Company Type: Tier 1 (35%), Tier 2 (40%), and Tier 3 (25%)
- By Designation: C-level Executives (45%), Directors (35%), and Others (20%)
- By Region: North America (27%), Europe (25%), Asia Pacific (30%), Latin America (8%), and the Middle East & Africa (10%)
The prominent players in the clear aligners market include Align Technology, AngelAlign Technology, Envista Holdings Corporation, Straumann Group, and Dentsply Sirona.
Research Coverage:
The report analyzes the clear aligners market and estimates its size and future growth potential across segments such as age group, material, distribution channel, and region. The report also includes a competitive analysis of the key players in this market along with their company profiles, service offerings, recent developments, and key market strategies.
Reasons to Buy the Report
The report will help market leaders/new entrants in this market by providing the closest approximations of revenue numbers for the overall clear aligners market. This report will help stakeholders understand the competitive landscape and gain deeper insights to better position their businesses and plan suitable go-to-market strategies. The report also helps stakeholders understand the market pulse and provides information on key drivers, restraints, challenges, and opportunities.
This report provides insights into the following points:
- Analysis of key drivers (growing preference for aesthetic and removable orthodontic treatment and increasing adoption of digital dentistry and treatment-planning technologies), restraints (high treatment costs and patient compliance requirements), challenges (clinical limitations of clear aligners in complex orthodontic cases and need for professional monitoring), and opportunities (increasing adoption of 3D printing, AI-enabled treatment planning, and digitally integrated orthodontic workflows) contributing to the growth of the clear aligners market.
- Market Penetration: It includes extensive information on products offered by the major players in the global clear aligners market. The report includes various segments in material, age group, distribution channel, and region.
- Product Enhancement/Innovation: Comprehensive details about new product launches and anticipated trends in the global clear aligners market.
- Market Development: Thorough knowledge and analysis of the profitable rising markets by material, age group, distribution channel, and region.
- Market Diversification: Comprehensive information about newly launched products, expanding markets, current advancements, and investments in the global clear aligners market.
- Competitive Assessment: Thorough evaluation of the market shares, growth plans, product offerings, and capacities of the major competitors in the global clear aligners market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 REGIONAL SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 CLEAR ALIGNERS MARKET OVERVIEW
- 3.2 ASIA PACIFIC: CLEAR ALIGNERS MARKET, BY AGE GROUP AND COUNTRY (2025)
- 3.3 CLEAR ALIGNERS MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 REGIONAL MIX: CLEAR ALIGNERS MARKET (2026-2031)
- 3.5 CLEAR ALIGNERS MARKET: DEVELOPED MARKETS VS. EMERGING ECONOMIES
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing prevalence of malocclusion and growing need for orthodontic treatment
- 4.2.1.2 Rising demand for aesthetic and minimally visible orthodontic treatment in adults
- 4.2.1.3 Expansion of dental service organizations and digital orthodontic care networks
- 4.2.2 RESTRAINTS
- 4.2.2.1 High treatment costs and limited insurance/reimbursement coverage
- 4.2.2.2 Dependence on patient compliance and limited effectiveness in complex orthodontic cases
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of digital orthodontics and tele-orthodontic care in emerging markets
- 4.2.3.2 Increasing adoption by general dentists and expansion into untapped patient populations
- 4.2.4 CHALLENGES
- 4.2.4.1 Increasing competition from low-cost and direct-to-consumer providers
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND SCROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER- 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT FROM NEW ENTRANTS
- 5.1.2 THREAT FROM SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN CLEAR ALIGNERS MARKET
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 SUPPLY CHAIN ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE, BY KEY PLAYER, 2023-2025
- 5.6.2 AVERAGE SELLING PRICE, BY PRODUCT, 2023-2025
- 5.6.3 AVERAGE SELLING PRICE, BY REGION, 2023-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 9021)
- 5.7.2 EXPORT SCENARIO (HS CODE 9021)
- 5.8 KEY CONFERENCES & EVENTS DURING 2026
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.10 INVESTMENT & FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.12 IMPACT OF 2025 US TARIFFS-CLEAR ALIGNERS MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 Asia Pacific
- 5.12.5 IMPACT ON END-USER INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 ARTIFICIAL INTELLIGENCE (AI)-ENABLED TREATMENT PLANNING & DIGITAL ORTHODONTICS
- 6.1.2 DIRECT 3D-PRINTED CLEAR ALIGNERS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 SMART CLEAR ALIGNERS AND EMBEDDED SENSOR TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 INTRAORAL SCANNING TECHNOLOGY
- 6.3.2 CAD/CAM SOFTWARE AND DIGITAL TREATMENT PLANNING
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM |RECENT TECHNOLOGIES| FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.5 PATENT ANALYSIS
- 6.5.1 PATENT PUBLICATION TRENDS FOR CLEAR ALIGNERS
- 6.5.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 6.5.3 TOP APPLICANTS & OWNERS (COMPANIES/INSTITUTIONS) FOR CLEAR ALIGNERS PATENTS (JANUARY 2015-DECEMBER 2025)
- 6.5.4 TOP APPLICANT COUNTRIES/REGIONS PATENTS FOR CLEAR ALIGNERS (JANUARY 2015-DECEMBER 2025)
- 6.6 IMPACT OF AI/GEN AI ON CLEAR ALIGNERS MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 INTERCONNECTED ADJACENT ECOSYSTEMS AND IMPACT ON MARKET PLAYERS
- 6.6.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN CLEAR ALIGNERS MARKET
- 6.7 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.7.1 ALIGN TECHNOLOGY: AI-ENABLED DIGITAL ORTHODONTIC WORKFLOW
- 6.7.2 GRAPHY: COMMERCIALIZATION OF DIRECTLY 3D-PRINTED CLEAR ALIGNERS
- 6.7.3 STRAUMANN (CLEARCORRECT): EXPANDING DIGITAL ORTHODONTICS THROUGH INTEGRATED SOLUTIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 US
- 7.1.2 EUROPEAN UNION
- 7.1.3 CHINA
- 7.1.4 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 ENVIRONMENTAL SUSTAINABILITY IN CLEAR ALIGNER SYSTEMS
- 7.2.2 DIGITAL-EFFICIENT ORTHODONTIC INFRASTRUCTURE
- 7.2.3 SUSTAINABLE PRECISION ORTHODONTICS - CLEAR ALIGNERS
- 7.2.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 INFLUENCE OF KEY STAKEHOLDERS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 CLEAR ALIGNERS MARKET, BY MATERIAL
- 9.1 INTRODUCTION
- 9.2 POLYURETHANE
- 9.2.1 ELASTICITY AND MECHANICAL PERFORMANCE TO SUPPORT POLYURETHANE ADOPTION IN CLEAR ALIGNERS
- 9.3 POLYETHYLENE TEREPHTHALATE GLYCOL (PETG)
- 9.3.1 TRANSPARENCY AND THERMOFORMABILITY TO SUPPORT PETG ADOPTION IN CLEAR ALIGNERS
- 9.4 MULTILAYER THERMOPLASTIC MATERIALS
- 9.4.1 MULTILAYER STRUCTURE TO ENHANCE FORCE CONTROL AND PATIENT COMFORT
- 9.5 OTHER MATERIALS
10 CLEAR ALIGNERS MARKET, BY AGE GROUP
- 10.1 INTRODUCTION
- 10.2 TEENAGERS
- 10.2.1 RISING NEED FOR ORTHODONTIC TREATMENT AND GROWING ACCEPTANCE OF AESTHETIC SOLUTIONS TO DRIVE ADOPTION AMONG TEENAGERS
- 10.3 ADULTS
- 10.3.1 RISING DEMAND FOR AESTHETIC AND CONVENIENT ORTHODONTIC TREATMENT TO DRIVE GROWTH
11 CLEAR ALIGNERS MARKET, BY DISTRIBUTION CHANNEL
- 11.1 INTRODUCTION
- 11.2 ONLINE
- 11.2.1 RISING ADOPTION OF DIGITAL AND REMOTE ORTHODONTIC SERVICES TO PROMOTE ONLINE CHANNEL GROWTH
- 11.3 OFFLINE
- 11.3.1 ESTABLISHED ORTHODONTIC AND DENTAL PRACTICE NETWORKS TO SUPPORT OFFLINE CHANNEL GROWTH
12 CLEAR ALIGNERS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 EUROPE
- 12.2.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 12.2.2 GERMANY
- 12.2.2.1 Strong orthodontic treatment base and digital dentistry adoption support clear aligner market growth
- 12.2.3 ITALY
- 12.2.3.1 Large dental workforce and established orthodontic infrastructure support clear aligner adoption
- 12.2.4 SPAIN
- 12.2.4.1 Rising dental care utilization to propel market growth
- 12.2.5 FRANCE
- 12.2.5.1 Expanding dental workforce and shift toward organized dental care create stronger base for clear aligner adoption
- 12.2.6 UK
- 12.2.6.1 High dental service engagement to favor growth
- 12.2.7 REST OF EUROPE
- 12.3 NORTH AMERICA
- 12.3.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 12.3.2 US
- 12.3.2.1 Strong dental care utilization and high oral health needs to drive market
- 12.3.3 CANADA
- 12.3.3.1 Rising healthcare expenditure to spur growth
- 12.4 ASIA PACIFIC
- 12.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 12.4.2 SOUTH KOREA
- 12.4.2.1 Rapid population aging and expanding medical tourism to support market
- 12.4.3 JAPAN
- 12.4.3.1 Strong dental infrastructure to support market growth
- 12.4.4 CHINA
- 12.4.4.1 Expanding dental infrastructure and large adult population to propel growth
- 12.4.5 INDIA
- 12.4.5.1 Growing dental tourism to support market
- 12.4.6 AUSTRALIA
- 12.4.6.1 High dental-service utilization to sustain growth
- 12.4.7 REST OF ASIA PACIFIC
- 12.5 LATIN AMERICA
- 12.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 12.5.2 BRAZIL
- 12.5.2.1 Strong orthodontic treatment needs and expanding dental infrastructure to favor growth
- 12.5.3 MEXICO
- 12.5.3.1 High oral disease burden and expanding dental service capacity to fuel market
- 12.5.4 REST OF LATIN AMERICA
- 12.6 MIDDLE EAST & AFRICA
- 12.6.1 HIGH ORAL DISEASE BURDEN AND IMPROVING DENTAL INFRASTRUCTURE TO SUPPORT MARKET GROWTH
- 12.6.2 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 12.7 GCC COUNTRIES
- 12.7.1 RISING DEMAND FOR AESTHETIC CARE TO DRIVE MARKET
- 12.7.2 MACROECONOMIC OUTLOOK FOR GCC COUNTRIES
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 13.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN CLEAR ALIGNERS MARKET
- 13.3 REVENUE ANALYSIS, 2021-2025
- 13.4 MARKET SHARE ANALYSIS (2025)
- 13.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.5.1 STARS
- 13.5.2 EMERGING LEADERS
- 13.5.3 PERVASIVE PLAYERS
- 13.5.4 EMERGING COMPANIES
- 13.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.5.5.1 Region footprint
- 13.5.5.2 Age group footprint
- 13.5.5.3 Material footprint
- 13.5.5.4 Distribution channel footprint
- 13.6 COMPANY EVALUATION MATRIX: START-UPS/SMES, 2025
- 13.6.1 PROGRESSIVE COMPANIES
- 13.6.2 STARTING BLOCKS
- 13.6.3 RESPONSIVE COMPANIES
- 13.6.4 DYNAMIC COMPANIES
- 13.6.5 COMPETITIVE BENCHMARKING; KEY STARTUPS/SMES, 2025
- 13.6.5.1 Detailed list of key startups/SMEs
- 13.6.5.2 Competitive benchmarking of key startups/SMEs
- 13.7 R&D EXPENDITURE OF KEY PLAYERS
- 13.8 COMPANY VALUATION AND FINANCIAL METRICS
- 13.8.1 COMPANY VALUATION
- 13.8.2 FINANCIAL METRICS
- 13.9 BRAND/PRODUCT COMPARISON
- 13.10 COMPETITIVE SCENARIO
- 13.10.1 PRODUCT LAUNCHES & APPROVALS
- 13.10.2 DEALS
- 13.10.3 EXPANSIONS
- 13.10.4 OTHER DEVELOPMENTS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 ALIGN TECHNOLOGY, INC.
- 14.1.1.1 Business overview
- 14.1.1.2 Products offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product launches & approvals
- 14.1.1.3.2 Deals
- 14.1.1.3.3 Expansions
- 14.1.1.4 MnM view
- 14.1.1.4.1 Right to win
- 14.1.1.4.2 Strategic choices made
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 ANGELALIGN TECHNOLOGY, INC.
- 14.1.2.1 Business overview
- 14.1.2.2 Products offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.3.2 Deals
- 14.1.2.3.3 Expansions
- 14.1.2.4 MnM view
- 14.1.2.4.1 Right to win
- 14.1.2.4.2 Strategic choices made
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 DENTSPLY SIRONA, INC.
- 14.1.3.1 Business overview
- 14.1.3.2 Products offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Other developments
- 14.1.3.4 MnM view
- 14.1.3.4.1 Right to win
- 14.1.3.4.2 Strategic choices made
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 INSTITUT STRAUMANN AG
- 14.1.4.1 Business overview
- 14.1.4.2 Products offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches & approvals
- 14.1.4.3.2 Deals
- 14.1.4.4 MnM view
- 14.1.4.4.1 Right to win
- 14.1.4.4.2 Strategic choices made
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 ENVISTA HOLDINGS CORPORATION
- 14.1.5.1 Business overview
- 14.1.5.2 Products offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Deals
- 14.1.5.3.2 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Right to win
- 14.1.5.4.2 Strategic choices made
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 SOLVENTUM CORPORATION
- 14.1.6.1 Business overview
- 14.1.6.2 Products offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Product launches
- 14.1.6.3.2 Deals
- 14.1.7 HENRY SCHEIN, INC.
- 14.1.7.1 Business overview
- 14.1.7.2 Products offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Service launches
- 14.1.7.3.2 Deals
- 14.1.8 MODERN DENTAL GROUP LIMITED (TRIOCLEAR)
- 14.1.8.1 Business overview
- 14.1.8.2 Products offered
- 14.1.9 SHANGHAI SMARTEE DENTI-TECHNOLOGY CO., LTD.
- 14.1.9.1 Business overview
- 14.1.9.2 Products offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Deals
- 14.1.9.3.3 Expansions
- 14.1.10 ORTHOCAPS GMBH
- 14.1.10.1 Business overview
- 14.1.11 PRODUCTS OFFERED
- 14.1.1 ALIGN TECHNOLOGY, INC.
- 14.2 OTHER PLAYERS
- 14.2.1 GRAPHY, INC.
- 14.2.2 CLEAR MOVES ALIGNERS
- 14.2.3 MODERN ME GMBH
- 14.2.4 ULAB SYSTEMS, INC.
- 14.2.5 SMILESET
- 14.2.6 SCHEU-DENTAL GMBH
- 14.2.7 THE ARGEN CORPORATION
- 14.2.8 DYNAFLEX
- 14.2.9 TP ORTHODONTICS, INC.
- 14.2.10 PLANMECA OY
- 14.2.11 CANDID CARE CO.
- 14.2.12 K LINE EUROPE GMBH
- 14.2.13 NOVOALIGN
- 14.2.14 ALIGNERCO CORP.
- 14.2.15 BRIUS TECHNOLOGIES
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH APPROACH
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.3 MARKET BREAKDOWN AND DATA TRIANGULATION
- 15.4 MARKET SHARE ESTIMATION
- 15.5 ASSUMPTIONS
- 15.6 LIMITATIONS
- 15.6.1 METHODOLOGY-RELATED LIMITATIONS
- 15.6.2 SCOPE-RELATED LIMITATIONS
- 15.7 RISK ASSESSMENT
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


