

|
시장보고서
상품코드
2138097
자외선 안정제 시장 : 유형별(HALS, UV 흡수제, 소광제), 용도별(퍼스널케어, 화장품 및 자외선 차단제, 자동차, 포장, 농업, 건축 및 건설, 접착제 및 실란트), 지역별 - 세계 예측(-2031년)UV Stabilizers Market by Type (HALS, UV Absorbers, and Quenchers), Application (Personal Care, Cosmetics & Sunscreens, Automotive, Packaging, Agriculture, Building & Construction, Adhesives & Sealants), and Region - Global Forecast to 2031 |
||||||

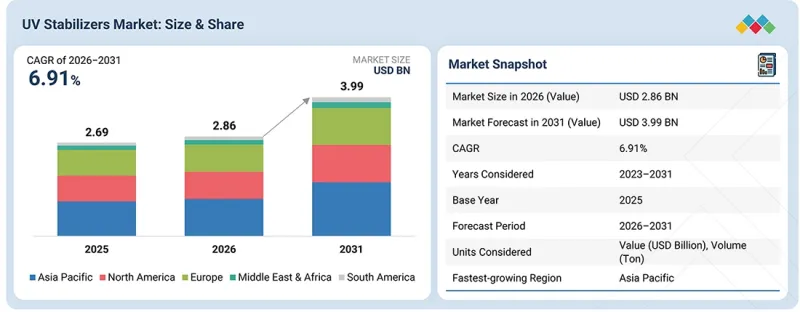
자외선 안정제 시장 규모는 2026년 28억 6,000만 달러에서 2031년에는 39억 9,000만 달러로 확대될 것으로 추정되며, 예측 기간 동안 CAGR은 6.91%가 될 전망입니다.
내구성이 높고 내후성이 뛰어나며 고성능 폴리머 소재에 대한 수요가 증가함에 따라 다양한 용도에서 자외선 안정제의 수요가 확대되고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2023-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러)·톤 |
| 부문 | 유형, 용도, 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미 |
제조업체들은 장기간 자외선 노출로 인해 발생하는 광산화, 표면 열화, 변색, 기계적 특성 저하를 최소화하기 위해 플라스틱에 안정제를 첨가하는 경향이 강해지고 있습니다. 특히 자동차 및 포장 업계에서는 폴리머계 부품 및 제품의 기능적 수명과 외관을 향상시키기 위해 자외선 안정제 기술이 채택되고 있습니다. 또한, 소재의 수명, 실외 내구성, 성능 유지에 대한 관심이 높아짐에 따라 첨단 HALS, 자외선 흡수제, 소광제의 개발이 촉진되고 있으며, 이는 시장 전체의 성장을 뒷받침하고 있습니다.
“HALS 부문은 예측 기간 동안 시장에서 가장 빠르게 성장할 유형이 될 것으로 전망됩니다.”
HALS 부문은 예측 기간 동안 자외선 안정제 시장에서 금액 기준으로 가장 빠르게 성장하는 유형이 될 것으로 추정됩니다. 이러한 성장은 가혹한 노출 조건에서도 장기적인 보호 기능을 제공하는 폴리머 안정화 시스템에 대한 수요 증가에 힘입은 것입니다. HALS는 비교적 낮은 농도에서도 효율적인 안정화 효과를 발휘하며, 장기간에 걸쳐 그 효능을 유지하기 때문에 일관된 보호가 필요한 고도의 배합에 적합합니다. 효율 향상 및 새로운 폴리머 계열과의 호환성 개선 등 HALS의 화학적 특성 개선 또한 자외선 안정제 시장에서의 채택 확대를 뒷받침하고 있습니다.
“용도별로는 건축·건설 분야가 2025년에 금액 기준으로 2위 규모를 차지했습니다.”
2025년, 건축·건설 분야는 장기간의 태양광 노출로부터의 보호가 필요한 지붕용 필름, 형재, 외장재, 실란트, 외장용 도료에 폴리머계 재료가 광범위하게 사용됨에 힘입어, 자외선 안정제 시장에서 금액 기준 2위의 점유율을 차지했습니다. 야외 구조물에서 내구성이 뛰어난 플라스틱 소재의 사용 증가는 치수 안정성, 표면 품질, 기능적 성능을 유지하는 데 도움이 되는 자외선 안정제의 수요를 견인하고 있습니다. 유지보수 주기의 장기화와 내구성이 뛰어난 건축자재에 대한 관심이 높아지고 있는 점도 건설용 배합에 자외선 안정제를 포함시키는 것을 더욱 촉진하고 있습니다.
“유럽은 2025년에 금액 기준으로 3위의 시장 점유율을 차지했습니다.”
2025년, 유럽은 재료의 내구성, 제품 품질, 엄격한 환경 요건 준수에 중점을 두고 있는 것을 배경으로, 금액 기준으로 3위의 점유율을 차지했습니다. 이 지역에서 경량 폴리머 부품 및 재활용 가능한 플라스틱 소재로의 전환에 따라, 반복 사용이나 실외 노출 조건에서도 성능을 유지하는 안정제 기술에 대한 수요가 증가하고 있습니다. 또한, 첨단 폴리머 배합 및 지속가능한 첨가제 시스템의 지속적인 개발이 유럽 시장 전반의 자외선 안정제 수요를 뒷받침하고 있습니다.
본 보고서에서는 전 세계 자외선 안정제 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 정리하고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 자외선 안정제 시장 : 유형별
제10장 자외선 안정제 시장 : 용도별
제11장 자외선 안정제 시장 : 지역별
제12장 경쟁 구도
제13장 기업 개요
제14장 조사 방법
제15장 부록
KSM 26.10.08The UV stabilizers market is estimated to grow from USD 2.86 billion in 2026 to USD 3.99 billion by 2031, at a CAGR of 6.91% during the forecast period. The growing need for longer-lasting, weather-resistant, and high-performance polymer materials is driving demand for UV stabilizers across various applications.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Thousand) and Volume (Ton) |
| Segments | Type, Application, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and South America |
Manufacturers are increasingly incorporating stabilizers into plastics to minimize photo-oxidation, surface deterioration, discoloration, and loss of mechanical properties caused by prolonged UV exposure. The automotive and packaging sectors, in particular, are adopting UV stabilizer technologies to improve the functional life and appearance of polymer-based components and products. Moreover, the increasing focus on material longevity, outdoor durability, and performance retention is encouraging the development of advanced HALS, UV absorbers, and quenchers, supporting overall market growth.
"HALS segment is projected to be the fastest-growing type in the UV stabilizers market during the forecast period."
The HALS segment is estimated to be the fastest-growing type by value in the UV stabilizers market during the forecast period. This growth is supported by the increasing need for polymer stabilization systems that provide prolonged protection under demanding exposure conditions. HALS offer efficient stabilization at relatively low concentrations and maintain their effectiveness over extended service periods, making them suitable for advanced formulations requiring consistent protection. Improvements in HALS chemistry, including higher efficiency and compatibility with newer polymer systems, are further supporting their faster adoption within the UV stabilizers market.
"Building & construction was the second-largest application of UV stabilizers in 2025, in terms of value."
The building & construction application accounted for the second-largest value share of the UV stabilizers market in 2025, driven by the extensive use of polymer-based materials in roofing membranes, profiles, cladding, sealants, and exterior coatings that require protection from prolonged solar exposure. The increasing use of durable plastic materials in outdoor structures is driving demand for UV stabilizers that help preserve dimensional stability, surface quality, and functional performance. The growing emphasis on longer maintenance cycles and durable building materials further supports integrating UV stabilizers into construction-grade formulations.
"Europe accounted for the third-largest share in the global UV stabilizers market, in terms of value, in 2025."
Europe accounted for the third-largest value share of the global UV stabilizers market in 2025, driven by its strong focus on material durability, product quality, and compliance with stringent environmental requirements. The region's shift toward lightweight polymer components and recyclable plastic materials is increasing the need for stabilizer technologies that maintain performance during repeated use and outdoor exposure. In addition, ongoing development of advanced polymer formulations and sustainable additive systems is supporting demand for UV stabilizers across European markets.
- By Company Type: Tier 1 - 55%, Tier 2 - 25%, and Tier 3 - 20%
- By Designation: Directors - 50%, Managers - 30%, and Others - 20%
- By Region: North America - 40%, Europe - 35%, Asia Pacific - 20%, and RoW- 5%
The key players profiled in the report include BASF SE (Germany), Rianlon Corporation (China), Arkema (France), Suqian Unitech Corp., Ltd. (China), Syensqo SA/NV (Belgium), SONGWON Industrial Co., Ltd. (South Korea), ADEKA Corporation (Japan), SABO S.p.A. (Italy), Clariant AG (Switzerland), Everlight Chemical Industrial Corporation (Taiwan), and SI Group, Inc. (US).
Study Coverage
This report segments the market for UV stabilizers based on type, application, and region, and provides estimations in terms of value for the overall market size across various regions. A detailed analysis of key industry players has been conducted to provide insights into their business overviews, services, and key strategies associated with the UV stabilizers market.
Reasons to Buy this Report
This research report is focused on various levels of analysis-industry analysis (industry trends), market share analysis of top players, and company profiles, which together provide an overall view of the competitive landscape, emerging and high-growth segments of the UV stabilizers market, high-growth regions, and market drivers, restraints, and opportunities.
The report provides insights into the following points:
- Market Penetration: Comprehensive information on UV stabilizers offered by top players in the global market
- Analysis of key drivers (expanding plastics production broadens the demand base for UV stabilizers, surging automotive production and premium exterior durability requirements, growing demand from construction industry), restraints (raw material price volatility and petrochemical feedstock dependence, limited HALS precursor availability and supply chain disruptions, high production costs), opportunities (increasing use of nanocomposites in UV stabilizers, growing agricultural films industry), and challenges (technical compatibility challenges in recycled and bio-based polymer systems, stringent government regulations) influencing the growth of the UV stabilizers market.
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the UV stabilizers market.
- Market Development: Comprehensive information about lucrative emerging markets-the report analyzes the market for UV stabilizers across regions.
- Market Diversification: Exhaustive information about new products, untapped regions, and recent developments in the global UV stabilizers market.
- Competitive Assessment: In-depth assessment of market shares, strategies, products, and manufacturing capabilities of leading players in the UV stabilizers market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS OF THE STUDY
- 1.3.3 MARKET DEFINITION AND INCLUSIONS, BY TYPE
- 1.3.4 MARKET DEFINITION AND INCLUSIONS, BY APPLICATION
- 1.3.5 YEARS CONSIDERED
- 1.3.6 CURRENCY CONSIDERED
- 1.3.7 UNIT CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: ASIA PACIFIC MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR UV STABILIZERS MARKET
- 3.2 UV STABILIZERS MARKET, BY TYPE AND REGION
- 3.3 UV STABILIZERS MARKET, BY APPLICATION
- 3.4 UV STABILIZERS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Expanding plastics production
- 4.2.1.2 Surging automotive production and premium exterior durability requirements
- 4.2.1.3 Growing demand from construction industry
- 4.2.2 RESTRAINTS
- 4.2.2.1 Raw material price volatility and petrochemical feedstock dependence
- 4.2.2.2 Limited HALS precursor availability and supply chain disruptions
- 4.2.2.3 High production costs
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing use of nanocomposites in UV stabilizers
- 4.2.3.2 Growing agricultural films industry
- 4.2.4 CHALLENGES
- 4.2.4.1 Technical compatibility challenges in recycled and bio-based polymer systems
- 4.2.4.2 Stringent government regulations
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.3.1 INTERCONNECTED MARKETS
- 4.3.2 CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.4.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST FOR MAJOR ECONOMIES
- 5.2.3 TRENDS IN GLOBAL AUTOMOTIVE INDUSTRY
- 5.2.4 TREND IN GLOBAL BUILDING & CONSTRUCTION INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF UV STABILIZERS OFFERED BY KEY PLAYERS, BY KEY APPLICATIONS, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF UV STABILIZERS, BY REGION, 2023-2031
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 3812)
- 5.6.2 EXPORT SCENARIO (HS CODE 3812)
- 5.7 KEY CONFERENCES & EVENTS IN 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 BASF SE'S CHIMASSORB RANGE OF UV STABILIZERS IMPROVED DURABILITY OF HIGHWAY GEOTEXTILES
- 5.10.2 OMYA INTERNATIONAL AG ADDRESSED YELLOWING IN SMP SEALANTS USING CLARIANT'S ADDWORKS STABILIZATION TECHNOLOGY
- 5.11 IMPACT OF 2025 US TARIFF - UV STABILIZERS MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 UV - C STABILIZATION TECHNOLOGY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 NANOCOMPOSITE TECHNOLOGY
- 6.2.2 ENCAPSULATION TECHNOLOGY
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.3.1 SHORT-TERM (2025-2027) | FORMULATION OPTIMIZATION & PERFORMANCE COMPLIANCE
- 6.3.2 MID-TERM (2027-2030) | PERFORMANCE ENHANCEMENT & MULTI-FUNCTIONALITY
- 6.3.3 LONG-TERM (2030-2035+) | SUSTAINABILITY, ADAPTIVE STABILIZATION & DIGITAL INTEGRATION
- 6.4 PATENT ANALYSIS
- 6.4.1 APPROACH
- 6.4.2 DOCUMENT TYPES
- 6.4.3 TOP APPLICANTS
- 6.4.4 JURISDICTION ANALYSIS
- 6.5 IMPACT OF AI/GEN AI ON UV STABILIZERS MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES IN UV STABILIZERS PROCESSING
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN UV STABILIZERS MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN UV STABILIZERS MARKET
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 ISO 14001 - Environmental Management Systems
- 7.1.2.2 ISO 31000 - Risk Management Guidelines
- 7.1.2.3 ISO 9001 - Quality Management Systems
- 7.1.2.4 ISO 14040 - Life Cycle Assessment (LCA)
- 7.2 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.2.1 SAFETY PROTOCOLS
- 7.2.2 SUSTAINABLE DEVELOPMENT
- 7.2.3 STANDARDIZATION
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS APPLICATIONS
9 UV STABILIZERS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 HALS
- 9.2.1 INCREASED DEMAND FROM FOOD PACKAGING TO DRIVE MARKET
- 9.3 UV ABSORBERS
- 9.3.1 EXPANDING PLASTIC AND COATING APPLICATIONS TO PROPEL MARKET
- 9.4 QUENCHERS
- 9.4.1 ADVANCED LIGHT-QUENCHING CAPABILITY ACCELERATING MARKET ADOPTION
10 UV STABILIZERS MARKET, BY APPLICATION
- 10.1 INTRODUCTION
- 10.2 PERSONAL CARE, COSMETICS & SUNSCREENS
- 10.2.1 EVOLVING CONSUMER PREFERENCES AND REGULATIONS PROPELLING ADOPTION OF UV STABILIZERS
- 10.3 AUTOMOTIVE
- 10.3.1 GROWING AUTOMOTIVE INDUSTRY IN ASIA PACIFIC AND EUROPE TO BOOST MARKET
- 10.4 PACKAGING
- 10.4.1 GROWING DEMAND IN FOOD AND NON-FOOD INDUSTRIES TO DRIVE MARKET
- 10.5 AGRICULTURE
- 10.5.1 INCREASE IN DEMAND FOR GREENHOUSE FILMS & TAPES TO DRIVE DEMAND
- 10.6 BUILDING & CONSTRUCTION
- 10.6.1 EXCELLENT RESISTANCE TO TEMPERATURE AND CLIMATIC CONDITIONS TO DRIVE MARKET GROWTH
- 10.7 ADHESIVES & SEALANTS
- 10.7.1 GROWING DEMAND FROM AUTOMOTIVE SECTOR TO BOOST MARKET
- 10.8 OTHER APPLICATIONS
- 10.8.1 INCREASING DEMAND FOR DURABILITY AND UV PROTECTION MATERIALS TO FUEL MARKET GROWTH
11 UV STABILIZERS MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 ASIA PACIFIC
- 11.2.1 CHINA
- 11.2.1.1 Increasing demand for UV-protected packaging to boost market
- 11.2.2 INDIA
- 11.2.2.1 Industrialization and urbanization to propel market growth
- 11.2.3 JAPAN
- 11.2.3.1 Automotive manufacturing and polymer applications to accelerate demand
- 11.2.4 SOUTH KOREA
- 11.2.4.1 Rising need for durable polymer performance to boost market
- 11.2.5 THAILAND
- 11.2.5.1 High demand for UV-resistant plastic and wood in construction industry to drive market
- 11.2.6 MALAYSIA
- 11.2.6.1 High demand from polymer industry to drive market
- 11.2.1 CHINA
- 11.3 NORTH AMERICA
- 11.3.1 US
- 11.3.1.1 Growing demand from automotive sector to boost market
- 11.3.2 CANADA
- 11.3.2.1 Construction industry to boost demand for UV stabilizers
- 11.3.3 MEXICO
- 11.3.3.1 Growing automotive and construction sectors to support market growth
- 11.3.1 US
- 11.4 EUROPE
- 11.4.1 GERMANY
- 11.4.1.1 Growing demand from automotive industry to boost market
- 11.4.2 FRANCE
- 11.4.2.1 Increase in construction activities to drive market
- 11.4.3 SPAIN
- 11.4.3.1 Robust automotive and packaging sector to drive market
- 11.4.4 UK
- 11.4.4.1 Demand for architectural coating and flooring applications in construction industry to propel market
- 11.4.5 ITALY
- 11.4.5.1 Advanced polymer processing and sustainability requirements to shape demand
- 11.4.6 TURKEY
- 11.4.6.1 Expanding industrial applications to strengthen demand
- 11.4.1 GERMANY
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 UAE
- 11.5.1.1 Development of non-oil sectors to augment market growth
- 11.5.2 SAUDI ARABIA
- 11.5.2.1 Saudi Arabia Vision 2030 project to drive market
- 11.5.3 SOUTH AFRICA
- 11.5.3.1 High demand from packaging industry to drive market
- 11.5.1 UAE
- 11.6 SOUTH AMERICA
- 11.6.1 BRAZIL
- 11.6.1.1 Growing demand from packaging applications to boost market
- 11.6.1 BRAZIL
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN, 2020-2026
- 12.3 MARKET SHARE ANALYSIS, 2025
- 12.4 REVENUE ANALYSIS, 2023-2025
- 12.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.5.1 STARS
- 12.5.2 EMERGING LEADERS
- 12.5.3 PERVASIVE PLAYERS
- 12.5.4 PARTICIPANTS
- 12.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.5.5.1 Company footprint
- 12.5.5.2 Region footprint
- 12.5.5.3 Type footprint
- 12.5.5.4 Application footprint
- 12.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.6.1 PROGRESSIVE COMPANIES
- 12.6.2 RESPONSIVE COMPANIES
- 12.6.3 DYNAMIC COMPANIES
- 12.6.4 STARTING BLOCKS
- 12.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.6.5.1 Detailed list of key startups/SMES
- 12.6.5.2 Competitive benchmarking of key startups/SMEs
- 12.7 BRAND/PRODUCT COMPARISON
- 12.8 COMPANY VALUATION AND FINANCIAL METRICS
- 12.9 COMPETITIVE SCENARIO
- 12.9.1 PRODUCT LAUNCHES
- 12.9.2 DEALS
- 12.9.3 EXPANSIONS
- 12.9.4 OTHER DEVELOPMENTS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 BASF SE
- 13.1.1.1 Business overview
- 13.1.1.2 Products/Solutions/Services offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product launches
- 13.1.1.3.2 Expansions
- 13.1.1.4 Strategic intelligence
- 13.1.1.4.1 Position in market
- 13.1.1.4.2 Financial strategy
- 13.1.1.4.3 Operational strategy
- 13.1.1.4.4 Market expansion strategy
- 13.1.1.4.5 Product USP
- 13.1.1.5 MnM view
- 13.1.1.5.1 Key strengths
- 13.1.1.5.2 Strategic choices
- 13.1.1.5.3 Weaknesses and competitive threats
- 13.1.2 RIANLON CORPORATION
- 13.1.2.1 Business overview
- 13.1.2.2 Products/Solutions/Services offered
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Product launches
- 13.1.2.3.2 Expansions
- 13.1.2.3.3 Other developments
- 13.1.2.4 Strategic intelligence
- 13.1.2.4.1 Position in market
- 13.1.2.4.2 Financial strategy
- 13.1.2.4.3 Operational strategy
- 13.1.2.4.4 Market expansion strategy
- 13.1.2.4.5 Product USP
- 13.1.2.5 MnM view
- 13.1.2.5.1 Key strengths
- 13.1.2.5.2 Strategic choices
- 13.1.2.5.3 Weaknesses and competitive threats
- 13.1.3 ARKEMA
- 13.1.3.1 Business overview
- 13.1.3.2 Products/Solutions/Services offered
- 13.1.3.3 Strategic intelligence
- 13.1.3.3.1 Position in market
- 13.1.3.3.2 Financial strategy
- 13.1.3.3.3 Operational strategy
- 13.1.3.3.4 Market expansion strategy
- 13.1.3.3.5 Product USP
- 13.1.3.4 MnM view
- 13.1.3.4.1 Key strengths
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weaknesses and competitive threats
- 13.1.4 SUQIAN UNITECH CORP., LTD.
- 13.1.4.1 Business overview
- 13.1.4.2 Products/Solutions/Services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Expansions
- 13.1.4.4 Strategic intelligence
- 13.1.4.4.1 Position in market
- 13.1.4.4.2 Financial strategy
- 13.1.4.4.3 Operational strategy
- 13.1.4.4.4 Market expansion strategy
- 13.1.4.4.5 Product USP
- 13.1.4.5 MnM view
- 13.1.4.5.1 Key strengths
- 13.1.4.5.2 Strategic choices
- 13.1.4.5.3 Weaknesses and competitive threats
- 13.1.5 SYENSQO SA/NV
- 13.1.5.1 Business overview
- 13.1.5.2 Products/Solutions/Services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Product launches
- 13.1.5.4 Strategic intelligence
- 13.1.5.4.1 Position in market
- 13.1.5.4.2 Financial strategy
- 13.1.5.4.3 Operational strategy
- 13.1.5.4.4 Market expansion strategy
- 13.1.5.4.5 Product USP
- 13.1.5.5 MnM view
- 13.1.5.5.1 Key strengths
- 13.1.5.5.2 Strategic choices
- 13.1.5.5.3 Weaknesses and competitive threats
- 13.1.6 SONGWON INDUSTRIAL CO., LTD.
- 13.1.6.1 Business overview
- 13.1.6.2 Products/Solutions/Services offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Product launches
- 13.1.6.3.2 Deals
- 13.1.6.4 Strategic intelligence
- 13.1.6.4.1 Position in market
- 13.1.6.4.2 Financial strategy
- 13.1.6.4.3 Operational strategy
- 13.1.6.4.4 Market expansion strategy
- 13.1.6.4.5 Product USP
- 13.1.6.5 MnM view
- 13.1.6.5.1 Key strengths
- 13.1.6.5.2 Strategic choices
- 13.1.6.5.3 Weaknesses and competitive threats
- 13.1.7 ADEKA CORPORATION
- 13.1.7.1 Business overview
- 13.1.7.2 Products/Solutions/Services offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Product launches
- 13.1.7.4 Strategic intelligence
- 13.1.7.4.1 Position in market
- 13.1.7.4.2 Financial strategy
- 13.1.7.4.3 Operational strategy
- 13.1.7.4.4 Market expansion strategy
- 13.1.7.4.5 Product USP
- 13.1.8 SABO S.P.A.
- 13.1.8.1 Business overview
- 13.1.8.2 Products/Solutions/Services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Deals
- 13.1.8.3.2 Expansions
- 13.1.8.4 Strategic intelligence
- 13.1.8.4.1 Position in market
- 13.1.8.4.2 Financial strategy
- 13.1.8.4.3 Operational strategy
- 13.1.8.4.4 Market expansion strategy
- 13.1.8.4.5 Product USP
- 13.1.9 EVERLIGHT CHEMICAL INDUSTRIAL CORPORATION
- 13.1.9.1 Business overview
- 13.1.9.2 Products/Solutions/Services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Product launches
- 13.1.9.4 Strategic intelligence
- 13.1.9.4.1 Position in market
- 13.1.9.4.2 Financial strategy
- 13.1.9.4.3 Operational strategy
- 13.1.9.4.4 Market expansion strategy
- 13.1.9.4.5 Product USP
- 13.1.10 SI GROUP, INC.
- 13.1.10.1 Business overview
- 13.1.10.2 Products/Solutions/Services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Deals
- 13.1.10.4 Strategic intelligence
- 13.1.10.4.1 Position in market
- 13.1.10.4.2 Financial strategy
- 13.1.10.4.3 Operational strategy
- 13.1.10.4.4 Market expansion strategy
- 13.1.10.4.5 Product USP
- 13.1.11 CLARIANT AG
- 13.1.11.1 Business overview
- 13.1.11.2 Products/Solutions/Services offered
- 13.1.11.3 Recent developments
- 13.1.11.3.1 Product launches
- 13.1.11.3.2 Expansions
- 13.1.11.4 Strategic intelligence
- 13.1.11.4.1 Position in market
- 13.1.11.4.2 Financial strategy
- 13.1.11.4.3 Operational strategy
- 13.1.11.4.4 Market expansion strategy
- 13.1.11.4.5 Product USP
- 13.1.1 BASF SE
- 13.2 OTHER PLAYERS
- 13.2.1 MAYZO, INC.
- 13.2.2 ALTANA GROUP
- 13.2.3 3V SIGMA S.P.A.
- 13.2.4 LYCUS LTD., LLC
- 13.2.5 AMPACET CORPORATION
- 13.2.6 MILLIKEN & COMPANY
- 13.2.7 MPI CHEMIE BV
- 13.2.8 TINTOLL PERFORMANCE MATERIALS CO., LTD.
- 13.2.9 KNV CHEMICALS INC.
- 13.2.10 BEIJING TIANGANG AUXILIARY CO., LTD.
- 13.2.11 GREENCHEMICALS S.R.L.
- 13.2.12 PHOENIX PLASTICS
- 13.2.13 CHITEC TECHNOLOGY CO., LTD.
- 13.2.14 EVERSPRING CHEMICAL CO., LTD.
- 13.2.15 SUNSHOW SPECIALTY CHEMICAL CO., LTD.
- 13.2.16 VALTRIS SPECIALTY CHEMICALS
- 13.2.17 FUJIAN DISHENG TECHNOLOGY CO., LTD.
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH DATA
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Key data from primary sources
- 14.1.2.2 Primary interview participants
- 14.1.2.3 Breakdown of primary interviews
- 14.1.2.4 Key industry insights
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.2.1 BOTTOM-UP APPROACH
- 14.2.2 TOP-DOWN APPROACH
- 14.3 GROWTH FORECAST
- 14.3.1 SUPPLY SIDE
- 14.3.2 DEMAND SIDE
- 14.4 DATA TRIANGULATION
- 14.5 FACTOR ANALYSIS
- 14.6 RESEARCH ASSUMPTIONS
- 14.7 RESEARCH LIMITATIONS
- 14.8 RISK ASSESSMENT
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS


