

|
시장보고서
상품코드
2144542
암 진단 시장 예측(-2031년) : 제품, 기술, 유형, 용도, 최종사용자, 지역별Cancer Diagnostics Market by Product (Consumables (Antibodies, Probes), Instruments), Technology (IVD Testing, Anatomic pathology, Imaging, Biopsy), Type (Tumors, Breast, Lung Cancer), Application, End User (Hospitals) & Region - Global Forecast to 2031 |
||||||

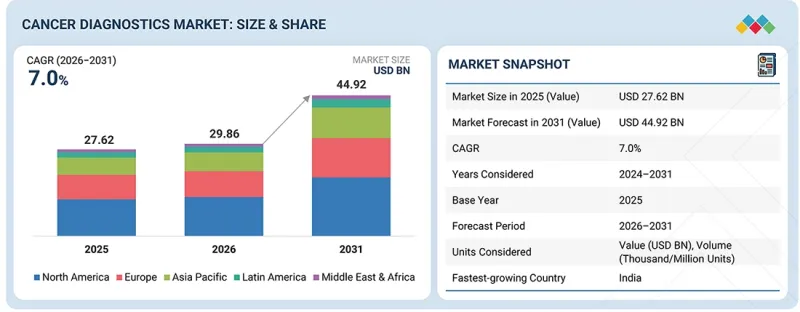
암 진단 시장은 2026년 298억 6,000만 달러에서 2031년까지 449억 2,000만 달러에 달할 것으로 예측되고 있으며, CAGR은 7.0%에 달할 전망입니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 제품, 방법, 기술, 용도, 최종사용자 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
암 진단은 암의 조기 발견, 정확한 진단, 질환의 특성 평가, 치료법 선택 및 지속적인 경과 관찰을 가능하게 함으로써 종양학 분야에서 매우 중요한 역할을 수행하고 있습니다. 제품별로 분류된 암 진단 시장은 체외진단(IVD),병리 진단, 그리고 영상 진단의 각 분야에서 사용되는 광범위한 기기 및 소모품 포트폴리오로 구성되어 있습니다. 시장의 성장은 첨단 진단 기술의 보급 확대, 소모품에 대한 지속적인 수요, 전 세계 암 발병률의 상승, 선별 검사 조치의 확대, 그리고 진단 검사 건수의 증가에 의해 주도되고 있습니다.
이 시장에는 PCR, 면역조직화학(IHC), 인 시투 하이브리다이제이션(ISH), 차세대 염기서열 분석(NGS), 마이크로어레이, 유세포분석법, 면역측정법, 조직병리학,생검, CT, MRI, PET, 유방촬영술, 초음파 검사 등 광범위한 진단 기술이 포함되어 있습니다. 이러한 기술들은 고형 종양 및 혈액 악성 종양 모두의 진단에 사용되며, 암 검진, 조기 발견, 질환의 진단 및 특성 평가, 치료 방침 결정, 재발 감지를 포함한 질환의 경과 관찰 등의 용도를 지원하고 있습니다.
제품별로 보면 암 진단 시장은 IVD 검사, 해부 병리학 및 영상 진단으로 구분됩니다. 이 중 IVD 검사가 가장 큰 시장 점유율을 차지하고 있으며, 예측 기간 중 가장 빠른 성장이 예상됩니다. 이 부문의 우위는 전 세계에서 증가하는 암 부담, 조기 발견 및 정밀 종양학에 대한 중요성 증대, 체액 생검 및 분자 진단 기술의 채택 확대, 그리고 암 선별 검사, 진단, 치료법 선택 및 질환 모니터링에서 바이오마커 기반 검사의 활용 확대에 의해 주도되고 있습니다. 차세대 염기서열 분석(NGS), 중합효소 연쇄 반응(PCR), 면역 분석법, 동반 진단, 그리고 AI를 활용한 진단 플랫폼의 지속적인 발전으로 인해 진단의 정확도, 민감도 및 결과 보고까지의 시간이 크게 개선되었습니다. 의료 투자 증가, 분자 검사에 대한 유리한 보험 환급, 정부 주도의 암 검진 구상, 그리고 맞춤형 의료에 대한 접근성 확대에 힘입어, IVD 검사 부문은 예측 기간 중 전 세계 암 진단 시장에서 주도적인 위치를 유지할 것으로 예상됩니다.
최종사용자별로 보면 암 진단 시장은 병원과 임상 검사실로 구분됩니다. 이 중 병원은 환자 수가 많고 포괄적인 진단 인프라를 갖추고 있으며, 단일 시설 내에서 선별 검사, 진단, 치료 계획, 질환 모니터링을 아우르는 통합적인 암 의료 서비스를 제공할 수 있으므로 가장 큰 시장 점유율을 차지하고 있습니다. 병원은 첨단 영상 진단, 생검 시술, 분자 검사 및 다학제적 협력을 통한 종양 치료의 주요 거점으로서, 암 진단 서비스에 대한 큰 수요를 주도하고 있습니다. 정밀 종양학, 컴패니언 진단, 차세대 염기서열 분석(NGS), AI를 활용한 진단 워크플로우의 도입 확대에 더해, 병원내 암 센터에 대한 투자 증가와 첨단 진단 기술에 대한 접근성 확대가 맞물리면서 병원 부문의 우위는 계속해서 강화되고 있습니다. 또한 암 검진을 위한 정부 주도의 노력 확대, 암 환자 입원 건수 증가, 그리고 디지털 병리학 및 검사 정보 시스템의 통합이 전 세계 암 진단 시장에서 병원의 주도적 지위를 강화하고 있습니다. 한편, 임상 검사실은 전문적인 분자 검사 및 게놈 검사의 아웃소싱 증가에 힘입어 꾸준한 성장을 이어가고 있습니다.
지역별로 보면 암 진단 시장은 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카로 분류됩니다. 북미는 2025년에 가장 큰 시장 점유율을 차지할 것으로 예상되며, 첨단인 의료 인프라, 높은 의료비 지출, 유리한 환급 정책, 그리고 혁신적인 암 진단 기술의 조기 도입에 힘입어 계속해서 주요 시장 견인차 역할을 수행하고 있습니다. 이 지역은 암 유병률이 높고, 확립된 선별 검사 프로그램이 있으며, 조기 발견 및 정밀 종양학에 대한 수요가 증가하고 있으며, 병원, 암 센터, 임상 검사실에서 분자 진단, 차세대 염기서열 분석(NGS),액체생검, 동반 진단, 디지털 병리학, 그리고 첨단 영상 진단 기술이 널리 채택되고 있습니다. 주요 진단 기업의 강력한 입지, 지속적인 기술 발전, 암 연구에 대한 막대한 투자, 지원적인 규제 체계, 그리고 암 진단에 인공지능(AI)의 통합 확대가 북미 시장의 리더십을 더욱 공고히 하고 있습니다.
이 보고서에서 언급된 암 진단 시장의 주요 응답자(공급 측) 구성은 다음과 같습니다. :
- 기업 유형별: Tier 1: 40%, Tier 2: 30%, Tier 3: 30%
- 직책별: C레벨: 55%, 이사급: 27%, 기타: 18%
- 지역별: 북미: 43%, 유럽: 28%, 아시아태평양: 20%, 라틴아메리카: 6%, 중동 및 아프리카: 3%
조사 범위
이 보고서에서는 암 진단 시장을 평가하고, 제품, 최종사용자, 지역 등 다양한 부문를 기반으로 시장 규모 및 향후 성장 가능성을 추정하고 있습니다. 또한 해당 시장의 주요 기업에 대한 경쟁 분석과 더불어 기업 개요, 제품 라인업, 최근 동향 및 주요 시장 전략에 대해서도 다루고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 암 진단 시장의 시장 선도 기업 및 신규 진입 기업에게 시장 전체 및 그 하위 부문의 매출에 관한 가장 정확한 추정치를 제공합니다. 또한 이해관계자가 경쟁 구도를 이해하고, 자사의 사업을 적절히 포지셔닝하며, 효과적인 시장 진입 전략을 수립하는 데 필요한 인사이트를 얻는 데 도움이 됩니다. 더불어 이해관계자가 시장 역학을 이해할 수 있도록 지원하는 동시에, 암 진단 시장에 영향을 미치는 주요 시장 촉진요인, 제약, 과제 및 성장 기회에 대한 인사이트를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 주요 촉진요인 분석(고령화, 라이프스타일 변화, 환경적 위험 요인으로 인한 전 세계 암 부담 증가; 환자 예후 및 생존율 개선을 위한 조기 암 발견 및 선별 검사에 대한 관심 증가; 분자 진단, 차세대 염기서열 분석(NGS),액체생검, 동반 진단의 발전으로 인한 정밀 종양학의 실현; 진단 정확도와 워크플로우 효율화를 위한 AI 기반 영상 진단 및 디지털 병리 솔루션 도입 확대; 암 연구, 바이오마커 발견 및 맞춤형 의료에 대한 투자 증가), 억제요인(첨단 진단 기술 및 게놈 검사의 높은 비용; 저·중소득 국가에서의 첨단 진단 인프라 접근 제한; 엄격한 규제 승인 및 보험 급여와 관련된 과제; 전문적인 지식이 필요한 유전체 및 분자 데이터 해석의 복잡성),기회(액체생검 등 비침습적 진단 기술에 대한 수요 증가; 전국적인 암 검진 프로그램 및 인식 제고 활동의 확대; 정밀 의료 및 동반 진단의 보급 확대; AI를 활용한 진단, 디지털 병리학, 다중 암 조기 검출(MCED) 검사에 대한 투자 증가; 신흥 시장의 의료 인프라 및 진단 역량 향상),및 과제(숙련된 종양학 및 병리학 전문가 부족; 데이터 개인정보 보호,상호 운용성 및 디지털 진단 플랫폼과의 통합 관련 문제; 신규 바이오마커 및 진단 분석법에 대한 엄격한 검증 요건; 의료제도별 보상 기준의 편차; 합리적인 가격과 진단 정확도를 유지하면서 첨단 암 진단에 대한 공평한 접근 보장).
- 제품 강화 및 혁신: 암 진단 시장에서의 신제품 출시 및 예상되는 동향에 대한 포괄적인 상세 정보.
- 시장 개발: 제품, 유형, 용도, 기술, 최종사용자, 지역별로 수익성이 높은 성장 시장에 대한 심층적인 인사이트와 분석.
- 시장 다각화: 암 진단 시장내 신제품 출시, 시장 확대, 최신 동향 및 투자에 관한 포괄적인 정보.
- 경쟁 평가: 암 진단 시장의 주요 경쟁사들의 시장 점유율, 성장 계획, 제공 제품 및 생산 능력에 대한 철저한 평가.
자주 묻는 질문
목차
제1장. 서론
제2장 요약
제3장 주요 인사이트
- 암 진단 시장의 개요
- 아시아태평양의 암 진단 시장: 국가별·기술별
- 암 진단 시장: 지역별 성장 전망(2026-2031년)
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요와 미개발 분야
- 암 진단 시장의 미충족 수요
- 미개발 시장의 기회
- 상호 연관된 시장과 부문 간 기회
- 상호 연관된 시장
- Tier 1/2/3 주요 기업의 전략적 움직임
- 주요 동향 및 전략적 초점
제5장 업계 동향
- Porter's Five Forces 분석
- 공급업체의 협상력
- 구매자의 협상력
- 신규 진입자의 위협
- 대체품의 위협
- 경쟁 기업 간의 적대적 관계
- 거시경제 지표
- GDP 동향 및 전망
- 공급망 분석
- 생태계 분석
- 투자 및 자금 조달 시나리오
- 가격 책정 분석
- 제품별 평균 판매 가격
- 주요 기업별 혈당 측정용 테스트 스트립의 평균 판매 가격
- 지역별 평균 판매 가격
- 밸류체인 분석
- 고객의 사업에 영향을 미치는 동향/변화
- 사례 연구 분석
- 가격 영향 분석
- 지역에 미치는 영향
제6장 기술의 진보, AI의 영향, 특허, 혁신 및 향후 응용
- 주요 신규 기술
- 체외진단(IVD) 검사
- 보완 기술
- 인접 기술
- 기술·제품 로드맵
- 특허 분석
- 주요 특허 리스트
- 미래 응용
- AI/생성형 AI가 암 진단 시장에 미치는 영향
- 주요 활용 사례 및 시장 잠재력
- AI를 도입한 주요 기업
- AI의 미래
제7장 규제 현황과 지속가능성
- 지역별 규제 및 규정 준수
- 규제기관, 정부 기관 및 기타 조직
- 업계 표준
- 지속가능성을 위한 노력
- 암 진단이 환경에 미치는 영향 및 환경 배려 노력
- 지속가능성에 미치는 영향 및 규제 정책 관련 노력
제8장 고객 동향과 구매 행동
- 의사결정 과정
- 구매자의 이해관계자와 구매 평가 기준
- 구매 과정에서 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 다양한 최종사용자의 충족되지 않은 요구
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 주요 용도에서의 이익률 향상 기회
제9장 암 진단 시장: 용도별
- 선별 검사 및 조기 발견
- 진단 및 질환 특성 평가
- 치료 결정 지원
- 치료 모니터링 및 질병 진행 평가
- 치료 후 경과 관찰 및 재발 감지
제10장 암 진단 시장: 기술별
- IVD 검사
- 영상 진단 기술
- 해부 병리학
- 생검
제11장 암 진단 시장: 유형별
- 고형 종양
- 유방암
- 폐암
- 대장암
- 위암
- 두경부암
- 전립선암
- 자궁경부암
- 악성 흑색종
- 체액성 종양
- 백혈병
- 골수종
- 림프종
제12장 암 진단 시장: 제품별
- IVD 검사
- 병리 진단
- 영상 진단 기반
제13장 암 진단 시장: 최종사용자별
- 병원·진료소
- 진단 실험실
제14장 암 진단 시장: 지역별
- 북미
- 미국
- 캐나다
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 호주
- 기타 아시아태평양
- 라틴아메리카
- 브라질
- 멕시코
- 기타 라틴아메리카
- 중동 및 아프리카
제15장 경쟁 현황
- 주요 진입 기업의 전략/강점
- 암 진단 시장내 주요 기업의 전략 개요
- 수익 분석(2023-2025년)
- 시장 점유율 분석(2025년)
- 기업 평가 및 재무 지표
- 브랜드/제품 비교
- ABBOTT
- F. HOFFMANN-LA ROCHE LTD.
- DANAHER
- 기업 평가 매트릭스: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2023년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 주요 스타트업/중소기업의 상세 리스트
- 스타트업/중소기업의 경쟁 벤치마킹
- 경쟁 시나리오
- 제품 출시 및 승인
제16장 기업 개요
- 주요 기업
- F. HOFFMANN-LA ROCHE
- DANAHER CORPORATION
- THERMO FISHER SCIENTIFIC INC
- ABBOTT LABORATORIES
- AGILENT TECHNOLOGIES INC.
- QIAGEN N.V.
- ILLUMINA, INC
- HOLOGIC, INC
- BECTON, DICKINSON AND COMPANY
- SIEMENS HEALTHINEERS AG
- EXACT SCIENCES CORPORATION
- GUARDANT HEALTH, INC
- SYSMEX CORPORATION
- BIOMERIEUX SA.
- MYRIAD GENETICS, INC
- 기타 기업
- NEOGENOMICS, INC
- NATERA, INC
- TEMPUS AI, INC
- GRAIL, INC
- CARIS LIFE SCIENCES, INC, INC.
- PERSONALIS, INC
- DELFI DIAGNOSTICS, INC
- FULGENT GENETICS, INC
- BURNING ROCK BIOTECH LIMITED
- GENETRON HOLDINGS LIMITED
제17장 조사 방법
제18장 부록
KSA 26.10.15The cancer diagnostics market is projected to reach USD 44.92 billion by 2031 from USD 29.86 billion in 2026, registering a CAGR of 7.0%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Product, Method, Technology, Application, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, and Middle East & Africa |
Cancer diagnostics play a critical role in oncology by enabling early detection, accurate diagnosis, disease characterization, treatment selection, and ongoing monitoring of cancer. The cancer diagnostics market, segmented by product, comprises a broad portfolio of instruments and consumables used across in vitro diagnostics (IVD), anatomic pathology, and imaging-based diagnostics. Market growth is driven by the increasing adoption of advanced diagnostic technologies, sustained demand for consumables, rising global cancer incidence, expanding screening initiatives, and growing diagnostic testing volumes.
The market encompasses a wide range of diagnostic technologies, including PCR, immunohistochemistry (IHC), in situ hybridization (ISH), next-generation sequencing (NGS), microarrays, flow cytometry, immunoassays, histopathology, biopsy, CT, MRI, PET, mammography, and ultrasound. These technologies are used to diagnose both solid tumors and hematological malignancies, supporting applications such as cancer screening, early detection, disease diagnosis and characterization, treatment decision-making, and disease monitoring, including recurrence detection.
Based on product, the cancer diagnostics market is segmented into IVD testing, anatomic pathology, and imaging-based diagnostics. Among these, IVD testing accounted for the largest market share and is projected to witness the fastest growth during the forecast period. The segment's dominance is driven by the increasing global burden of cancer, growing emphasis on early detection and precision oncology, rising adoption of liquid biopsy and molecular diagnostic technologies, and expanding use of biomarker-based testing for cancer screening, diagnosis, treatment selection, and disease monitoring. Continuous advancements in next-generation sequencing (NGS), polymerase chain reaction (PCR), immunoassays, companion diagnostics, and AI-enabled diagnostic platforms have significantly enhanced diagnostic accuracy, sensitivity, and turnaround time. Supported by increasing healthcare investments, favorable reimbursement for molecular testing, government-led cancer screening initiatives, and expanding access to personalized medicine, the IVD testing segment is expected to maintain its leading position in the global cancer diagnostics market throughout the forecast period.
Based on end user, the cancer diagnostics market is segmented into hospitals and clinical laboratories. Among these, hospitals account for the largest market share due to their high patient volumes, comprehensive diagnostic infrastructure, and ability to provide integrated cancer care encompassing screening, diagnosis, treatment planning, and disease monitoring under a single setting. Hospitals are the primary centers for advanced imaging, biopsy procedures, molecular testing, and multidisciplinary oncology care, driving significant demand for cancer diagnostic services. The increasing adoption of precision oncology, companion diagnostics, next-generation sequencing (NGS), and AI-enabled diagnostic workflows, coupled with rising investments in hospital-based cancer centers and expanding access to advanced diagnostic technologies, continues to strengthen the dominance of the hospital segment. Furthermore, growing government initiatives for cancer screening, increasing cancer admissions, and the integration of digital pathology and laboratory information systems are reinforcing the leading position of hospitals in the global cancer diagnostics market, while clinical laboratories continue to witness steady growth driven by increasing outsourcing of specialized molecular and genomic testing.
Based on region, the cancer diagnostics market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America accounted for the largest market share in 2025 and continues to serve as the primary market driver, supported by its advanced healthcare infrastructure, high healthcare expenditure, favorable reimbursement policies, and early adoption of innovative cancer diagnostic technologies. The region has a high prevalence of cancer, well-established screening programs, and increasing demand for early detection and precision oncology, resulting in the widespread adoption of molecular diagnostics, next-generation sequencing (NGS), liquid biopsy, companion diagnostics, digital pathology, and advanced imaging technologies across hospitals, cancer centers, and clinical laboratories. The strong presence of leading diagnostics companies, continuous technological advancements, substantial investments in oncology research, supportive regulatory frameworks, and expanding integration of artificial intelligence into cancer diagnostics further reinforce North America's market leadership.
A breakdown of the primary respondents (supply-side) for the cancer diagnostics market referred to in this report is provided below:
- By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
- By Designation: C-level: 55%, Director Level: 27%, and Others: 18%
- By Region: North America: 43%, Europe: 28%, Asia Pacific: 20%, Latin America: 6% and Middle East & Africa: 3%
Prominent players in the cancer diagnostics market include Roche Diagnostics (Switzerland), Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Abbott Laboratories (US), Siemens Healthineers AG (Germany), Agilent Technologies, Inc. (US), QIAGEN N.V. (Netherlands), Illumina, Inc. (US), Hologic, Inc. (US), Becton, Dickinson and Company (US), Exact Sciences Corporation (US), Guardant Health, Inc. (US), Sysmex Corporation (Japan), Foundation Medicine, Inc. (US), Myriad Genetics, Inc. (US), NeoGenomics Laboratories, Inc. (US), bioMerieux SA (France), and Revvity, Inc. (US), among others.
Research Coverage
The report evaluates the cancer diagnostics market and estimates the market size and future growth potential of this market based on various segments, including product, end user, and region. The report also includes a competitive analysis of the major players in this market, along with company profiles, product offerings, recent developments, and key market strategies.
Reasons to Buy the Report
The report will assist market leaders and new entrants in the cancer diagnostics s market with data on the nearest approximations of revenue figures for the overall market and its subsegments. The report will help stakeholders understand the competitive landscape and gain insights into better positioning their businesses and developing effective go-to-market strategies. It also enables stakeholders to understand market dynamics and provides insights into key drivers, restraints, challenges, and growth opportunities influencing the cancer diagnostics market.
This report provides insights into the following points:
- Analysis of Key Drivers (Increasing global burden of cancer driven by aging populations, lifestyle changes, and environmental risk factors; Growing emphasis on early cancer detection and screening to improve patient outcomes and survival rates; Advancements in molecular diagnostics, next-generation sequencing (NGS), liquid biopsy, and companion diagnostics enabling precision oncology; Rising adoption of AI-powered imaging and digital pathology solutions to enhance diagnostic accuracy and workflow efficiency; Increasing investments in cancer research, biomarker discovery, and personalized medicine), restraints (High cost of advanced diagnostic technologies and genomic testing; Limited accessibility to sophisticated diagnostic infrastructure in low- and middle-income countries; Stringent regulatory approval and reimbursement challenges; Complexity in interpreting genomic and molecular data requiring specialized expertise), opportunities (Growing demand for non-invasive diagnostic techniques such as liquid biopsy; Expansion of national cancer screening programs and awareness initiatives; Increasing adoption of precision medicine and companion diagnostics; Rising investments in AI-enabled diagnostics, digital pathology, and multi-cancer early detection (MCED) tests; Growing healthcare infrastructure and diagnostic capabilities in emerging markets), and challenges (Shortage of skilled oncology and pathology professionals; Data privacy, interoperability, and integration issues with digital diagnostic platforms; High validation requirements for novel biomarkers and diagnostic assays; Reimbursement variability across different healthcare systems; Ensuring equitable access to advanced cancer diagnostics while maintaining affordability and diagnostic accuracy).
- Product Enhancement/Innovation: Comprehensive details about product launches and anticipated trends in the cancer diagnostics market.
- Market Development: Thorough knowledge and analysis of the profitable rising markets by product, type, application, technology, end user, and region.
- Market Diversification: Comprehensive information about newly launched products, expanding markets, current advancements, and investments in the cancer diagnostics market.
- Competitive Assessment: Thorough evaluation of the market shares, growth plans, offerings, and capacities of the major competitors in the cancer diagnostics market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET
- 2.4 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 CANCER DIAGNOSTICS MARKET OVERVIEW
- 3.2 ASIA PACIFIC CANCER DIAGNOSTICS MARKET, BY COUNTRY AND TECHNOLOGY
- 3.3 CANCER DIAGNOSTICS MARKET: GEOGRAPHIC GROWTH (2026-2031)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing incidence of cancer
- 4.2.1.2 Growth in number of private diagnostics centers
- 4.2.1.3 Availability of favorable reimbursement policies
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital investment requirements
- 4.2.2.2 High cost of advanced diagnostic imaging systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing adoption of companion diagnostics
- 4.2.3.2 Expansion of organized cancer screening programs
- 4.2.3.3 Growing demand for cancer diagnostics in emerging markets
- 4.2.4 CHALLENGES
- 4.2.4.1 Increasing adoption of refurbished diagnostic imaging systems
- 4.2.4.2 Shortage of skilled professionals
- 4.2.4.3 Limited healthcare infrastructure and low awareness in developing countries
- 4.2.4.4 Product recalls and diagnostic test failures
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN CANCER DIAGNOSTICS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF NEW ENTRANTS
- 5.1.4 THREAT OF SUBSTITUTES
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 INVESTMENT AND FUNDING SCENARIO
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE BY PRODUCT
- 5.6.2 AVERAGE SELLING PRICE OF GLUCOSE MONITORING TEST STRIPS, BY KEY PLAYER
- 5.6.3 AVERAGE SELLING PRICE, BY REGION
- 5.6.3.1 Average selling price of glucose monitoring test strips, by region
- 5.6.3.2 Average selling price of infectious disease testing products, by region
- 5.6.3.3 Average selling price of cardiometabolic monitoring products, by region
- 5.7 VALUE CHAIN ANALYSIS
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 PRICE IMPACT ANALYSIS
- 5.9.2 IMPACT ON REGION
- 5.9.2.1 North America
- 5.9.2.2 Europe
- 5.9.2.3 Asia Pacific
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 IVD TESTING
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Molecular diagnostics
- 6.1.3 ADJACENT TECHNOLOGIES
- 6.1.3.1 Biochemical technologies
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.3 PATENT ANALYSIS
- 6.3.1 LIST OF MAJOR PATENTS
- 6.4 FUTURE APPLICATIONS
- 6.5 IMPACT OF AI/GENERATIVE AI ON CANCER DIAGNOSTICS MARKET
- 6.5.1 INTRODUCTION
- 6.5.2 TOP USE CASES AND MARKET POTENTIAL
- 6.5.3 KEY COMPANIES IMPLEMENTING AI
- 6.5.4 FUTURE OF AI
7 REGULATORY LANDSCAPE AND SUSTAINABILITY
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 ENVIRONMENTAL IMPACT AND ECO-FRIENDLY INITIATIVES IN CANCER DIAGNOSTICS
- 7.2.1.1 Eco-friendly Initiatives
- 7.2.1 ENVIRONMENTAL IMPACT AND ECO-FRIENDLY INITIATIVES IN CANCER DIAGNOSTICS
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END USERS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 CANCER DIAGNOSTICS MARKET, BY APPLICATION
- 9.1 INTRODUCTION
- 9.2 SCREENING & EARLY DETECTION
- 9.2.1 INCREASING EMPHASIS ON EARLY CANCER DETECTION TO DRIVE SEGMENT
- 9.3 DIAGNOSIS & DISEASE CHARACTERIZATION
- 9.3.1 GOVERNMENT INITIATIVES TO EXPAND HEALTHCARE ACCESS TO DRIVE SEGMENT
- 9.4 TREATMENT DECISION SUPPORT
- 9.4.1 RISING DEMAND FOR PRECISION ONCOLOGY TO PROPEL SEGMENT
- 9.5 TREATMENT MONITORING & DISEASE PROGRESSION ASSESSMENT
- 9.5.1 INCREASING DEMAND FOR DETECTION OF DISEASE PROGRESSION SUPPORT SEGMENT GROWTH
- 9.6 POST-TREATMENT SURVEILLANCE & RECURRENCE DETECTION
- 9.6.1 GROWING EMPHASIS ON POST-TREATMENT MONITORING TO DRIVE SEGMENT
10 CANCER DIAGNOSTICS MARKET, BY TECHNOLOGY
- 10.1 INTRODUCTION
- 10.2 IVD TESTING
- 10.2.1 POLYMERASE CHAIN REACTION
- 10.2.1.1 PCR-based diagnostic tests preferred as they provide simple representations of genomic data
- 10.2.2 IN SITU HYBRIDIZATION
- 10.2.2.1 ISH used for identification of specific mRNA species within sample cells
- 10.2.3 IMMUNOHISTOCHEMISTRY
- 10.2.3.1 Increasing use of IHC tests for cancer diagnostics to boost market growth
- 10.2.4 NEXT-GENERATION SEQUENCING
- 10.2.4.1 NGS dominates IVD testing market
- 10.2.5 IMMUNOASSAY
- 10.2.5.1 Immunoassay segment accounted for second-largest share of cancer diagnostics market for IVD testing
- 10.2.6 MICROARRAY
- 10.2.6.1 Cost-effectiveness of microarray technology to support market growth
- 10.2.7 FLOW CYTOMETRY
- 10.2.7.1 Limited budgets restrain segment growth
- 10.2.8 OTHER IVD TECHNOLOGIES
- 10.2.1 POLYMERASE CHAIN REACTION
- 10.3 IMAGING TECHNOLOGIES
- 10.3.1 MAGNETIC RESONANCE IMAGING
- 10.3.1.1 Technological advancements to boost segment growth
- 10.3.2 COMPUTED TOMOGRAPHY
- 10.3.2.1 CT is widely used technique in cancer diagnostics
- 10.3.3 POSITRON EMISSION TOMOGRAPHY (PET)
- 10.3.3.1 Widely used nuclear imaging technique in cancer diagnostics
- 10.3.4 MAMMOGRAPHY
- 10.3.4.1 Increasing government initiatives for breast cancer screening to drive segment growth
- 10.3.5 ULTRASOUND
- 10.3.5.1 Substantial clinical advancements and technical innovations to support market growth
- 10.3.1 MAGNETIC RESONANCE IMAGING
- 10.4 ANATOMIC PATHOLOGY
- 10.4.1 INTRODUCTION
- 10.4.1.1 Histopathology
- 10.4.1.1.1 Growing demand for high-throughput, error-free staining to drive market
- 10.4.1.2 Cytopathology
- 10.4.1.2.1 Rising cervical cancer screening volumes to boost demand for automated cytology systems
- 10.4.1.1 Histopathology
- 10.4.1 INTRODUCTION
- 10.5 BIOPSIES
11 CANCER DIAGNOSTICS MARKET, BY TYPE
- 11.1 INTRODUCTION
- 11.2 SOLID TUMORS
- 11.3 BREAST CANCER
- 11.3.1 SEGMENT TO ACCOUNT FOR LARGEST SHARE DURING FORECAST PERIOD
- 11.4 LUNG CANCER
- 11.4.1 LUNG CANCER SEGMENT ACCOUNTED FOR THE SECOND-LARGEST SHARE
- 11.5 COLORECTAL CANCER
- 11.5.1 INCREASING INCIDENCE OF COLORECTAL CANCER TO DRIVE MARKET GROWTH
- 11.6 GASTRIC CANCER
- 11.6.1 SEGMENT GROWTH SUPPORTED BY INCREASING ADOPTION OF BIOMARKER-BASED TESTING FOR TREATMENT SELECTION
- 11.7 HEAD & NECK CANCER
- 11.7.1 SEGMENT TO BE DRIVEN BY INCREASING AGING POPULATION
- 11.8 PROSTATE CANCER
- 11.8.1 RISING GLOBAL DISEASE BURDEN AND EVOLVING DIAGNOSTIC LANDSCAPE TO BOOST SEGMENT
- 11.9 CERVICAL CANCER
- 11.9.1 INCREASE IN SCREENING, HPV TESTING, AND BIOMARKER ADOPTION TO DRIVE MARKET GROWTH
- 11.10 MELANOMA
- 11.10.1 INCREASING INCIDENCE OF MELANOMA TO DRIVE MARKET GROWTH
- 11.10.2 OTHER SOLID TUMORS
- 11.11 LIQUID TUMORS
- 11.12 LEUKEMIA
- 11.12.1 SEGMENT CONTINUES TO REPRESENT SIGNIFICANT SHARE OF GLOBAL HEMATOLOGIC (LIQUID) CANCER BURDEN
- 11.13 MYELOMA
- 11.13.1 RISING CASES, PARTICULARLY ACROSS ASIA AND AFRICA, TO DRIVE MARKET
- 11.14 LYMPHOMA
- 11.14.1 INCREASING DISEASE BURDEN TO DRIVE SEGMENT
12 CANCER DIAGNOSTICS MARKET, BY PRODUCT
- 12.1 INTRODUCTION
- 12.2 IVD TESTING
- 12.2.1 KITS & REAGENTS
- 12.2.1.1 Increasing adoption due to ease of use to boost segment
- 12.2.2 INSTRUMENTS
- 12.2.2.1 PCR instruments
- 12.2.2.1.1 Cost-effectiveness drives growth of segment
- 12.2.2.2 NGS instruments
- 12.2.2.2.1 NGS is an emerging technology for cancer diagnostics
- 12.2.2.3 Microarrays
- 12.2.2.3.1 Use in determination of primary sites in metastatic carcinomas to boost market
- 12.2.2.1 PCR instruments
- 12.2.3 IN SITU HYBRIDIZATION
- 12.2.3.1 Use for identification of specific mRNA species within sample cells - key driver
- 12.2.4 IMMUNOHISTOCHEMISTRY
- 12.2.4.1 Increasing use of IHC tests for cancer diagnostics to boost market growth
- 12.2.5 IMMUNOASSAY
- 12.2.5.1 Segment holds second-largest share of cancer diagnostics market for IVD testing
- 12.2.6 FLOW CYTOMETRY
- 12.2.6.1 Use across diagnosis, monitoring, and treatment to propel market
- 12.2.7 OTHER IVD TESTING INSTRUMENTS
- 12.2.1 KITS & REAGENTS
- 12.3 ANATOMIC PATHOLOGY
- 12.3.1 INTRODUCTION
- 12.3.2 INSTRUMENTS
- 12.3.2.1 Slide staining systems
- 12.3.2.1.1 Increasing focus on automation to drive market
- 12.3.2.2 Tissue processing systems
- 12.3.2.2.1 Use in automatic processing of tissue samples to boost market
- 12.3.2.3 Cell processors
- 12.3.2.3.1 Used to remove unwanted matter from cytology samples
- 12.3.2.4 Microtomes
- 12.3.2.4.1 Segment gaining traction as rising biopsy volumes and automation drive demand
- 12.3.2.5 Embedding systems
- 12.3.2.5.1 Automated tissue embedding gains momentum in cancer diagnostics
- 12.3.2.6 Cover slippers
- 12.3.2.6.1 Automated cover slippers strengthen workflow efficiency in cancer diagnostics
- 12.3.2.7 Digital pathology scanners
- 12.3.2.7.1 Shift toward automated cancer diagnostics to accelerate segment growth
- 12.3.2.8 Other anatomic pathology instruments
- 12.3.2.1 Slide staining systems
- 12.3.3 CONSUMABLES
- 12.3.3.1 Antibodies
- 12.3.3.1.1 Cancer diagnostic consumables market
- 12.3.3.2 Kits & Reagents
- 12.3.3.2.1 Use of kits is increasing among end users owing to their ease of use
- 12.3.3.3 Probes
- 12.3.3.3.1 Probes Enable Precise Molecular Detection in Cancer Diagnostics
- 12.3.3.4 Other consumables
- 12.3.3.1 Antibodies
- 12.4 IMAGING-BASED
- 12.4.1 INSTRUMENTS
- 12.4.1.1 CT systems
- 12.4.1.1.1 Technological advancements to drive growth of segment
- 12.4.1.2 Ultrasound systems
- 12.4.1.2.1 Increasing incidence of cancer to drive segment growth
- 12.4.1.1 CT systems
- 12.4.2 MRI SYSTEMS
- 12.4.2.1 Rising cancer incidence and growing adoption of MRI drive market growth
- 12.4.2.2 Mammography systems
- 12.4.2.2.1 Increasing incidence of breast cancer to drive growth of segment
- 12.4.2.3 PET-CT
- 12.4.2.3.1 Technological advancements in nuclear imaging systems to drive segment
- 12.4.3 CONSUMABLES
- 12.4.3.1 Contrast agents
- 12.4.3.1.1 Increasing incidence of cancer to drive segment
- 12.4.3.2 Radiopharmaceuticals
- 12.4.3.2.1 Increasing availability of radioisotopes to drive segment
- 12.4.3.1 Contrast agents
- 12.4.1 INSTRUMENTS
13 CANCER DIAGNOSTICS MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 HOSPITALS & CLINICS
- 13.2.1 SEGMENT IS LARGEST END USER OF CANCER DIAGNOSTIC PRODUCTS
- 13.3 DIAGNOSTIC LABORATORIES
- 13.3.1 INCREASING INCIDENCE OF CANCER TO DRIVE GROWTH
14 CANCER DIAGNOSTICS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Expected to be dominant in North American market
- 14.2.2 CANADA
- 14.2.2.1 High cancer burden, aging population, and expanding screening programs to support market growth
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Availability of reimbursements for colorectal cancer screening to drive market growth
- 14.3.2 UK
- 14.3.2.1 Favorable government initiatives to drive market growth
- 14.3.3 FRANCE
- 14.3.3.1 Increasing government funding for cancer diagnosis and prevention to support market growth
- 14.3.4 ITALY
- 14.3.4.1 High incidence of cancer to support market growth
- 14.3.5 SPAIN
- 14.3.5.1 High incidence of chronic diseases to drive market growth
- 14.3.6 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Increasing healthcare expenditure to drive market growth
- 14.4.2 JAPAN
- 14.4.2.1 Advanced healthcare infrastructure to support market growth
- 14.4.3 INDIA
- 14.4.3.1 Expanding healthcare sector in country to drive market growth
- 14.4.4 SOUTH KOREA
- 14.4.4.1 Focus on genomic research and precision medicine to boost market growth
- 14.4.5 AUSTRALIA
- 14.4.6 REST OF ASIA PACIFIC
- 14.4.7 LATIN AMERICA
- 14.4.7.1 Increasing number of cancer screening programs to support market growth
- 14.4.8 BRAZIL
- 14.4.8.1 Expansion of cancer screening programs to support market growth
- 14.4.9 MEXICO
- 14.4.9.1 Increasing cancer screening initiatives and diagnostic infrastructure to drive market growth
- 14.4.10 REST OF LATIN AMERICA
- 14.4.11 MIDDLE EAST & AFRICA
- 14.4.11.1 Increasing incidence of cancer to drive market growth
- 14.4.1 CHINA
15 COMPETITIVE LANDSCAPE
- 15.1 INTRODUCTION
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY PLAYERS IN CANCER DIAGNOSTICS MARKET
- 15.3 REVENUE ANALYSIS, 2023-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY VALUATION AND FINANCIAL METRICS
- 15.6 BRAND/PRODUCT COMPARISON
- 15.6.1 ABBOTT
- 15.6.2 F. HOFFMANN-LA ROCHE LTD.
- 15.6.3 DANAHER
- 15.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.7.1 STARS
- 15.7.2 EMERGING LEADERS
- 15.7.3 PERVASIVE PLAYERS
- 15.7.4 PARTICIPANTS
- 15.7.5 COMPANY FOOTPRINT, KEY PLAYERS, 2025
- 15.7.5.1 Company footprint
- 15.7.5.2 Region footprint
- 15.7.5.3 End user footprint
- 15.7.5.4 Product footprint
- 15.7.5.5 Technology footprint
- 15.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2023
- 15.8.1 PROGRESSIVE COMPANIES
- 15.8.2 RESPONSIVE COMPANIES
- 15.8.3 DYNAMIC COMPANIES
- 15.8.4 STARTING BLOCKS
- 15.9 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.9.1 DETAILED LIST OF KEY STARTUPS/SMES
- 15.9.2 COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- 15.10 COMPETITIVE SCENARIO
- 15.10.1 PRODUCT LAUNCHES AND APPROVALS
16 COMPANY PROFILE
- 16.1 KEY PLAYERS
- 16.1.1 F. HOFFMANN-LA ROCHE
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches and approvals
- 16.1.1.3.2 Deals
- 16.1.1.3.3 Expansions
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 DANAHER CORPORATION
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches and approvals
- 16.1.2.3.2 Deals
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 THERMO FISHER SCIENTIFIC INC
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Product launches and approvals
- 16.1.3.3.2 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses and competitive threats
- 16.1.4 ABBOTT LABORATORIES
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Deals
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 AGILENT TECHNOLOGIES INC.
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Product launches and approvals
- 16.1.5.3.2 Deals
- 16.1.5.3.3 Expansions
- 16.1.5.4 MnM view
- 16.1.5.4.1 Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses and competitive threats
- 16.1.6 QIAGEN N.V.
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Product launches and approvals
- 16.1.6.3.2 Deals
- 16.1.6.3.3 Expansions
- 16.1.6.4 MnM view
- 16.1.6.4.1 Right to win
- 16.1.6.4.2 Strategic choices
- 16.1.6.4.3 Weaknesses and competitive threats
- 16.1.7 ILLUMINA, INC
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Product launches and approvals
- 16.1.7.3.2 Deals
- 16.1.7.3.3 Expansions
- 16.1.7.4 MnM view
- 16.1.7.4.1 Right to win
- 16.1.7.4.2 Strategic choices
- 16.1.7.4.3 Weaknesses and competitive threats
- 16.1.8 HOLOGIC, INC
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Product launches and approvals
- 16.1.8.3.2 Deals
- 16.1.8.3.3 Expansions
- 16.1.8.4 MnM view
- 16.1.8.4.1 Right to win
- 16.1.8.4.2 Strategic choices
- 16.1.8.4.3 Weaknesses and competitive threats
- 16.1.9 BECTON, DICKINSON AND COMPANY
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Product launches and approvals
- 16.1.9.3.2 Deals
- 16.1.9.4 MnM view
- 16.1.9.4.1 Right to win
- 16.1.9.4.2 Strategic choices
- 16.1.9.4.3 Weaknesses and competitive threats
- 16.1.10 SIEMENS HEALTHINEERS AG
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Product launches and approvals
- 16.1.10.3.2 Expansions
- 16.1.10.4 MnM view
- 16.1.10.4.1 Right to win
- 16.1.10.4.2 Strategic choices
- 16.1.10.4.3 Weaknesses and competitive threats
- 16.1.11 EXACT SCIENCES CORPORATION
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Product launches and approvals
- 16.1.11.3.2 Deals
- 16.1.11.3.3 Expansions
- 16.1.12 GUARDANT HEALTH, INC
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Product launches and approvals
- 16.1.12.3.2 Deals
- 16.1.13 SYSMEX CORPORATION
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Expansions
- 16.1.14 BIOMERIEUX SA.
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Product launches and approvals
- 16.1.15 MYRIAD GENETICS, INC
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Product launches and approvals
- 16.1.15.3.2 Deals
- 16.1.1 F. HOFFMANN-LA ROCHE
- 16.2 OTHER PLAYERS
- 16.2.1 NEOGENOMICS, INC
- 16.2.2 NATERA, INC
- 16.2.3 TEMPUS AI, INC
- 16.2.4 GRAIL, INC
- 16.2.5 CARIS LIFE SCIENCES, INC, INC.
- 16.2.6 PERSONALIS, INC
- 16.2.7 DELFI DIAGNOSTICS, INC
- 16.2.8 FULGENT GENETICS, INC
- 16.2.9 BURNING ROCK BIOTECH LIMITED
- 16.2.10 GENETRON HOLDINGS LIMITED
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.2 RESEARCH APPROACH
- 17.2.1 SECONDARY RESEARCH
- 17.2.1.1 Key data from secondary sources
- 17.2.2 PRIMARY DATA
- 17.2.2.1 Primary sources
- 17.2.2.2 Key data from primary sources
- 17.2.2.3 Key industry insights
- 17.2.1 SECONDARY RESEARCH
- 17.3 MARKET SIZE ESTIMATION
- 17.3.1 BOTTOM-UP APPROACH
- 17.3.1.1 Approach 1: Company revenue estimation approach
- 17.3.1.2 Approach 2: Presentations of companies and primary interviews
- 17.3.1.3 Growth forecast
- 17.3.2 TOP-DOWN APPROACH
- 17.3.1 BOTTOM-UP APPROACH
- 17.4 MARKET BREAKDOWN AND DATA TRIANGULATION
- 17.5 MARKET SHARE ANALYSIS
- 17.6 RESEARCH ASSUMPTIONS
- 17.6.1 PARAMETRIC ASSUMPTIONS
- 17.6.2 GROWTH RATE ASSUMPTIONS
- 17.7 RESEARCH LIMITATIONS
- 17.8 RISK ASSESSMENT
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS


