

|
시장보고서
상품코드
2149762
기내 엔터테인먼트 및 커넥티비티 시장 : 제공 방식별, 등급별, 플랫폼별, 최종 용도별 - 세계 예측(-2031년)In-Flight Entertainment & Connectivity Market by Offering (If Entertainment, If Connectivity), Class (First, Business, Premium Economy, Economy), Platform (Narrow-Body Aircraft, Wide-Body Aircraft, Business Jet), End Use - Global Forecast To 2031 |
||||||

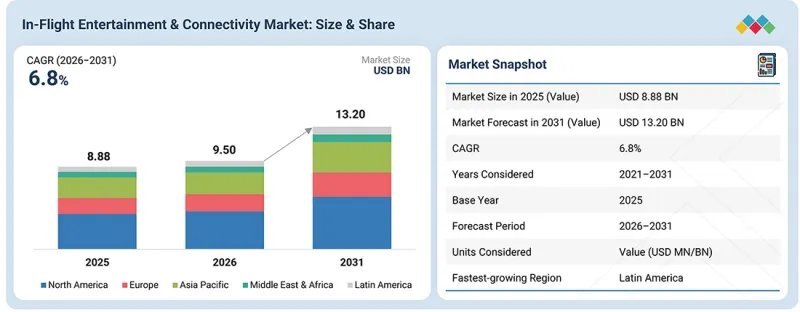
기내 엔터테인먼트 및 커넥티비티 시장은 2026년 95억 달러에서 2031년까지 132억 달러로 연평균 성장률(CAGR) 6.8%를 기록하며 확대될 것으로 전망됩니다.
이 시장의 성장은 기내 인터넷 접속 및 디지털 엔터테인먼트 서비스에 대한 승객의 수요 증가에 힘입어 이루어지고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 제공, 플랫폼, 최종 용도, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양(APAC), 기타 지역(RoW) |
각 항공사는 승객 경험을 향상시키기 위해 기존 항공기에 고속 Wi-Fi, 무선 기내 엔터테인먼트(IFE), 스트리밍 기능 및 개인 단말기 연결 기능을 도입하여 업그레이드를 진행하고 있습니다. 이에 따라 민간 항공기 및 비즈니스 제트기를 막론하고, 승객을 위한 커넥티드 서비스를 뒷받침하는 첨단 위성 기반 및 하이브리드형 연결 환경, 클라우드 기반 IFE 플랫폼, 맞춤형 콘텐츠, 그리고 소프트웨어 기반 솔루션에 대한 수요가 증가하고 있습니다.
“등급별로는 퍼스트 클래스 부문이 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예상됩니다.”
비즈니스 클래스 부문은 항공사들이 프리미엄 객실 업그레이드에 주력하고 있으며, 비즈니스 여행객에게 연결성의 중요성이 높아지고 있는 점을 배경으로, 기내 엔터테인먼트 및 커넥티비티 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 비즈니스 클래스 승객은 일반적으로 비행 중 업무, 커뮤니케이션, 오락을 위해 신뢰할 수 있는 고속 인터넷을 필요로 합니다. 이에 따라 각 항공사는 비즈니스 클래스 객실에서 첨단 Wi-Fi, 좌석 등받이형 IFE, 대형 디스플레이, 개인 단말기 연결 기능 및 맞춤형 디지털 서비스에 대한 투자를 확대하고 있습니다. 프리미엄 여행 경험의 지속적인 향상과 객실 현대화는 이 부문에서 IFE 솔루션에 대한 수요를 더욱 촉진하고 있습니다.
“예측 기간 동안 기내 엔터테인먼트 부문이 시장 점유율의 대부분을 차지할 것으로 예상됩니다.”
기내 엔터테인먼트 부문은 민간 항공기 내 엔터테인먼트 시스템의 보급에 힘입어, 기내 엔터테인먼트 및 연결 시장에서 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. 항공사들은 승객의 기대에 부응하기 위해 좌석 등받이형 및 무선형 IFE, 스트리밍 및 저장형 콘텐츠, 개인 단말기를 통한 엔터테인먼트 제공을 지속하고 있습니다. 프리미엄 콘텐츠 확충, 대형 디스플레이 도입, 무선 스트리밍, 그리고 맞춤형 엔터테인먼트 서비스의 확대가 기내 엔터테인먼트 부문에 대한 투자를 더욱 촉진하고 있습니다.
“예측 기간 동안 북미가 가장 큰 시장 점유율을 차지할 것으로 예상됩니다.”
북미는 대규모 민간 항공기 기단과 주요 항공사의 강력한 입지를 바탕으로 기내 엔터테인먼트 및 커넥티비티 시장에서 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. 이 지역의 항공사들은 자사 기단 전체에 걸쳐 고속 Wi-Fi, 무선 IFE 및 위성 기반 연결성을 적극적으로 확대하고 있습니다. 지속적인 항공기 인도, 기단 업그레이드 및 개조 또한 첨단 엔터테인먼트 및 연결 시스템에 대한 수요를 창출하고 있으며, 기내 디지털 서비스에 대한 승객들의 높은 이용률은 해당 지역의 시장을 더욱 견인하고 있습니다.
기내 엔터테인먼트 및 커넥티비티 시장의 주요 참여 기업 구성은 다음과 같습니다:
- 기업 유형별 : Tier 1 - 35%, Tier 2 - 45%, Tier 3 - 20%
- 직책별 : 이사 - 25%, C레벨 임원 - 35%, 기타(매니저 및 C레벨 이외의 임원) - 40%
- 지역별 : 북미 - 21%, 유럽 - 18%, 아시아태평양 - 42%, 중동 및 아프리카 - 10%, 라틴아메리카 - 9%
조사 범위:
본 조사는 기내 엔터테인먼트 및 커넥티비티 시장을 다양한 부문 및 하위 부문에 걸쳐 포괄하고 있습니다. 본 조사의 목적은 시장의 각 분야 및 지역별 시장 규모와 성장 잠재력을 추정하는 것입니다. 또한, 본 조사에는 시장 내 주요 기업에 대한 상세한 경쟁 분석, 기업 개요, 제품 및 사업 내용에 관한 주요 발견 사항, 최근 동향, 그리고 각 기업이 채택하고 있는 주요 시장 전략이 포함되어 있습니다.
본 보고서를 구매해야 하는 이유:
본 보고서는 기내 엔터테인먼트 및 커넥티비티 시장 전체의 매출에 대한 가장 정확한 추정치를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업을 지원합니다. 또한, 이해관계자들이 경쟁 구도를 이해하고, 자사의 비즈니스를 더 나은 위치로 이끌며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻는 데 도움이 됩니다. 더불어, 본 보고서는 이해관계자들이 시장 동향을 파악하는 데 도움을 주며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
마지막으로, 본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 시장 촉진요인(승객의 ‘BYOD(Bring Your Own Device)’ 증가 추세, 클라우드 서비스로의 전환 가속화, 기체 현대화 및 레거시 IFEC 시스템 개량, 원활하고 고품질의 기내 연결성에 대한 수요 증가, 스트리밍 기반 기내 엔터테인먼트의 보급 확대), 제약요인(엄격한 데이터 개인정보 보호 규정, 대역폭 제한, 항공기 중량 및 전력 관련 제약), 기회(항공사와 콘텐츠 플랫폼 간의 제휴 확대, 기내 한정 혜택에 대한 관심 증가, 개방적이고 상호 운용 가능한 IFEC 플랫폼의 확대), 과제(기내 스트리밍용 콘텐츠 라이선스 확보의 복잡성, 도입 및 통합에 드는 높은 비용)
- 시장 침투율 : 시장을 선도하는 주요 기업들이 제공하는 기내 엔터테인먼트 및 커넥티비티 솔루션에 대한 종합적인 정보
- 제품 개발/혁신 : 기내 엔터테인먼트 및 커넥티비티 시장의 향후 기술 동향, 연구 개발 활동, 신제품 출시에 대한 상세한 분석
- 시장 개발 : 다양한 지역의 수익성 높은 시장에 대한 종합적인 정보
- 시장 다각화 : 기내 엔터테인먼트 및 커넥티비티 시장의 신제품, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁 분석 : 기내 엔터테인먼트 및 커넥티비티 시장의 주요 기업들의 시장 점유율, 성장 전략, 제품, 생산능력에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 기내 엔터테인먼트 및 커넥티비티 시장에서 사업자에게 매력적인 기회
- 기내 엔터테인먼트 및 커넥티비티 시장 : 제공 유형별
- 기내 엔터테인먼트 및 커넥티비티 시장 : 플랫폼별
- 기내 엔터테인먼트 및 커넥티비티 시장 : 최종 용도별
- 기내 엔터테인먼트 및 커넥티비티 시장 : 클래스별
제4장 시장 개요
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 기내 엔터테인먼트 및 커넥티비티 시장의 미충족 수요와 미개척 분야
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
제5장 업계 동향
- 생태계 분석
- 제조업체 및 시스템 공급업체
- 서비스 제공업체
- 최종사용자
- 세계 기내 엔터테인먼트 및 커넥티비티 시장 동향
- 밸류체인 분석
- 가격 분석
- 2025년 서비스 유형별 평균 판매 가격
- IFE 하드웨어 장비의 참고 가격
- 무역 분석
- HS 코드 852872
- HS 코드 851762
- 사례 연구
- 사례 연구 1 : 델타항공, 클라우드 기반의 맞춤형 기내 엔터테인먼트 도입
- 사례 연구 2 : 에티하드 항공, 전 기종에 비아샛 통신 연결 확대
- 사례 연구 3 : 루프트한자가 기내 엔터테인먼트의 일환으로 가상현실을 시범 도입
- 2026-2027년 주요 컨퍼런스 및 행사
- 고객의 비즈니스에 영향을 미치는 동향과 파괴적 혁신
- 운영 데이터
- OEM별 신규 항공기 수주 대수,2023-2025년(대)
- 기종별 신규 항공기 수주 대수,2022-2024년(대)
- 총 소유 비용
- 거시경제 전망
- GDP 동향 및 전망
- 비즈니스 모델
- 광고 및 스폰서 지원 연결 서비스
- 서비스형 연결(CAAS)
- IFEC 하드웨어 판매 및 시스템 통합
- 부품 명세서(BOM) 분석
- 기내 엔터테인먼트 솔루션을 위한 부품 명세서(BOM) 분석
- 기내 연결 솔루션을 위한 부품 명세서(BOM) 분석
제6장 기술의 발전, AI의 영향, 특허, 혁신 및 향후 응용
- 주요 기술
- 다중 궤도 위성 및 LEO(저궤도) 기반 기내 연결 기술
- 5G 및 차세대 항공기-지상 간 연결 기술
- 엣지 컴퓨팅 및 클라우드 기반 기내 엔터테인먼트 기술
- 보완 기술
- 첨단 항공기용 안테나, 모뎀 및 위성 통신 단말기 기술
- 무선 기내 네트워크 및 디지털 콘텐츠 관리 기술
- 관련 기술
- 항공사의 디지털 커머스 및 맞춤형 승객 경험 기술
- 스마트 기내 디스플레이, 승객용 기기 및 인간-기계 인터페이스 기술
- 기술 로드맵
- AI/생성형 AI의 영향
- 주요 사용 사례 및 시장 잠재력
- 모범 사례
- AI 도입 사례 연구
- 상호 연계되는 생태계와 시장 참여자에 미치는 영향
- 생성형 AI 도입에 대한 고객의 준비 현황
- 특허 분석
- 향후 적용 사례
- 성공 사례 및 실제 적용 사례
- 파나소닉 아비오닉스 : IFEC 진단을 위한 에이전틱 AI
- 델타항공 : AI를 활용한 기내 엔터테인먼트 개인화
- 루프트한자 그룹 : AI를 활용한 객실 결함 관리
제7장 지속가능성과 규제 현황
- 지역별 규제 및 규정 준수
- 조직
- 업계 기준
- 지속가능성 이니셔티브
- 경량 IFE 하드웨어 및 저전력 연결 시스템
- IFE 스크린, 좌석용 전자기기, 케이블, 안테나, 레돔 및 연결 장비에 재활용 가능한 소재 사용
- 인증, 표시 및 환경 기준
제8장 고객 현황 및 구매 행동
- 의사결정 과정
- 구매 담당자, 이해관계자 및 구매 평가 기준
- 구매 과정에서 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 다양한 최종 이용 산업 분야의 미충족 수요
제9장 기내 엔터테인먼트 및 커넥티비티 시장 : 제공 유형별
- 기내 엔터테인먼트
- 기내 연결성
제10장 기내 엔터테인먼트 및 커넥티비티 시장 : 최종 용도별
- OEM
- 애프터마켓
제11장 기내 엔터테인먼트 및 커넥티비티 시장 : 플랫폼별
- 협폭기
- 와이드바디 항공기
- 비즈니스 제트기
제12장 기내 엔터테인먼트 및 커넥티비티 시장 : 클래스별
- 일등석
- 비즈니스 클래스
- 프리미엄 이코노미 클래스
- 이코노미 클래스
제13장 기내 엔터테인먼트 및 커넥티비티 시장 : 지역별
- 북미
- 미국
- 캐나다
- 유럽
- 영국
- 프랑스
- 독일
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양
- 중동 및 아프리카
- GCC
- 튀르키예
- 남아프리카
- 라틴아메리카
- 브라질
- 멕시코
- 기타 라틴아메리카
제14장 경쟁 현황
- 주요 기업의 전략
- 수익 분석
- 시장 점유율 분석
- 기업 평가 매트릭스
- 스타 기업
- 신흥 리더
- 광범위한 참여 기업
- 진입 기업
- 기업의 사업 전개
- 스타트업/중소기업 평가 매트릭스(2025년)
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹
- 기업 가치 평가와 재무 지표
- 브랜드 비교
- 경쟁 시나리오
- 제품 출시
- 거래
- 기타 동향
제15장 기업 개요
- 주요 기업
- PANASONIC AVIONICS CORPORATION
- THALES
- ANUVU
- COLLINS AEROSPACE(PARENT : RTX CORPORATION)
- ASTRONICS CORPORATION
- VIASAT, INC.
- GOGO BUSINESS AVIATION, LLC
- SAFRAN
- HONEYWELL INTERNATIONAL INC.
- SITA
- ECA GROUP
- IRIDIUM COMMUNICATIONS INC.
- LUFTHANSA SYSTEMS
- AERQ
- BLUEBOX AVIATION SYSTEMS LTD.
- 기타 주요 기업
- EUTELSAT COMMUNICATIONS SA
- IMMFLY
- IDEANOVA TECHNOLOGIES, INC.
- INFLIGHT VR SOFTWARE GMBH
- SMARTSKY NETWORKS, LLC.
- ARGONFDS
- AEROPLAY ENTERTAINMENT
- IMAGIK INTERNATIONAL CORP.
- SPAFAX
- BURRANA
제16장 조사 방법론
제17장 부록
KSM 26.10.23The in-flight entertainment and connectivity market is projected to grow from USD 9.50 billion in 2026 to USD 13.20 billion by 2031 at a CAGR of 6.8%. The market is driven by increasing passenger demand for onboard connectivity and digital entertainment services.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion) |
| Segments | By Offering, Platform, End Use and Region |
| Regions covered | North America, Europe, APAC, RoW |
Airlines are upgrading existing aircraft with high-speed Wi-Fi, wireless IFE, streaming capabilities, and personal-device connectivity to improve the passenger experience. This is increasing demand for advanced satellite-based and hybrid connectivity, cloud-based IFE platforms, personalized content, and software-based solutions that support connected passenger services across commercial and business aircraft.
"By class, the first class segment is expected to have the highest CAGR during the forecast period."
The business class segment is expected to register the highest CAGR in the In-flight entertainment and connectivity market, supported by increasing airline focus on premium cabin upgrades and the growing importance of connectivity for business travelers. Business class passengers typically require reliable high-speed internet for work, communication, and entertainment during flights. Airlines are therefore investing in advanced Wi-Fi, seatback IFE, larger displays, personal device connectivity, and personalized digital services in business class cabins. The continued improvement of premium travel and cabin modernization is further supporting demand for IFEC solutions in this segment.
"By offering, the in-flight entertainment segment is expected to have the dominant market share during the forecast period."
The in-flight entertainment segment is expected to account for the dominant market share in the in-flight entertainment and connectivity market, supported by the widespread use of entertainment systems across commercial aircraft. Airlines continue to provide seatback and wireless IFE, streamed and stored content, and personal device entertainment to meet passenger expectations. The expansion of premium content, larger displays, wireless streaming, and personalized entertainment services is further supporting investment in the in-flight entertainment segment.
"North America is expected to account for the largest market share during the forecast period."
North America is expected to account for the largest market share in the in-flight entertainment and connectivity market, supported by its large commercial aircraft fleet and strong presence of major airlines. Airlines in the region have been actively expanding high-speed Wi-Fi, wireless IFE, and satellite-based connectivity across their fleets. Continued aircraft deliveries, fleet upgrades, and retrofits are also creating demand for advanced entertainment and connectivity systems, while high passenger adoption of onboard digital services further supports the regional market.
Panasonic Corporation of North America (US), Thales (France), Anuvu (US), RTX (US), and Astronics Corporation (US) are some of the key players in the in-flight entertainment and connectivity market.
The breakdown of profiles for primary participants in the in-flight entertainment and connectivity market is provided below:
- By Company Type: Tier 1 - 35%, Tier 2 - 45%, and Tier 3 - 20%
- By Designation: Directors - 25%, C-level Executives - 35%, and Others (Managers and Other Non-C-level Executives) - 40%
- By Region: North America -21%, Europe - 18%, Asia Pacific - 42%, Middle East & Africa -10%, Latin America - 9%
Research Coverage:
This study covers the in-flight entertainment and connectivity market across various segments and subsegments. It aims to estimate the size and growth potential of this market across different parts and regions. Additionally, this study includes an in-depth competitive analysis of key players in the market, their company profiles, key observations on their products and business offerings, recent developments, and the key market strategies they have adopted.
Reasons to Buy This Report:
The report will help market leaders/new entrants with information on the closest approximations of revenue for the overall in-flight entertainment and connectivity market. It will also help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. Moreover, the report will help stakeholders understand the market pulse and will provide information on key market drivers, restraints, challenges, and opportunities.
Lastly, the report provides insights into the following pointers:
- Market drivers (rising trend of bring your own device among the passengers, rising shift toward cloud services, fleet modernization and retrofit of legacy IFEC systems, growing demand for seamless, high-quality in-flight connectivity, growing adoption of streaming-based in-flight entertainment), restraints (stringent data privacy regulations, bandwidth limitations, aircraft weight and power constraints), opportunities (growing collaborations between airlines and content platforms, rising interest in exclusive in-flight offers, expansion of open and interoperable IFEC platforms), challenges (complexity of securing content licensing rights for in-flight streaming, high cost of installation and integration)
- Market Penetration: Comprehensive information on in-flight entertainment and connectivity solutions offered by the top players in the market
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product launches in the in-flight entertainment and connectivity market
- Market Development: Comprehensive information about lucrative markets across varied regions
- Market Diversification: Exhaustive information about new products, untapped geographies, recent developments, and investments in the in-flight entertainment and connectivity market
- Competitive Assessment: In-depth assessment of market share, growth strategies, products, and manufacturing capabilities of leading players in the in-flight entertainment and connectivity market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET SEGMENTATION & REGIONAL SNAPSHOT
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 2.4 HIGH GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 3.2 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY OFFERING
- 3.3 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY PLATFORM
- 3.4 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY END USE
- 3.5 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY CLASS
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising trend of bring your own device among passengers
- 4.2.1.2 Rising shift toward cloud services
- 4.2.1.3 Fleet modernization and retrofit of legacy IFEC systems
- 4.2.1.4 Growing demand for seamless, high-quality in-flight connectivity
- 4.2.1.5 Growing adoption of streaming-based in-flight entertainment
- 4.2.2 RESTRAINTS
- 4.2.2.1 Stringent data privacy regulations
- 4.2.2.2 Bandwidth limitations
- 4.2.2.3 Aircraft weight and power constraints
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of open and interoperable IFEC platforms
- 4.2.3.2 Growing collaborations between airlines and content platforms
- 4.2.3.3 Rising interest in exclusive in-flight offers
- 4.2.4 CHALLENGES
- 4.2.4.1 Complexity of securing content licensing rights for in-flight streaming
- 4.2.4.2 High cost of installation and integration
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES IN IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 4.4 INTER-CONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 ECOSYSTEM ANALYSIS
- 5.2.1 MANUFACTURERS AND SYSTEM PROVIDER
- 5.2.2 SERVICE PROVIDER
- 5.2.3 END USER
- 5.3 TRENDS IN GLOBAL IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE, BY OFFERING, 2025
- 5.5.2 INDICATIVE PRICING OF IFE HARDWARE DEVICES
- 5.6 TRADE ANALYSIS
- 5.6.1 HS CODE 852872
- 5.6.1.1 Import scenario (HS code 852872)
- 5.6.1.2 Export scenario (HS code 852872)
- 5.6.2 HS CODE 851762
- 5.6.2.1 Import scenario (HS code 851762)
- 5.6.2.2 Export scenario (HS code 851762)
- 5.6.1 HS CODE 852872
- 5.7 CASE STUDIES
- 5.7.1 CASE STUDY 1: DELTA AIR LINES INTRODUCED CLOUD-BASED AND PERSONALIZED IN-FLIGHT ENTERTAINMENT
- 5.7.2 CASE STUDY 2: ETIHAD AIRWAYS EXPANDED VIASAT CONNECTIVITY ACROSS ITS FLEET
- 5.7.3 CASE STUDY 3: LUFTHANSA TESTED VIRTUAL REALITY AS PART OF IN-FLIGHT ENTERTAINMENT
- 5.8 KEY CONFERENCES & EVENTS, 2026-2027
- 5.9 TRENDS & DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 OPERATIONAL DATA
- 5.10.1 NEW NEW AIRCRAFT ORDERS BY OEMS, 2023-2025 (UNITS)
- 5.10.2 NEW AIRCRAFT ORDERS, BY AIRCRAFT TYPE, 2022-2024 (UNITS)
- 5.11 TOTAL COST OF OWNERSHIP
- 5.12 MACROECONOMIC OUTLOOK
- 5.12.1 INTRODUCTION
- 5.12.2 GDP TRENDS AND FORECAST
- 5.13 BUSINESS MODELS
- 5.13.1 ADVERTISING & SPONSORED CONNECTIVITY
- 5.13.2 CONNECTIVITY-AS-A-SERVICE
- 5.13.3 IFEC HARDWARE SALES & SYSTEM INTEGRATION
- 5.14 BILL OF MATERIALS ANALYSIS
- 5.14.1 BILL OF MATERIALS ANALYSIS FOR IN-FLIGHT ENTERTAINMENT SOLUTIONS
- 5.14.2 BILL OF MATERIALS ANALYSIS FOR IN-FLIGHT CONNECTIVITY SOLUTIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 MULTI-ORBIT SATELLITE AND LEO-BASED IN-FLIGHT CONNECTIVITY TECHNOLOGY
- 6.1.2 5G AND NEXT-GENERATION AIR-TO-GROUND CONNECTIVITY TECHNOLOGY
- 6.1.3 EDGE COMPUTING AND CLOUD-ENABLED IN-FLIGHT ENTERTAINMENT TECHNOLOGY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ADVANCED AIRCRAFT ANTENNA, MODEM, AND SATCOM TERMINAL TECHNOLOGIES
- 6.2.2 WIRELESS CABIN NETWORKING AND DIGITAL CONTENT MANAGEMENT TECHNOLOGIES
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 AIRLINE DIGITAL COMMERCE AND PERSONALIZED PASSENGER EXPERIENCE TECHNOLOGY
- 6.3.2 SMART CABIN DISPLAYS, PASSENGER DEVICES, AND HUMAN-MACHINE INTERFACE TECHNOLOGY
- 6.4 TECHNOLOGY ROADMAP
- 6.5 IMPACT OF AI/GENERATIVE AI
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL
- 6.5.2 BEST PRACTICES
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION
- 6.5.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GEN AI
- 6.6 PATENT ANALYSIS
- 6.7 FUTURE APPLICATIONS
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 PANASONIC AVIONICS CORPORATION: AGENTIC AI FOR IFEC DIAGNOSTICS
- 6.8.2 DELTA AIR LINES: AI-BASED PERSONALIZATION OF IN-FLIGHT ENTERTAINMENT
- 6.8.3 LUFTHANSA GROUP: AI-BASED CABIN DEFECT MANAGEMENT
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 LIGHTWEIGHT IFE HARDWARE AND LOW-POWER CONNECTIVITY SYSTEMS
- 7.2.2 USE OF RECYCLABLE MATERIALS IN IFE SCREENS, SEAT ELECTRONICS, CABLING, ANTENNAS, RADOMES, AND CONNECTIVITY EQUIPMENT
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYERS, STAKEHOLDERS, AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.2 IN-FLIGHT ENTERTAINMENT
- 9.2.1 PRODUCT
- 9.2.1.1 Portable devices
- 9.2.1.1.1 Increasing personal-device usage and wireless IFE adoption to drive growth
- 9.2.1.2 Non-portable devices
- 9.2.1.2.1 Rising airline investment in seatback systems to drive growth
- 9.2.1.1 Portable devices
- 9.2.2 IN-FLIGHT CONTENT
- 9.2.2.1 Streamed
- 9.2.2.1.1 Rising demand for onboard streaming and personalized digital content to drive growth
- 9.2.2.2 Stored
- 9.2.2.2.1 Expanding content libraries and reliable offline entertainment to drive growth
- 9.2.2.1 Streamed
- 9.2.3 IN-FLIGHT RETAIL AND ADVERTISING
- 9.2.3.1 Retail
- 9.2.3.1.1 Digital onboard commerce and passenger engagement to drive growth
- 9.2.3.2 Advertising
- 9.2.3.2.1 Personalized digital engagement and new airline revenue channels to drive growth
- 9.2.3.1 Retail
- 9.2.1 PRODUCT
- 9.3 IN-FLIGHT CONNECTIVITY
- 9.3.1 SOLUTION
- 9.3.1.1 Wired
- 9.3.1.1.1 Fleet modernization and seatback IFE upgrades to drive growth
- 9.3.1.2 Wireless
- 9.3.1.2.1 Personal-device usage and lower-complexity deployment to drive growth
- 9.3.1.1 Wired
- 9.3.2 IN-FLIGHT INTERNET
- 9.3.2.1 Air-to-Ground (Cellular-based)
- 9.3.2.1.1 Expanding terrestrial coverage and lower latency to drive growth
- 9.3.2.2 Satellite-based
- 9.3.2.2.1 Global route coverage and high-capacity satellite networks to drive growth
- 9.3.2.3 Hybrid-based
- 9.3.2.3.1 Multi-orbit flexibility and network resilience to drive growth
- 9.3.2.1 Air-to-Ground (Cellular-based)
- 9.3.1 SOLUTION
10 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY END USE
- 10.1 INTRODUCTION
- 10.2 OEM
- 10.2.1 NEW-AIRCRAFT DELIVERIES AND FACTORY-INSTALLED IFEC SYSTEMS TO DRIVE GROWTH
- 10.3 AFTERMARKET
- 10.3.1 EXTENDING AIRCRAFT SERVICE LIFE AND UPGRADING LEGACY SYSTEMS TO DRIVE GROWTH
11 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY PLATFORM
- 11.1 INTRODUCTION
- 11.2 NARROW-BODY AIRCRAFT
- 11.2.1 EXPANDING SINGLE-AISLE FLEETS AND WIDER DEPLOYMENT OF WIRELESS IFEC TO DRIVE GROWTH
- 11.3 WIDE-BODY AIRCRAFT
- 11.3.1 EXPANDING LONG-HAUL FLEETS AND HIGHER IFEC REQUIREMENTS TO DRIVE MARKET
- 11.4 BUSINESS JET
- 11.4.1 RISING BUSINESS JET DELIVERIES AND GREATER DEMAND FOR CONNECTED CABINS TO DRIVE MARKET
12 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY CLASS
- 12.1 INTRODUCTION
- 12.2 FIRST CLASS
- 12.2.1 INCREASING DEMAND FOR PREMIUM-CABIN SERVICES AND ADVANCED ENTERTAINMENT TO DRIVE GROWTH
- 12.3 BUSINESS CLASS
- 12.3.1 GROWING BUSINESS TRAVEL AND PREMIUM CABIN UPGRADES TO DRIVE GROWTH
- 12.4 PREMIUM ECONOMY CLASS
- 12.4.1 INCREASING PREMIUM-CABIN CAPACITY AND ENHANCED ONBOARD SERVICES TO DRIVE GROWTH
- 12.5 ECONOMY CLASS
- 12.5.1 RISING ECONOMY-CLASS PASSENGER VOLUMES AND BROADER CONNECTIVITY DEPLOYMENT TO DRIVE GROWTH
13 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 NORTH AMERICA
- 13.2.1 US
- 13.2.1.1 Rising air travel and fleet connectivity upgrades to drive market
- 13.2.2 CANADA
- 13.2.2.1 Conversion of airline fleets from limited onboard connectivity to aircraft-wide, streaming-quality internet to drive market
- 13.2.1 US
- 13.3 EUROPE
- 13.3.1 UK
- 13.3.1.1 Record air traffic and fleet-wide connectivity upgrades to drive market
- 13.3.2 FRANCE
- 13.3.2.1 Expansion of high-speed onboard connectivity to drive market
- 13.3.3 GERMANY
- 13.3.3.1 Lufthansa's fleet-wide connectivity upgrades to drive market
- 13.3.4 ITALY
- 13.3.4.1 International passenger traffic and fleet digitalization to drive market
- 13.3.5 SPAIN
- 13.3.5.1 Rising international air traffic and high-speed connectivity deployment to drive market
- 13.3.6 REST OF EUROPE
- 13.3.1 UK
- 13.4 ASIA PACIFIC
- 13.4.1 CHINA
- 13.4.1.1 Rapid passenger growth and aircraft connectivity upgrades to drive market
- 13.4.2 INDIA
- 13.4.2.1 Rapid air travel expansion and rising onboard data usage to drive market
- 13.4.3 JAPAN
- 13.4.3.1 Rising international air traffic and wider onboard streaming to drive market
- 13.4.4 AUSTRALIA
- 13.4.4.1 International traffic and fleet connectivity upgrades to drive market
- 13.4.5 SOUTH KOREA
- 13.4.5.1 Expanding international air traffic and fleet-wide Wi-Fi deployment to drive market
- 13.4.6 REST OF ASIA PACIFIC
- 13.4.1 CHINA
- 13.5 MIDDLE EAST & AFRICA
- 13.5.1 GCC
- 13.5.1.1 UAE
- 13.5.1.1.1 Rapid airline expansion and high-capacity connectivity to drive market
- 13.5.1.2 Saudi Arabia
- 13.5.1.2.1 Growing long-haul operations and airline fleet modernization to drive market
- 13.5.1.3 Qatar
- 13.5.1.3.1 Expanding global connectivity and fleet-wide satellite upgrades to drive market
- 13.5.1.1 UAE
- 13.5.2 TURKEY
- 13.5.2.1 Record passenger traffic and expanding onboard connectivity to drive market
- 13.5.3 SOUTH AFRICA
- 13.5.3.1 International route recovery and digital cabin upgrades to drive market
- 13.5.1 GCC
- 13.6 LATIN AMERICA
- 13.6.1 BRAZIL
- 13.6.1.1 Record passenger traffic and growing passenger-device connectivity to drive market
- 13.6.2 MEXICO
- 13.6.2.1 Transition toward wireless entertainment and onboard internet on newer aircraft to drive market
- 13.6.3 REST OF LATIN AMERICA
- 13.6.1 BRAZIL
14 COMPETITIVE LANDSCAPE
- 14.1 INTRODUCTION
- 14.2 KEY PLAYER STRATEGIES
- 14.3 REVENUE ANALYSIS
- 14.4 MARKET SHARE ANALYSIS
- 14.5 COMPANY EVALUATION MATRIX
- 14.5.1 STARS
- 14.5.2 EMERGING LEADERS
- 14.5.3 PERVASIVE PLAYERS
- 14.5.4 PARTICIPANTS
- 14.5.5 COMPANY FOOTPRINT
- 14.6 STARTUP/SME EVALUATION MATRIX, 2025
- 14.6.1 PROGRESSIVE COMPANIES
- 14.6.2 RESPONSIVE COMPANIES
- 14.6.3 DYNAMIC COMPANIES
- 14.6.4 STARTING BLOCKS
- 14.6.5 COMPETITIVE BENCHMARKING
- 14.7 COMPANY VALUATION AND FINANCIAL METRICS
- 14.8 BRAND COMPARISON
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 OTHER DEVELOPMENTS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 PANASONIC AVIONICS CORPORATION
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 THALES
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 ANUVU
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 COLLINS AEROSPACE (PARENT:RTX CORPORATION)
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 ASTRONICS CORPORATION
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 VIASAT, INC.
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 Recent developments
- 15.1.7 GOGO BUSINESS AVIATION, LLC
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.8 SAFRAN
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.9 HONEYWELL INTERNATIONAL INC.
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 Recent developments
- 15.1.10 SITA
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.11 ECA GROUP
- 15.1.11.1 Business overview
- 15.1.11.2 Products/Solutions/Services offered
- 15.1.11.3 Recent developments
- 15.1.12 IRIDIUM COMMUNICATIONS INC.
- 15.1.12.1 Business overview
- 15.1.12.2 Products/Solutions/Services offered
- 15.1.13 LUFTHANSA SYSTEMS
- 15.1.13.1 Business overview
- 15.1.13.2 Products/Solutions/Services offered
- 15.1.13.3 Recent developments
- 15.1.14 AERQ
- 15.1.14.1 Business overview
- 15.1.14.2 Products/Solutions/Services offered
- 15.1.14.3 Recent developments
- 15.1.15 BLUEBOX AVIATION SYSTEMS LTD.
- 15.1.15.1 Business overview
- 15.1.15.2 Products/Solutions/Services offered
- 15.1.15.3 Recent developments
- 15.1.1 PANASONIC AVIONICS CORPORATION
- 15.2 OTHER PLAYERS
- 15.2.1 EUTELSAT COMMUNICATIONS SA
- 15.2.2 IMMFLY
- 15.2.3 IDEANOVA TECHNOLOGIES, INC.
- 15.2.4 INFLIGHT VR SOFTWARE GMBH
- 15.2.5 SMARTSKY NETWORKS, LLC.
- 15.2.6 ARGONFDS
- 15.2.7 AEROPLAY ENTERTAINMENT
- 15.2.8 IMAGIK INTERNATIONAL CORP.
- 15.2.9 SPAFAX
- 15.2.10 BURRANA
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Breakdown of primary interviews
- 16.1.3 KEY PRIMARY SOURCES
- 16.1.1 SECONDARY DATA
- 16.2 FACTOR ANALYSIS
- 16.2.1 INTRODUCTION
- 16.2.2 DEMAND-SIDE ANALYSIS
- 16.2.3 DEMAND-SIDE INDICATORS
- 16.2.3.1 Passenger traffic
- 16.2.3.2 Emerging countries
- 16.2.4 SUPPLY-SIDE ANALYSIS
- 16.2.4.1 Supply-side indicators
- 16.3 RESEARCH APPROACH AND METHODOLOGY
- 16.3.1 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 16.3.1.1 OEM
- 16.3.1.2 Aftermarket
- 16.3.2 IN-FLIGHT CONNECTIVITY MARKET
- 16.3.3 IN-FLIGHT ENTERTAINMENT MARKET
- 16.3.4 TOP-DOWN APPROACH
- 16.3.1 IN-FLIGHT ENTERTAINMENT AND CONNECTIVITY MARKET
- 16.4 DATA TRIANGULATION
- 16.5 RESEARCH ASSUMPTIONS
- 16.5.1 ASSUMPTIONS USED IN MARKET SIZING AND FORECAST
- 16.6 RESEARCH LIMITATIONS
- 16.7 RISK ANALYSIS
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS


