

|
시장보고서
상품코드
2152960
데이터센터 인프라 관리 시장 : DCIM 소프트웨어, 기능별 - 세계 예측(-2031년)Data Center Infrastructure Management Market by DCIM Software (Monitoring, Operations & Management) and Functionality (Asset Management, Operational Monitoring, Performance Optimization, Configuration, Reporting & Dashboards) - Global Forecast to 2031 |
||||||

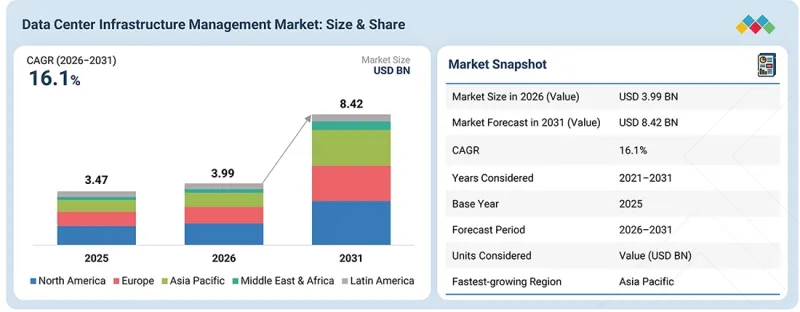
전 세계 데이터센터 인프라 관리(DCIM) 시장은 2026년 39억 9,000만 달러에서 2031년까지 84억 2,000만 달러로 성장할 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 16.1%에 달할 전망입니다.
인공지능(AI), 고급 분석, 자동화가 DCIM 플랫폼에 점점 더 통합됨에 따라, 사업자가 데이터센터 인프라를 모니터링하고 관리하는 방식에 변화가 일어나고 있습니다. AI 기반 기능은 예측 유지보수, 성능 최적화, 용량 계획, 에너지 관리 및 실시간 인프라 모니터링을 지원하여, 사업자가 잠재적인 문제를 파악하고 자원 활용 효율을 높이는 데 기여하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(백만 달러/십억 달러) |
| 부문 | 제공, 기능성, 배포 방식, 티어 유형, 데이터센터 규모, 최종사용자 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 중동 및 아프리카, 라틴아메리카 |
AI 및 고밀도 워크로드의 도입 확대에 따라 전력, 냉각, 공간 및 장비 성능을 최적화해야 할 필요성이 더욱 커지고 있습니다. 그 결과, DCIM 플랫폼은 기존의 모니터링 도구에서 운영 업무 자동화, 예측적 인사이트 제공, 데이터 기반 의사결정을 지원할 수 있는 지능형 인프라 관리 시스템으로 진화하고 있습니다. 데이터센터 사업자들이 점점 더 복잡해지는 인프라 환경에서 효율성, 신뢰성, 확장성 및 지속가능성을 향상시키려함에 따라, 이러한 전환으로 인해 DCIM 솔루션에 대한 수요가 더욱 높아질 것으로 예상됩니다.
“서비스 제공에 힘입어, 예측 기간 동안 서비스 부문이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
조직들이 복잡한 데이터센터 환경 전반에 걸쳐 DCIM 플랫폼의 도입, 통합, 최적화에 관한 전문적인 지원을 요구함에 따라, DCIM 시장에서 서비스의 중요성은 점점 더 커지고 있습니다. DCIM 서비스에는 설계 및 컨설팅, 통합 및 도입, 지원 및 유지보수가 포함되며, 조직이 DCIM 솔루션을 자사의 인프라 요구 사항에 맞게 조정할 수 있도록 지원합니다. 데이터센터의 분산화와 복잡화가 진행됨에 따라, 조직은 DCIM 플랫폼을 IT 인프라, 전력 관리, 냉각 시스템, 빌딩 관리 시스템 및 기타 모니터링 플랫폼과 통합하기 위한 전문 지식이 필요합니다. 기업들이 멀티사이트 및 하이브리드 인프라 환경을 도입함에 따라 통합·구축 서비스의 중요성이 특히 커지고 있는 반면, 지원·유지보수 서비스는 시스템의 가용성과 성능을 유지하는 데 도움이 됩니다. AI 기반 DCIM, 클라우드 기반 플랫폼, 고급 분석 기술의 채택 확대 또한 구현 및 통합에 대한 전문 지식에 대한 수요를 창출하고 있습니다. 조직이 신속한 도입, 효과적인 시스템 통합, 비즈니스 연속성 및 DCIM 투자 가치 극대화에 주력함에 따라, 이러한 요인들이 서비스 채택을 촉진할 것으로 예상됩니다.
“기능별로는 예측 기간 동안 자산 관리가 가장 큰 비중을 차지할 것으로 전망됩니다.”
예측 기간 동안 DCIM 시장에서 자산 관리가 가장 큰 점유율을 차지할 것으로 예상됩니다. 데이터센터 운영자는 점점 더 복잡해지고 분산되는 인프라를 관리하기 위해 IT 자산 및 시설 자산에 대한 통합적인 가시성을 점점 더 필요로 하고 있습니다. 자산 관리 기능을 통해 조직은 상세한 장비 기록을 유지하고, 자산의 위치 및 상태를 추적하며, 이용 현황을 모니터링하고, 수명주기 관리를 지원할 수 있습니다. 또한, 가용 용량에 대한 가시성을 높여 운영자가 장비 도입, 교체 및 자원 배분에 대해 정보에 기반한 의사결정을 내리는 데 도움이 됩니다. 하이퍼스케일, 코로케이션, 엔터프라이즈, 엣지 데이터센터의 도입 확대에 따라 모니터링 및 관리가 필요한 자산의 수와 다양성이 증가하고 있습니다. 자산 관리를 용량 계획, 환경 모니터링, 성능 분석과 통합함으로써 인프라 가시성은 더욱 향상됩니다. 사업자들이 기존 리소스의 최적화, 활용도 저하 해소, 인프라 계획 개선을 도모함에 따라, 종합적인 자산 관리 기능에 대한 수요는 예측 기간 동안 계속해서 견조할 것으로 전망됩니다.
“예측 기간 동안 북미가 가장 큰 시장 점유율을 차지할 것으로 예상됩니다.”
북미는 확립된 데이터센터 생태계, 하이퍼스케일 및 코로케이션 시설에 대한 지속적인 투자, 그리고 AI 및 고밀도 컴퓨팅 인프라 도입 확대에 힘입어 예측 기간 동안 DCIM 시장에서 가장 큰 점유율을 차지할 것으로 예상됩니다. 특히 미국에서는 중앙 집중식 인프라 모니터링 및 관리가 필요한 엔터프라이즈, 하이퍼스케일, 클라우드, 코로케이션 데이터센터가 다수 도입되어 있습니다. 전력 수요 증가, 랙 밀도 향상, 에너지 효율 개선에 대한 압박으로 인해 사업자들은 전력, 냉각, 용량, 환경 조건, 자산 성능을 모니터링하기 위해 DCIM 플랫폼 도입을 추진하고 있습니다. 또한, 이 지역에는 주요 DCIM 공급업체와 데이터센터 인프라 기업이 다수 존재하며, 이는 기술 도입과 플랫폼 통합을 촉진하고 있습니다. 더욱이 기존 시설의 현대화로 인해 BMS, EPMS, IT 인프라 및 기타 운영 시스템과 통합되는 DCIM 솔루션에 대한 수요가 발생하고 있습니다. 데이터센터 사업자들이 운영 가시성, 인프라 효율성, 신뢰성 높은 시설 관리를 우선시하는 가운데, 이러한 요인들로 인해 북미가 주도적인 위치를 계속 유지할 것으로 예상됩니다.
주요 참여 기업의 내역은 다음과 같습니다:
- 기업 규모별 : 티어 I : 33%, 티어 II : 25%, 티어 III : 42%
- 직책별 : C레벨 임원 : 31%, 디렉터급 : 34%, 기타 : 35%
- 지역별 : 북미 : 42%, 유럽 : 28%, 아시아태평양 : 22%, 기타 지역 : 8%
참고 : ‘기타’에는 영업 매니저, 마케팅 매니저, 제품 매니저가 포함됩니다.
참고 : ‘기타 지역’에는 중동 및 아프리카 및 라틴아메리카가 포함됩니다
참고 : Tier 1 기업의 매출은 1억 달러 이상, Tier 2 기업의 매출은 1,000만 달러에서 1억 달러, Tier 3 기업의 매출은 1,000만 달러 미만입니다
조사 범위
본 조사에서는 시장 동향, 2021년의 잠재적 성장, 그리고 2026년부터 2031년까지의 예측을 바탕으로 데이터센터 인프라 관리(DCIM) 시장에 대한 상세한 분석을 제시합니다. 또한, 데이터센터 인프라 관리 시장의 상세한 시장 동향, 경쟁 구도, 시장 규모, 예측 및 주요 업체에 대한 분석도 제공합니다. 본 조사에서는 모든 주요 지역의 데이터센터 인프라 관리 성장률과 보급률을 분석하고 있습니다.
본 보고서를 구매해야 하는 이유
본 보고서는 서버리스 컴퓨팅 시장 및 그 하위 부문의 매출에 대한 가장 정확한 추정치를 제공함으로써, 시장을 선도하는 기업과 신규 진입 기업을 지원합니다. 본 조사는 이해관계자가 경쟁 구도를 이해하는 데 도움을 주고, 비즈니스 위치를 최적화하며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 제공합니다. 또한, 이해관계자가 시장 동향을 파악할 수 있도록 지원하며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서에서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인 분석(AI 및 고밀도 데이터센터 도입 확대, 에너지 효율이 높은 솔루션에 대한 수요 증가, 원격 및 분산형 데이터센터 관리에 대한 수요 증가), 제약요인(DCIM 솔루션의 높은 도입 비용, 이기종 인프라 전반에 걸친 DCIM 도입의 복잡성과 비용), 기회(데이터센터 기술에 대한 투자 확대, 엣지 데이터센터 채택 확대), 그리고 과제(데이터 개인정보 보호 및 보안에 대한 우려)에 대해 데이터센터 인프라 관리 시장의 성장에 영향을 미치는 요인을 분석하고 있습니다.
- 제품 개발/혁신 : 데이터센터 인프라 관리 시장의 향후 기술, 연구 개발 활동 및 신제품·서비스 출시에 대한 상세한 인사이트
- 시장 개발 : 데이터센터 인프라 관리 시장의 향후 기술, 연구 개발 활동 및 신제품·서비스 출시에 대한 심층적인 이해
- 시장 다각화 : 데이터센터 인프라 관리 시장의 최신 제품 및 서비스, 미개척 지역, 최근 동향 및 투자에 대한 종합적인 세부 정보
- 경쟁 분석 : 시장 점유율, 성장 전략 및 데이터센터 인프라 관리 시장 내 각 기업에 대한 상세한 분석.
자주 묻는 질문
목차
제1장. 서론
제2장 요약
제3장 주요 인사이트
- 데이터센터 인프라 관리 시장에서 사업자를 위한 매력적인 성장 기회
- 데이터센터 인프라 관리 시장 : 제공 유형별
- 데이터센터 인프라 관리 시장 : 기능별
- 데이터센터 인프라 관리 시장 : 배포 방식별
- 데이터센터 인프라 관리 시장 : 티어 유형별
- 데이터센터 인프라 관리 시장 : 데이터센터 규모별
- 데이터센터 인프라 관리 시장 : 최종사용자별
- 데이터센터 인프라 관리 시장 : 지역별
제4장 시장 개요 및 업계 동향
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 미충족 수요 및 미개척 분야
- 소프트웨어 정의 데이터센터(SDDC) 시장의 미충족 수요
- 미개척 시장의 기회
- 상호 연관된 시장
- 여러 부문에 걸친 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
- 주요 동향 및 전략적 중점
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 구매자의 협상력
- 공급업체의 협상력
- 경쟁 기업 간의 적대 관계의 격렬함
- 거시경제 지표
- GDP 동향 및 전망
- 세계 데이터센터 솔루션 업계 동향
- 세계 클라우드 컴퓨팅 업계 동향
- 공급망 분석
- 생태계
- 가격 분석
- 주요 기업의 평균 판매 가격 동향(소프트웨어별)
- 지역별 평균 판매 가격 동향
- 2026-2027년 주요 컨퍼런스 및 행사
- 고객의 비즈니스에 영향을 미치는 동향 및 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- 코만트(Cormant), 효율성과 투명성을 추구하며 코로케이션 데이터센터 운영을 혁신
- 라리탄은 F5 네트웍스의 제품 개발 연구소에서 전력 및 냉각 관리를 강화했습니다
- RIT TECH의 ‘XPEDITE’가 베이징 지하철의 광섬유 네트워크 관리를 혁신했습니다
- MORO HUB사는 분산형 데이터센터의 통합 관리를 위해 Neteco600을 도입했습니다
- ALL IT ROOMS사는 PAESSLER PRTG 네트워크 모니터를 통해 시스템 안정성을 100% 확보했습니다
- 리딩 엣지 데이터센터가 슈나이더 일렉트릭을 활용하여 호주 지역의 연결 환경에 혁명을 일으켰습니다
- 컴퓨타센터는 NLYTE를 활용하여 데이터센터를 효과적으로 관리했습니다
- Sunbird의 DCIM이 Vodafone의 효율성과 지속가능성을 촉진했습니다
- VERTIV는 지속적인 가용성을 실현하기 위해 은행 인프라를 혁신하고 있습니다
- FNT의 DCIM 솔루션을 통해 데이터비타의 코로케이션 서비스를 강화했습니다
- 2025년 미국 관세가 데이터센터 인프라 관리 시장에 미치는 영향
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가·지역별 영향
- 산업별 영향
- 기술 분석
- 주요 기술
- 보완 기술
- 인접 기술
- 기술·제품 로드맵
- 단기(2026-2028년) | 모니터링, 통합 및 자동화
- 중기(2028-2031년) | AI를 활용한 분석 및 인프라 최적화
- 장기(2031-2036년 이후) | 자율형·AI 구동형·자가 최적화형 인프라
- 특허 분석
- 미래 응용
- AI를 활용한 예측형 인프라 관리
- 자율적인 용량 계획 및 리소스 최적화
- 지능형 에너지 및 냉각 최적화
- AI를 활용한 자산 모니터링 및 이상 감지
- 자동화된 사고 관리 및 인프라 운영
- AI/생성형 AI가 데이터센터 인프라 관리 시장에 미치는 영향
- 주요 사용 사례 및 시장의 잠재력
- 데이터센터 인프라 관리 시장의 모범 사례
- 데이터센터 인프라 관리 시장에서의 AI 도입 사례 연구
- 상호 연관된 인접 생태계 및 시장 참여자에 미치는 영향
- 데이터센터 인프라 관리 분야에서 생성형 AI 도입에 대한 고객의 준비 현황
- 규제 현황
- 규제 기관, 정부 기관 및 기타 조직
- 국가·지역별 규제
- 의사결정 과정
- 주요 이해관계자 및 구매 기준
- 구매 프로세스 내 주요 이해관계자
- 구매 기준
- 도입 장벽 및 내부 과제
- 각 최종사용자 산업 분야의 미충족 수요
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 주요 용도에서의 이익률 향상 기회
- 비즈니스 모델 분석
- 제품 라인업
- 수익원
- 수익 모델 동향
- 판매 채널
- 고객 부문
- DCIM 내 데이터 생성원
- IT 장비
- 전기 시스템
- 냉각 설비
- 환경 자원
제5장 데이터센터 인프라 관리 시장 : 제공 유형별
- DCIM 소프트웨어
- 서비스
제6장 데이터센터 인프라 관리 시장 : 기능별
- 성능 최적화
- 자산 관리
- 구성
- 운영 모니터링
- 보고서 및 대시보드
- 기타 기능
제7장 데이터센터 인프라 관리 시장 : 전개 방식별
- 온프레미스
- 클라우드
제8장 데이터센터 인프라 관리 시장 : 티어별
- Tier 1
- Tier 2
- Tier 3
- Tier 4
제9장 데이터센터 인프라 관리 시장 : 데이터센터 규모별
- 소규모 데이터센터
- 중규모 데이터센터
- 대규모 데이터센터
제10장 데이터센터 인프라 관리 시장 : 최종사용자별
- 기업
- 통신 서비스 제공업체
- 클라우드 서비스 제공업체
제11장 데이터센터 인프라 시장 : 지역별
- 북미
- 북미 : 데이터센터 인프라 관리 시장의 촉진요인
- 미국
- 캐나다
- 유럽
- 유럽 : 데이터센터 인프라 관리 시장의 성장 촉진요인
- 영국
- 독일
- 프랑스
- 이탈리아
- 기타 유럽
- 아시아태평양
- 아시아태평양 : 데이터센터 인프라 관리 시장의 촉진요인
- 중국
- 일본
- 인도
- 기타 아시아태평양
- 중동 및 아프리카
- 중동 및 아프리카 : 데이터센터 인프라 관리 시장의 성장 촉진요인
- 걸프협력회의(GCC)
- 남아프리카
- 기타 중동 및 아프리카
- 라틴아메리카
- 라틴아메리카 : 데이터센터 인프라 관리 시장의 촉진요인
- 브라질
- 멕시코
- 기타 라틴아메리카
제12장 경쟁 현황
- 주요 진입 기업의 전략/강점
- 시장 점유율 분석
- 브랜드/제품 비교
- SCHNEIDER ELECTRIC - ECOSTRUXURE IT
- VERTIV - ENVIRONET
- JOHNSON CONTROLS - METASYS DCIM MODULE
- EATON - BRIGHTLAYER DCIM
- SIEMENS- DESIGO CC/BUILDING X
- 수익 분석
- 기업 평가 매트릭스 : 주요 기업, 2023년
- 스타
- 신흥 리더
- 광범위한 업체
- 진입 기업
- 기업의 사업 전개 : 주요 기업, 2025년
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹 : 스타트업/중소기업, 2025년
- 기업 평가 및 재무 지표
- 경쟁 시나리오 및 동향
- 제품 출시 및 기능 강화
- 거래
제13장 기업 개요
- 주요 기업
- SCHNEIDER ELECTRIC
- VERTIV
- JOHNSON CONTROLS
- SIEMENS
- EATON
- HUAWEI
- ABB
- FNT SOFTWARE
- NLYTE SOFTWARE
- SUNBIRD SOFTWARE
- 기타 주요 기업
- CORMANT
- RF CODE
- RACKWISE
- PAESSLER
- ITRACS
- STULZ
- DEVICE42
- HYPERVIEW
- RITTAL
- PATCH MANAGER
- MANAGEENGINE
- GREENFIELD SOFTWARE
- ISPSYSTEM
- DELTA ELECTRONICS
- ZPE SYSTEMS
- MODIUS
- NETZOOM
- EKKOSENSE
- CENTEROS
- TEECUBE SOLUTIONS
- UNITEDLAYER
- RIT TECH
제14장 조사 방법론
제15장 인접 시장 및 관련 시장
- 서론
- 관련 시장
- 데이터센터 솔루션 시장
- 데이터센터 변혁 시장
제16장 부록
KSM 26.10.26The global data center infrastructure management (DCIM) market is projected to grow from USD 3.99 billion in 2026 to USD 8.42 billion by 2031, reflecting a 16.1% CAGR over the forecast period. The growing integration of artificial intelligence (AI), advanced analytics, and automation into DCIM platforms is transforming how operators monitor and manage data center infrastructure. AI-enabled capabilities support predictive maintenance, performance optimization, capacity planning, energy management, and real-time infrastructure monitoring, helping operators identify potential issues and improve resource utilization.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/USD Billion) |
| Segments | Offering, Functionality, Deployment Mode, Tier Type, Data Center Size, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, and Latin America |
The growing deployment of AI and high-density workloads is further increasing the need to optimize power, cooling, space, and equipment performance. DCIM platforms are consequently evolving from conventional monitoring tools toward intelligent infrastructure management systems that can automate operational tasks, provide predictive insights, and support data-driven decision-making. This transition is expected to strengthen demand for DCIM solutions as data center operators seek to improve efficiency, reliability, scalability, and sustainability across increasingly complex infrastructure environments.
"By offering, services will grow at the highest CAGR during the forecast period."
Services are increasingly important in the DCIM market as organizations seek specialized support for deploying, integrating, and optimizing DCIM platforms across complex data center environments. DCIM services include design and consulting, integration and deployment, and support and maintenance, helping organizations align DCIM solutions with their infrastructure requirements. As data centers become more distributed and complex, organizations require expertise to integrate DCIM platforms with IT infrastructure, power management, cooling systems, building management systems, and other monitoring platforms. Integration and deployment services are particularly relevant as enterprises adopt multi-site and hybrid infrastructure environments, while support and maintenance services help maintain system availability and performance. The growing adoption of AI-enabled DCIM, cloud-based platforms, and advanced analytics is also creating demand for implementation and integration expertise. These factors are expected to drive service adoption as organizations focus on faster deployment, effective system integration, operational continuity, and maximizing the value of DCIM investments.
"By functionality, asset management will hold the largest share during the forecast period."
Asset management is expected to account for the largest share of the DCIM market during the forecast period. Data center operators increasingly require centralized visibility into IT and facility assets to manage increasingly complex and distributed infrastructure. Asset management functionality enables organizations to maintain detailed equipment records, track asset locations and status, monitor utilization, and support lifecycle management. It also provides greater visibility into available capacity and helps operators make informed decisions about equipment deployment, replacement, and resource allocation. The growing deployment of hyperscale, colocation, enterprise, and edge data centers is increasing the number and diversity of assets that must be monitored and managed. Integrating asset management with capacity planning, environmental monitoring, and performance analytics further improves infrastructure visibility. As operators seek to optimize existing resources, reduce underutilization, and improve infrastructure planning, demand for comprehensive asset management capabilities is expected to remain strong throughout the forecast period.
"North America is expected to hold the largest market share during the forecast period."
North America is expected to hold the largest share of the DCIM market during the forecast period, supported by its established data center ecosystem, continued investment in hyperscale and colocation facilities, and the growing deployment of AI and high-density computing infrastructure. The US, in particular, has a large installed base of enterprise, hyperscale, cloud, and colocation data centers that require centralized infrastructure monitoring and management. Rising power requirements, higher rack densities, and pressure to improve energy efficiency are driving operators to adopt DCIM platforms to monitor power, cooling, capacity, environmental conditions, and asset performance. The region also has a strong presence of leading DCIM providers and data center infrastructure companies, which supports technology adoption and platform integration. In addition, the modernization of existing facilities is creating demand for DCIM solutions that integrate with BMS, EPMS, IT infrastructure, and other operational systems. These factors are expected to sustain North America's leading position as data center operators prioritize operational visibility, infrastructure efficiency, and reliable facility management.
The breakup of the profiles of the primary participants is below:
- By Company: Tier I: 33%, Tier II: 25%, and Tier III: 42%
- By Designation: C-Level Executives: 31%, Director Level: 34%, and Others: 35%
- By Region: North America: 42%, Europe: 28%, Asia Pacific: 22%, Rest of World: 8%
Note: Others include sales managers, marketing managers, and product managers
Note: The Rest of the World consists of the Middle East & Africa and Latin America
Note: Tier 1 companies have revenues of more than USD 100 million; tier 2 companies' revenue ranges from USD 10 million to USD 100 million; and tier 3 companies' revenue is less than 10 million
Source: Secondary Literature, Expert Interviews, and MarketsandMarkets Analysis
Major companies offering data center infrastructure management software and services are Schneider Electric (France), Vertiv (US), Siemens (Germany), Nlyte Software (US), Huawei (China), Johnson Controls (Ireland), Eaton (Ireland), ABB (Switzerland), Sunbird Software (US), and FNT Software (Germany).
Research coverage
This study presents an in-depth analysis of the data center infrastructure management (DCIM) market, based on market trends, potential growth in 2021, and a forecast through 2026-2031. It also provides detailed market trends, a competitive landscape, market size, forecasts, and an analysis of key players in the data center infrastructure management market. The study analyzes the growth rate and penetration of data center infrastructure management across all major regions.
Reasons to buy this report
The report will aid market leaders and new entrants by providing the following: the closest approximations of revenue for the serverless computing market and its subsegments. This study will aid stakeholders in understanding the competitive landscape; it offers more insights to position their businesses better and plan suitable go-to-market strategies. It also helps stakeholders understand the market pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of critical drivers (Growing adoption of AI and high-density data centers, Growing demand for energy-efficient solutions, Increasing demand for remote and distributed data center management), restraints (High implementation costs of DCIM solutions, Complexity and cost of deploying DCIM across heterogeneous infrastructure), opportunities (Growing investments in data center technologies, Rising adoption of edge data centers), and challenges (Concerns over data privacy and security) influencing the growth of the data center infrastructure management market.
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the data center infrastructure management market
- Market Development: In-depth understanding of upcoming technologies, research & development efforts, and new product & service releases in the data center infrastructure management market
- Market Diversification: Comprehensive details on the latest products & services, unexplored regions, recent advancements, and investments in the data center infrastructure management market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and Schneider Electric (France), Vertiv (US), Siemens (Germany), Nlyte Software (US), Huawei (China), Johnson Controls (Ireland), Eaton (Ireland), ABB (Switzerland), Sunbird Software (US), and FNT Software (Germany), among others, in the data center infrastructure management market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.2.1 INCLUSIONS AND EXCLUSIONS
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONS COVERED
- 1.3.2 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.2 DISRUPTIVE TRENDS IN SOFTWARE-DEFINED DATA CENTER MARKET
- 2.3 HIGH GROWTH SEGMENTS
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE GROWTH OPPORTUNITIES FOR PLAYERS IN DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET
- 3.2 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY OFFERING
- 3.3 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY FUNCTIONALITY
- 3.4 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY DEPLOYMENT MODE
- 3.5 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY TIER TYPE
- 3.6 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY DATA CENTER SIZE
- 3.7 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY END USER
- 3.8 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY REGION
4 MARKET OVERVIEW AND INDUSTRY TRENDS
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Growing adoption of AI and high-density data centers
- 4.2.1.2 Growing demand for energy-efficient solutions
- 4.2.1.3 Increasing demand for remote and distributed data center management
- 4.2.2 RESTRAINTS
- 4.2.2.1 High implementation costs of DCIM solutions
- 4.2.2.2 Complexity and cost of deploying DCIM across heterogeneous infrastructure
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing investments in data center technologies
- 4.2.3.2 Rising adoption of edge data centers
- 4.2.4 CHALLENGES
- 4.2.4.1 Concerns over data privacy and security
- 4.2.4.2 Lack of skilled professionals
- 4.2.4.3 Integration with legacy systems
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN THE SOFTWARE-DEFINED DATA CENTER MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.3.3 INTERCONNECTED MARKETS
- 4.3.4 CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.4.1 KEY MOVES AND STRATEGIC FOCUS
- 4.5 PORTER'S FIVE FORCES ANALYSIS
- 4.5.1 THREAT OF NEW ENTRANTS
- 4.5.2 THREAT OF SUBSTITUTES
- 4.5.3 BARGAINING POWER OF BUYERS
- 4.5.4 BARGAINING POWER OF SUPPLIERS
- 4.5.5 INTENSITY OF COMPETITIVE RIVALRY
- 4.6 MACROECONOMIC INDICATORS
- 4.6.1 INTRODUCTION
- 4.6.2 GDP TRENDS & FORECASTS
- 4.6.3 TRENDS IN GLOBAL DATA CENTER SOLUTIONS INDUSTRY
- 4.6.4 TRENDS IN GLOBAL CLOUD COMPUTING INDUSTRY
- 4.7 SUPPLY CHAIN ANALYSIS
- 4.8 ECOSYSTEM
- 4.9 PRICING ANALYSIS
- 4.9.1 AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY SOFTWARE
- 4.9.2 AVERAGE SELLING PRICE TREND, BY REGION
- 4.10 KEY CONFERENCES AND EVENTS, 2026-2027
- 4.11 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 4.12 INVESTMENT AND FUNDING SCENARIO
- 4.13 CASE STUDY ANALYSIS
- 4.13.1 CORMANT TRANSFORMED COLOCATION DATA CENTER OPERATIONS FOR EFFICIENCY AND TRANSPARENCY
- 4.13.2 RARITAN ENHANCED POWER AND COOLING MANAGEMENT AT F5 NETWORKS PRODUCT DEVELOPMENT LAB
- 4.13.3 RIT TECH'S XPEDITE TRANSFORMED BEIJING SUBWAY'S FIBER NETWORK MANAGEMENT
- 4.13.4 MORO HUB ADOPTED NETECO600 FOR UNIFIED MANAGEMENT OF DISTRIBUTED DATA CENTERS
- 4.13.5 ALL IT ROOMS ENSURED 100% SYSTEM STABILITY WITH PAESSLER PRTG NETWORK MONITOR
- 4.13.6 LEADING EDGE DATA CENTRES REVOLUTIONIZED CONNECTIVITY IN AUSTRALIAN REGION WITH SCHNEIDER ELECTRIC
- 4.13.7 COMPUTACENTER EFFECTIVELY MANAGED DATA CENTER WITH NLYTE
- 4.13.8 SUNBIRD DCIM DRIVES EFFICIENCY AND SUSTAINABILITY FOR VODAFONE
- 4.13.9 VERTIV TRANSFORMING BANKING INFRASTRUCTURE FOR CONTINUOUS AVAILABILITY
- 4.13.10 ENHANCING DATAVITA'S COLOCATION SERVICES WITH FNT'S DCIM SOLUTIONS
- 4.14 IMPACT OF 2025 US TARIFF - DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET
- 4.14.1 INTRODUCTION
- 4.14.2 KEY TARIFF RATES
- 4.14.3 PRICE IMPACT ANALYSIS
- 4.14.4 IMPACT ON COUNTRIES/REGIONS
- 4.14.4.1 US
- 4.14.4.2 Europe
- 4.14.4.3 Asia Pacific
- 4.14.5 IMPACT ON VERTICALS
- 4.14.5.1 BFSI
- 4.14.5.2 Cloud services providers & hyperscalers
- 4.14.5.3 Manufacturing
- 4.14.5.4 Government & public sector
- 4.15 TECHNOLOGY ANALYSIS
- 4.15.1 KEY TECHNOLOGIES
- 4.15.1.1 AI and ML
- 4.15.1.2 Internet of Things (IoT)
- 4.15.1.3 Big data and analytics
- 4.15.1.4 Cloud computing
- 4.15.2 COMPLEMENTARY TECHNOLOGIES
- 4.15.2.1 Building management systems
- 4.15.2.2 Security information and event management (SIEM) systems
- 4.15.2.3 Network management systems
- 4.15.2.4 Uninterruptible power supply (UPS) monitoring systems
- 4.15.3 ADJACENT TECHNOLOGIES
- 4.15.3.1 Edge computing
- 4.15.3.2 Robotic process automation
- 4.15.3.3 Hyper-converged infrastructure
- 4.15.3.4 Container orchestration platform
- 4.15.1 KEY TECHNOLOGIES
- 4.16 TECHNOLOGY/PRODUCT ROADMAP
- 4.16.1 SHORT-TERM (2026-2028) | MONITORING, INTEGRATION & AUTOMATION
- 4.16.2 MID-TERM (2028-2031) | AI-ENABLED ANALYTICS & INFRASTRUCTURE OPTIMIZATION
- 4.16.3 LONG-TERM (2031-2036+) | AUTONOMOUS, AI-DRIVEN & SELF-OPTIMIZING INFRASTRUCTURE
- 4.17 PATENT ANALYSIS
- 4.18 FUTURE APPLICATIONS
- 4.18.1 AI-DRIVEN PREDICTIVE INFRASTRUCTURE MANAGEMENT
- 4.18.2 AUTONOMOUS CAPACITY PLANNING & RESOURCE OPTIMIZATION
- 4.18.3 INTELLIGENT ENERGY & COOLING OPTIMIZATION
- 4.18.4 AI-ENABLED ASSET MONITORING & ANOMALY DETECTION
- 4.18.5 AUTOMATED INCIDENT MANAGEMENT & INFRASTRUCTURE OPERATIONS
- 4.19 IMPACT OF AI/GENERATIVE AI ON THE DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET
- 4.19.1 TOP USE CASES AND MARKET POTENTIAL
- 4.19.2 BEST PRACTICES IN DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET
- 4.19.3 CASE STUDY OF AI IMPLEMENTATION IN DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET
- 4.19.3.1 Telstra transforms data center management with Nlyte's AI-powered DCIM solution
- 4.19.4 INTERCONNECTED ADJACENCT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 4.19.5 CLIENT READINESS TO ADOPT GENERATIVE AI IN THE DATA CENTER INFRASTRUCTURE MANAGEMENT
- 4.20 REGULATORY LANDSCAPE
- 4.20.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 4.20.2 REGULATIONS, BY COUNTRY/REGION
- 4.21 DECISION-MAKING PROCESS
- 4.22 KEY STAKEHOLDERS AND BUYING CRITERIA
- 4.22.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 4.22.2 BUYING CRITERIA
- 4.23 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 4.24 UNMET NEEDS IN VARIOUS END-USER INDUSTRIES
- 4.25 MARKET PROFITABILITY
- 4.25.1 REVENUE POTENTIAL
- 4.25.2 COST DYNAMICS
- 4.25.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
- 4.26 BUSINESS MODEL ANALYSIS
- 4.26.1 PRODUCT OFFERINGS
- 4.26.2 REVENUE STREAMS
- 4.26.3 REVENUE MODEL TRENDS
- 4.26.4 CHANNELS
- 4.26.5 CUSTOMER SEGMENTS
- 4.27 DCIM SOURCES OF DATA GENERATION
- 4.27.1 IT EQUIPMENT
- 4.27.2 ELECTRICAL SYSTEMS
- 4.27.3 COOLING EQUIPMENT
- 4.27.4 ENVIRONMENTAL RESOURCES
5 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY OFFERING
- 5.1 INTRODUCTION
- 5.1.1 OFFERING: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 5.2 DCIM SOFTWARE
- 5.2.1 MONITORING
- 5.2.1.1 Optimizing data center efficiency and uptime with advanced DCIM monitoring solutions for power, cooling, and infrastructure
- 5.2.2 OPERATIONS & MANAGEMENT
- 5.2.2.1 Enhancing data center efficiency with AI-driven DCIM software for real-time monitoring and predictive maintenance
- 5.2.1 MONITORING
- 5.3 SERVICES
- 5.3.1 DESIGN & CONSULTING
- 5.3.1.1 Optimizing data center operations through strategic design and consulting services for efficiency and scalability
- 5.3.2 INTEGRATION & DEPLOYMENT
- 5.3.2.1 Enhancing data center efficiency through advanced integration and deployment services
- 5.3.3 SUPPORT & MAINTENANCE
- 5.3.3.1 Essential support and maintenance services for optimizing data center infrastructure reliability and performance
- 5.3.1 DESIGN & CONSULTING
6 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY FUNCTIONALITY
- 6.1 INTRODUCTION
- 6.1.1 FUNCTIONALITY: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 6.2 PERFORMANCE OPTIMIZATION
- 6.2.1 AI-DRIVEN PERFORMANCE OPTIMIZATION IN DCIM FOR ENERGY EFFICIENCY, COST REDUCTION, AND PREDICTIVE DIAGNOSTICS
- 6.2.2 ENERGY OPTIMIZATION
- 6.2.3 COST ANALYSIS
- 6.2.4 PREDICTIVE DIAGNOSTICS
- 6.3 ASSET MANAGEMENT
- 6.3.1 ENHANCING DATA CENTER EFFICIENCY WITH ADVANCED ASSET MANAGEMENT TO REDUCE RISKS AND OPTIMIZE OPERATIONS
- 6.3.2 INVENTORY MANAGEMENT
- 6.3.3 WORKFLOW & CHANGE MANAGEMENT
- 6.3.4 LOCATION TRACKING
- 6.3.5 POWER INFRASTRUCTURE MANAGEMENT
- 6.4 CONFIGURATION
- 6.4.1 OPTIMIZING DATA CENTER EFFICIENCY THROUGH ADVANCED CONFIGURATION TO ENABLE CAPACITY, FLOOR SPACE, AND RACK & CABINET PLANNING
- 6.4.2 CAPACITY PLANNING & RESOURCE UTILIZATION
- 6.4.3 FLOOR SPACE PLANNING
- 6.4.4 RACK & CABINET PLANNING
- 6.5 OPERATIONAL MONITORING
- 6.5.1 MAXIMIZING DATA CENTER EFFICIENCY THROUGH COMPREHENSIVE OPERATIONAL MONITORING
- 6.5.2 POWER MONITORING
- 6.5.3 ENVIRONMENTAL MONITORING
- 6.5.4 IT EQUIPMENT MONITORING
- 6.6 REPORTING & DASHBOARDS
- 6.6.1 OPTIMIZING DATA CENTER OPERATIONS WITH ADVANCED REPORTING, DASHBOARDS, AND REAL-TIME ALERTS
- 6.6.2 DATA VISUALIZATION & REPORTING
- 6.6.3 PERFORMANCE DASHBOARDS
- 6.6.4 ALERT & INCIDENT REPORTING
- 6.7 OTHER FUNCTIONALITIES
7 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY DEPLOYMENT MODE
- 7.1 INTRODUCTION
- 7.1.1 DEPLOYMENT MODE: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 7.2 ON-PREMISES
- 7.2.1 ON-PREMISE DCIM PROVIDES CONTROL, SECURITY, AND CUSTOMIZATION FOR REGULATED INDUSTRIES
- 7.3 CLOUD
- 7.3.1 INCREASING NEED FOR SCALABLE, FLEXIBLE, AND COST-EFFICIENT SOLUTIONS TO MANAGE DATA CENTER INFRASTRUCTURE
8 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY TIER TYPE
- 8.1 INTRODUCTION
- 8.1.1 TIER TYPE: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 8.2 TIER 1
- 8.2.1 ASSESSING TIER 1 DATA CENTERS FOR COST, RELIABILITY, AND SCALABILITY LIMITATIONS
- 8.3 TIER 2
- 8.3.1 NEED FOR ENHANCED INFRASTRUCTURE RELIABILITY AND REDUNDANCY TO DRIVE DEMAND
- 8.4 TIER 3
- 8.4.1 NEED FOR HIGH RELIABILITY AND DUAL POWER AND COOLING PATHS TO DRIVE DEMAND
- 8.5 TIER 4
- 8.5.1 REQUIREMENT FOR UNMATCHED RELIABILITY AND COMPLETE REDUNDANCY TO DRIVE DEMAND
9 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY DATA CENTER SIZE
- 9.1 INTRODUCTION
- 9.1.1 DATA CENTER SIZE: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 9.2 SMALL DATA CENTERS
- 9.2.1 SMALL DATA CENTERS ADOPT ENERGY-EFFICIENT, MODULAR DESIGNS TO ENHANCE PERFORMANCE AND SCALABILITY
- 9.3 MID-SIZED DATA CENTERS
- 9.3.1 MID-SIZED DATA CENTERS ENHANCE EFFICIENCY WITH ENERGY-SAVING TECHNOLOGIES AND ADVANCED DCIM SOLUTIONS
- 9.4 LARGE DATA CENTERS
- 9.4.1 LARGE DATA CENTERS OPTIMIZE EFFICIENCY AND SUSTAINABILITY WITH ADVANCED POWER SYSTEMS AND DCIM SOFTWARE
10 DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET, BY END USER
- 10.1 INTRODUCTION
- 10.1.1 END USER: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 10.2 ENTERPRISES
- 10.2.1 DCIM SOLUTIONS DRIVE ENTERPRISE EFFICIENCY WITH IMPROVED RESOURCE MANAGEMENT AND REDUCED OPERATIONAL COSTS
- 10.3 TELECOM SERVICE PROVIDERS
- 10.3.1 DCIM SOLUTIONS ENHANCE TELECOM EFFICIENCY WITH IMPROVED ENERGY USE AND REDUCED DOWNTIME
- 10.4 CLOUD SERVICE PROVIDERS
- 10.4.1 DCIM SOLUTIONS BOOST CLOUD SERVICE EFFICIENCY: FASTER LAUNCHES, COST REDUCTIONS, AND ENHANCED RELIABILITY
11 DATA CENTER INFRASTRUCTURE MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 NORTH AMERICA
- 11.2.1 NORTH AMERICA: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 11.2.2 US
- 11.2.2.1 Implementation of advanced technologies in established hubs and emerging rural regions to drive market
- 11.2.3 CANADA
- 11.2.3.1 Data center expansion drives growth amid regional energy and regulatory challenges
- 11.3 EUROPE
- 11.3.1 EUROPE: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 11.3.2 UK
- 11.3.2.1 USD 1.31 billion data center investment drives hyperscale expansion amid energy and security challenges
- 11.3.3 GERMANY
- 11.3.3.1 Data center expansion accelerates with USD 10 billion investment and regulatory changes amid infrastructure challenges
- 11.3.4 FRANCE
- 11.3.4.1 Major investments in sustainability and technology to drive market
- 11.3.5 ITALY
- 11.3.5.1 Market growth fueled by major investments, regulatory challenges, and technological innovations
- 11.3.6 REST OF EUROPE
- 11.4 ASIA PACIFIC
- 11.4.1 ASIA PACIFIC: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 11.4.2 CHINA
- 11.4.2.1 Major government investments and sustainable innovations to drive market
- 11.4.3 JAPAN
- 11.4.3.1 Major cloud and AI investments to drive market
- 11.4.4 INDIA
- 11.4.4.1 Major investments and increasing digital need to boost market
- 11.4.5 REST OF ASIA PACIFIC
- 11.5 MIDDLE EAST & AFRICA
- 11.5.1 MIDDLE EAST & AFRICA: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 11.5.2 GULF COOPERATION COUNCIL (GCC)
- 11.5.2.1 Saudi Arabia
- 11.5.2.1.1 Market growth driven by major investments and focus on energy efficiency
- 11.5.2.2 UAE
- 11.5.2.2.1 Strategic investments and government support to drive market
- 11.5.2.3 Rest of GCC
- 11.5.2.1 Saudi Arabia
- 11.5.3 SOUTH AFRICA
- 11.5.3.1 Major data center investments in Johannesburg and Cape Town to propel market growth
- 11.5.4 REST OF MIDDLE EAST & AFRICA
- 11.6 LATIN AMERICA
- 11.6.1 LATIN AMERICA: DATA CENTER INFRASTRUCTURE MANAGEMENT MARKET DRIVERS
- 11.6.2 BRAZIL
- 11.6.2.1 Major investments and infrastructure enhancements to drive market
- 11.6.3 MEXICO
- 11.6.3.1 Major tech investments and sustainability focus to drive market
- 11.6.4 REST OF LATIN AMERICA
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 12.3 MARKET SHARE ANALYSIS
- 12.4 BRAND/PRODUCT COMPARISON
- 12.4.1 SCHNEIDER ELECTRIC - ECOSTRUXURE IT
- 12.4.2 VERTIV - ENVIRONET
- 12.4.3 JOHNSON CONTROLS - METASYS DCIM MODULE
- 12.4.4 EATON - BRIGHTLAYER DCIM
- 12.4.5 SIEMENS- DESIGO CC / BUILDING X
- 12.5 REVENUE ANALYSIS
- 12.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2023
- 12.6.1 STARS
- 12.6.2 EMERGING LEADERS
- 12.6.3 PERVASIVE PLAYERS
- 12.6.4 PARTICIPANTS
- 12.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.6.5.1 Company footprint
- 12.6.5.2 Offering footprint
- 12.6.5.3 End user footprint
- 12.6.5.4 Regional footprint
- 12.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 12.7.1 PROGRESSIVE COMPANIES
- 12.7.2 RESPONSIVE COMPANIES
- 12.7.3 DYNAMIC COMPANIES
- 12.7.4 STARTING BLOCKS
- 12.7.5 COMPETITIVE BENCHMARKING: STARTUP/SMES, 2025
- 12.7.5.1 Detailed list of key startups/SMEs
- 12.7.5.2 Competitive benchmarking of startups/SMEs
- 12.8 COMPANY VALUATION AND FINANCIAL METRICS
- 12.9 COMPETITIVE SCENARIO AND TRENDS
- 12.9.1 PRODUCT LAUNCHES/ENHANCEMENTS
- 12.9.2 DEALS
13 COMPANY PROFILES
- 13.1 INTRODUCTION
- 13.2 MAJOR PLAYERS
- 13.2.1 SCHNEIDER ELECTRIC
- 13.2.1.1 Business overview
- 13.2.1.2 Products/Solutions/Services offered
- 13.2.1.3 Recent developments
- 13.2.1.3.1 Product launches/Enhancements
- 13.2.1.3.2 Deals
- 13.2.1.4 MnM view
- 13.2.1.4.1 Right to win
- 13.2.1.4.2 Strategic choices
- 13.2.1.4.3 Weaknesses and competitive threats
- 13.2.2 VERTIV
- 13.2.2.1 Business overview
- 13.2.2.2 Products/Solutions/Services offered
- 13.2.2.3 Recent developments
- 13.2.2.3.1 Product launches/Enhancements
- 13.2.2.3.2 Deals
- 13.2.2.4 MnM view
- 13.2.2.4.1 Right to win
- 13.2.2.4.2 Strategic choices
- 13.2.2.4.3 Weaknesses and competitive threats
- 13.2.3 JOHNSON CONTROLS
- 13.2.3.1 Business overview
- 13.2.3.2 Products/Solutions/Services offered
- 13.2.3.3 Recent developments
- 13.2.3.3.1 Product launches/Enhancements
- 13.2.3.3.2 Deals
- 13.2.3.4 MnM view
- 13.2.3.4.1 Right to win
- 13.2.3.4.2 Strategic choices
- 13.2.3.4.3 Weaknesses and competitive threats
- 13.2.4 SIEMENS
- 13.2.4.1 Business overview
- 13.2.4.2 Products/Solutions/Services offered
- 13.2.4.3 Recent developments
- 13.2.4.3.1 Product launches/Enhancements
- 13.2.4.3.2 Deals
- 13.2.4.4 MnM view
- 13.2.4.4.1 Right to win
- 13.2.4.4.2 Strategic choices
- 13.2.4.4.3 Weaknesses and competitive threats
- 13.2.5 EATON
- 13.2.5.1 Business overview
- 13.2.5.2 Products/Solutions/Services offered
- 13.2.5.3 Recent developments
- 13.2.5.3.1 Product launches/Enhancements
- 13.2.5.3.2 Deals
- 13.2.5.4 MNM View
- 13.2.5.4.1 Right to win
- 13.2.5.4.2 Strategic choices
- 13.2.5.4.3 Weaknesses and competitive threats
- 13.2.6 HUAWEI
- 13.2.6.1 Business overview
- 13.2.6.2 Products/Solutions/Services offered
- 13.2.6.3 Recent developments
- 13.2.6.3.1 Product launches/Enhancements
- 13.2.7 ABB
- 13.2.7.1 Business overview
- 13.2.7.2 Products/Solutions/Services offered
- 13.2.7.3 Recent developments
- 13.2.7.3.1 Deals
- 13.2.8 FNT SOFTWARE
- 13.2.8.1 Business overview
- 13.2.8.2 Products/Solutions/Services offered
- 13.2.8.3 Recent developments
- 13.2.8.3.1 Product launches/Enhancements
- 13.2.8.3.2 Deals
- 13.2.9 NLYTE SOFTWARE
- 13.2.9.1 Business overview
- 13.2.9.2 Products/Solutions/Services offered
- 13.2.9.3 Recent developments
- 13.2.9.3.1 Product launches/Enhancements
- 13.2.9.3.2 Deals
- 13.2.10 SUNBIRD SOFTWARE
- 13.2.10.1 Business overview
- 13.2.10.2 Products/Solutions/Services offered
- 13.2.10.3 Recent developments
- 13.2.10.3.1 Product launches/Enhancements
- 13.2.10.3.2 Deals
- 13.2.1 SCHNEIDER ELECTRIC
- 13.3 OTHER PLAYERS
- 13.3.1 CORMANT
- 13.3.2 RF CODE
- 13.3.3 RACKWISE
- 13.3.4 PAESSLER
- 13.3.5 ITRACS
- 13.3.6 STULZ
- 13.3.7 DEVICE42
- 13.3.8 HYPERVIEW
- 13.3.9 RITTAL
- 13.3.10 PATCH MANAGER
- 13.3.11 MANAGEENGINE
- 13.3.12 GREENFIELD SOFTWARE
- 13.3.13 ISPSYSTEM
- 13.3.14 DELTA ELECTRONICS
- 13.3.15 ZPE SYSTEMS
- 13.3.16 MODIUS
- 13.3.17 NETZOOM
- 13.3.18 EKKOSENSE
- 13.3.19 CENTEROS
- 13.3.20 TEECUBE SOLUTIONS
- 13.3.21 UNITEDLAYER
- 13.3.22 RIT TECH
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH APPROACH
- 14.1.1 SECONDARY DATA
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Breakup of primary profiles
- 14.1.2.2 Key industry insights
- 14.2 MARKET BREAKUP AND DATA TRIANGULATION
- 14.3 MARKET SIZE ESTIMATION
- 14.4 MARKET FORECAST
- 14.5 RESEARCH ASSUMPTIONS
- 14.6 RESEARCH LIMITATIONS
15 ADJACENT AND RELATED MARKETS
- 15.1 INTRODUCTION
- 15.1.1 RELATED MARKETS
- 15.2 DATA CENTER SOLUTIONS MARKET
- 15.3 DATA CENTER TRANSFORMATION MARKET
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


