

|
시장보고서
상품코드
2154195
A2L 냉매 시장 : 유형별, 화학적 특성별, 용도별, 유통 채널별, 최종사용자별, 지역별 - 세계 예측(-2031년)A2L Refrigerant Market by Type, By Chemistry, by Application, by Distribution Channel (Direct, Distributors & Wholesalers), by End User, and Region - Global Forecast to 2031 |
||||||

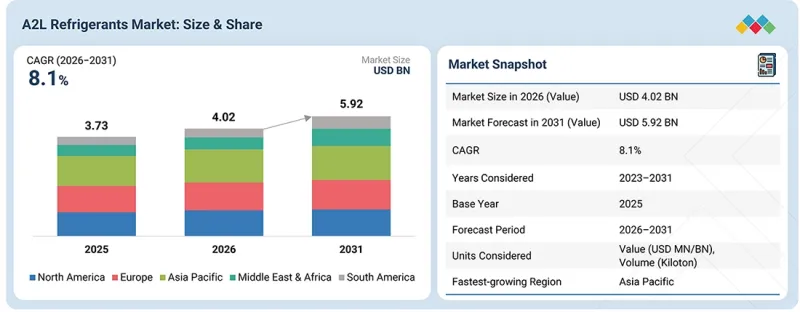
A2L 냉매 시장은 2026년 40억 2,000만 달러에서 2031년까지 59억 2,000만 달러에 달할 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 8.1%를 기록할 전망입니다.
A2L 냉매 시장은 GWP(지구 온난화 지수)가 낮은 냉매로의 전환, 환경 규제의 강화, 그리고 에너지 효율이 높은 공조·냉동 시스템에 대한 수요 증가를 배경으로 급속한 성장을 이루고 있습니다. 주요 요인으로는 공조, 냉동, 히트 펌프, 칠러 등의 용도에서 지구온난화지수가 낮은 냉매에 대한 수요가 증가하고 있다는 점을 들 수 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2023-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(백만 달러) 킬로톤 |
| 부문 | 유형, 화학적 특성, 유통 채널, 용도, 최종 이용 산업 및 지역 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카 |
GWP가 높은 HFC 냉매의 단계적 감축과 GWP가 낮은 대체 냉매의 채택 확대에 따라 R-32, R-454B, R-454A, R-454C, R-1234yf, R-1234ze 등의 A2L 냉매에 대한 수요가 발생하고 있습니다. 에너지 효율이 높은 HVAC 장비의 도입 확대와 기존 냉매로부터의 대체가 시장 성장을 더욱 뒷받침하고 있습니다. 냉매 기술은 적절한 열역학적 성능, 에너지 효율, 장비와의 호환성 및 안전성을 제공할 수 있도록 발전하고 있습니다. 누출 감지 시스템, 냉매 충전 관리, 압축기, 열교환기, 전자 제어 및 안전 시스템의 발전으로 인해 A2L 냉매 전용으로 설계된 장비의 개발이 가능해졌습니다.
“예측 기간 동안 R-454B는 A2L 냉매 시장에서 두 번째로 큰 점유율을 차지할 것으로 보입니다.”
R-454B는 공조 및 히트 펌프 용도에서 기존 냉매를 대체하는 저GWP 대체 냉매로 채택이 확대되고 있어, A2L 냉매 시장에서 두 번째로 큰 점유율을 차지하고 있습니다. R-454B는 신규 기기에 사용될 것을 염두에 두고 설계되었으며, R-410A에 비해 지구온난화지수(GWP)가 현저히 낮은 반면, 주거용 및 상업용 HVAC 시스템에 적합한 성능을 발휘합니다. 환경 규제와 HFC의 단계적 감축에 힘입어 GWP가 높은 냉매에서 R-454B로의 전환이 이루어지면서, R-454B에 대한 수요가 증가하고 있습니다. 이 냉매는 A2L 냉매에 대응하도록 설계된 신규 시스템에서 HVAC 기기 제조업체들에 의해 점점 더 많이 채택되고 있습니다. 또한, 고효율 공조 및 히트 펌프 시스템에 대한 수요 증가, 구형 장비의 교체, 그리고 A2L 대응 부품의 개발이 R-454B 부문의 성장을 뒷받침하고 있습니다.
“예측 기간 동안 A2L 냉매 시장에서 HFC/HFO 블렌드는 두 번째로 큰 점유율을 차지할 것으로 보입니다.”
HFC/HFO 블렌드는 HFC 및 HFO 성분의 성능 특성을 모두 갖추고 있으면서도 일부 기존 HFC 냉매보다 낮은 지구온난화지수(GWP)를 실현할 수 있기 때문에 A2L 냉매 시장에서 두 번째로 큰 점유율을 차지하고 있습니다. R-454A, R-454B, R-454C 등의 냉매는 공조, 냉동, 히트 펌프 용도를 위한 저GWP 대체 냉매로서 개발 및 채택이 진행되고 있습니다. 이러한 혼합 냉매는 적절한 열역학적 성능을 유지하면서, 진화하는 환경 요건을 충족하는 냉매 선택지를 기기 제조업체에 제공합니다. 고GWP 냉매로부터의 전환은 물론, 규제 압력의 고조와 에너지 효율이 높은 냉각 시스템에 대한 수요 증가가 HFC/HFO 혼합 냉매의 채택을 뒷받침하고 있습니다. 또한, A2L 냉매에 대응하는 기기 및 부품 개발이 진행됨에 따라 이러한 혼합 냉매의 응용 가능성이 확대되고 있습니다. 낮은 GWP, 적절한 시스템 성능, 그리고 차세대 HVAC 및 냉동 기기와의 호환성이 결합되어 HFC/HFO 혼합 냉매의 지속적인 성장이 기대됩니다.
“예측 기간 동안 A2L 냉매 시장에서 냉동 분야는 두 번째로 큰 용도를 차지했습니다.”
상업용 및 산업용 냉동 시스템 전반에 걸쳐 GWP가 낮은 냉매로의 전환이 진행됨에 따라, 냉동 분야는 A2L 냉매 시장에서 두 번째로 큰 용도를 차지했습니다. 규제에 따라 높은 GWP 냉매의 감축이 촉진되는 가운데, 상업용 냉동 장비, 냉장 창고, 식품 가공 및 기타 냉각 시스템과 같은 용도에서 지구 온난화 지수(GWP)가 낮은 냉매가 점점 더 많이 검토되고 있습니다. 고효율 냉동 시스템에 대한 수요 증가, 콜드체인 인프라 확충, 그리고 기존 냉매로부터의 대체가 A2L 냉매의 채택을 뒷받침하고 있습니다. 또한, 압축기, 열교환기, 제어 장치, 누출 감지 장치, 안전 시스템 등의 기술 발전으로 인해 냉동 기기 제조업체는 저가연성 냉매에 적합한 시스템을 개발할 수 있게 되었습니다. 에너지 효율이 높은 냉동 장비에 대한 투자 증가와 끊임없이 변화하는 환경 요건 준수의 필요성이 냉동 분야에서 A2L 냉매의 사용을 더욱 촉진할 것으로 예상됩니다.
“예측 기간 동안 북미 시장은 A2L 냉매 시장에서 두 번째로 큰 규모를 차지할 것입니다.”
북미는 저GWP 냉매로의 전환, 확립된 HVAC 인프라, 그리고 A2L 대응 공조·히트 펌프 기기의 채택 확대에 힘입어 A2L 냉매 시장에서 2위 규모를 자랑하는 지역입니다. 미국은 공조·냉동 기기의 설치 대수가 많고, 저GWP 대체 냉매에 대한 수요가 증가하고 있어 이 지역의 주요 시장으로 자리 잡고 있습니다. 고GWP 냉매 사용 감축을 목적으로 한 규제 조치로 인해, 기기 제조사와 최종사용자는 A2L 냉매로의 전환을 촉진받고 있습니다. 또한, 이 지역에는 주요 냉매 제조사, HVAC 기기 제조사, 그리고 확립된 유통 네트워크가 존재하며, 이것이 시장 발전에 기여하고 있습니다. 에너지 효율이 높은 냉각 시스템에 대한 수요 증가와 기존 냉매의 대체도 시장 성장을 더욱 뒷받침하고 있습니다. 게다가 A2L 대응 장비, 누출 감지 기술, 안전 제어 장치 및 시스템 구성요소의 개발이 지속되고 있으며, 이는 저가연성 냉매로의 전환을 촉진하고 있습니다. 아시아태평양이 시장 성장을 주도하는 한편, 북미는 규제 체계, 확립된 HVAC 시장, 강력한 제조 역량, 그리고 저GWP 냉매 기술에 대한 지속적인 투자 덕분에 두 번째로 큰 규모를 자랑하는 지역이 되었습니다.
여러 부문 및 하위 부문의 시장 규모를 파악하고 검증하며, 2차 조사를 통해 수집한 정보를 뒷받침하기 위해 광범위한 1차 인터뷰가 실시되었습니다.
1차 인터뷰의 내역은 다음과 같습니다:
- 기업 유형별 : Tier 1 : 40%, Tier 2 : 30%, Tier 3 : 30%
- 직책별 : 이사 : 30%, 관리자 : 20%, 기타 : 50%
- 지역별 : 아시아태평양 : 40%, 유럽 : 10%, 북미 : 20%, 중동 및 아프리카 : 20%, 남미 : 10%
본 조사에서는 A2L 냉매 시장의 주요 기업들에 대해 기업 개요, 최근 동향 및 주요 시장 전략을 포함한 상세한 경쟁 분석을 수록하고 있습니다.
조사 범위
본 시장 조사는 A2L 냉매 시장의 다양한 부문을 대상으로 합니다. 본 조사는 종류, 화학적 성질, 용도, 유통 채널, 최종 이용 산업 및 지역을 기준으로 각 부문의 시장 규모와 성장 잠재력을 추정하는 것을 목적으로 합니다. 또한, 본 조사에서는 시장의 주요 기업에 대한 상세한 경쟁 분석, 각 기업 개요, 제품 및 사업 제공 내용에 관한 주요 관찰 사항, 각 기업이 시행한 최근 동향, 그리고 A2L 냉매 시장에서 입지를 강화하기 위해 채택한 주요 성장 전략에 대해서도 다루고 있습니다.
본 보고서를 구매할 때의 주요 이점
본 보고서는 이 시장의 선도 기업 및 신규 진입 기업이 A2L 냉매 시장 전체와 그 부문·하위 부문의 매출액에 대해 가장 정확한 추정치를 파악하는 데 도움이 될 것으로 기대됩니다. 또한 이해관계자가 시장 상황을 이해하고, 자사의 사업 위치를 향상시키기 위한 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데 도움이 될 것으로 예상됩니다. 아울러 본 보고서는 이해관계자가 시장 동향을 파악할 수 있도록 지원하는 것을 목적으로 하며, 주요 시장 촉진요인, 제약, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 주요 촉진요인(GWP 값이 높은 HFC 냉매의 단계적 감축, 에너지 효율이 높은 냉각 시스템에 대한 수요 증가, 히트 펌프 및 공조 장비의 채택 확대), 제약요인(경미한 가연성 및 이와 관련된 안전 요건, 장비 재설계 및 개조에 따른 제약), 기회(신흥 시장에서의 A2L 냉매 보급 확대, 히트 펌프에 대한 A2L 냉매 채택 확대, 첨단 A2L 대응 HVAC 시스템 개발), 그리고 과제(진화하는 안전 기준 및 규제 준수, 기술자의 전문 지식 부족 및 교육 요건)에 대한 인사이트를 제공합니다.
- 제품 개발/혁신 : A2L 냉매 시장의 향후 기술, 연구 개발 활동 및 제품·서비스 출시에 관한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보 - 본 보고서는 다양한 지역의 A2L 냉매 시장을 분석하고 있습니다
시장 다각화 : A2L 냉매 시장의 신제품·서비스, 미개척 지역, 최근 동향 및 투자에 관한 종합적인 정보
- 경쟁 분석 : 주요 기업의 시장 점유율, 성장 전략, 서비스 제공 내용에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- A2L 냉매 시장에서 사업자에게 매력적인 비즈니스 기회
- A2L 냉매 시장 : 유형별
- A2L 냉매 시장 : 화학 조성별
- A2L 냉매 시장 : 용도별
- A2L 냉매 시장 : 유통 채널별
- A2L 냉매 시장 : 최종 이용 산업별
- A2L 냉매 시장 : 국가별
제4장 시장 개요
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- A2L 냉매 시장의 미충족 수요
- 미개척 시장의 기회
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
- 주요 동향 및 전략적 초점
제5장 업계 동향
- Porter's Five Forces 분석
- 공급업체의 협상력
- 구매자의 협상력
- 대체품의 위협
- 신규 진입자의 위협
- 경쟁 기업 간의 적대 관계의 격렬함
- 밸류체인 분석
- 원자재·부품 공급업체
- A2L 냉매 제조사/기술 제공업체
- OEM, 장비 제조사 및 서비스 제공업체
- 최종사용자
- 생태계 분석
- 가격 분석
- 지역별 평균 판매 가격 동향(2023-2025년)
- A2L 냉매 가격 동향(최종 이용 산업별, 2023-2025년)
- 거시경제 전망
- 세계 GDP 동향
- A2L 냉매 시장에 대한 미국 관세의 영향
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가·지역별 영향
- 최종 이용 산업에 미치는 영향
- 무역 분석
- 수입 시나리오(HS 코드 290342)
- 수출 시나리오(HS 코드 290342)
- 수입 시나리오(HS 코드 290351)
- 수출 시나리오(HS 코드 290351)
- 수입 시나리오(HS 코드 382763)
- 수출 시나리오(HS 코드 382763)
- 고객의 비즈니스에 영향을 미치는 동향/혼란 요인
- 투자 및 자금 조달 시나리오
- 사례 분석
- BUSTAMANTE REFRIGERATION, 미국 애리조나주 최초의 A2L 냉동 창고에 ‘옵티온 XL20(R-454C)’ 도입
- HONEYWELL과 KMW, 독일 엘크스레벤에 위치한 EDEKA에 비용 대비 효율이 높고 지속가능한 ‘솔스티스 L40X(R-455A)’ 솔루션을 도입
- ASDA, 영국 BOOTLE SUPERMARKET에서 R-744 CO₂ 시스템을 대체하기 위해 ‘OPTEON XL40(R-454A)’ 도입
- 2026-2027년 주요 컨퍼런스 및 행사
제6장 기술의 진보, AI의 영향, 특허, 혁신 및 미래의 응용
- 기술 분석
- 주요 기술
- 보완 기술
- 기술·제품 로드맵
- 단기(2025-2027년) | 저GWP 냉매의 상용화 및 시스템 적용
- 중기(2027-2030년) | 첨단 저GWP 냉매 및 통합형 안전 기술
- 장기(2030-2035년 이후) | 차세대 냉매 및 지능형 냉매 관리
- 특허 분석
- 특허의 법적 현황
- 관할권 분석
- 향후 용도
- 주거용 및 상업용 공조용 저 GWP A2L 냉매
- HFO 계열 및 첨단 HFC/HFO A2L 냉매 블렌드
- A2L용 누출 감지, 안전성 및 저충전량 시스템 기술
- A2L 대응 기기, 부품 및 디지털 냉매 관리
- AI/범용 AI가 A2L 냉매 시장에 미치는 영향
- A2L 냉매의 주요 사용 사례 및 시장 잠재력
- A2L 냉매 처리의 모범 사례
- A2L 냉매 시장에서 AI 도입 사례 연구
- 상호 연계되는 인접 생태계와 시장 참여자에 미치는 영향
- A2L 냉매 시장에서 생성형 AI 도입에 대한 고객의 준비 현황
제7장 지속가능성과 규제 현황
- 지역별 규제 및 규정 준수
- 규제 기관, 정부 기관 및 기타 조직
- 업계 표준
- 규제 정책 및 지속가능성 이니셔티브의 영향
- 인증, 표시 및 환경 기준
제8장 고객 현황 및 구매 행동
- 의사결정 과정
- 주요 이해관계자와 구매 기준
- 구매 과정의 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 각 최종 이용 산업별 미충족 수요
- 시장의 수익성
- 수익 창출 가능성
- 비용 동향
- 주요 최종 이용 산업에서의 이익률 향상 기회
제9장 A2L 냉매 시장 : 유형별
- R-32
- R-454B
- R-454C
- R-1234YF
- R-1234ZE
- R-454A
- 기타 유형
제10장 A2L 냉매 시장 : 화학적 성질별
- HFC
- HFO
- HFC/HFO 혼합물
제11장 A2L 냉매 시장 : 용도별
- 공조
- 냉장
- 히트 펌프
- 칠러
- 기타 용도
제12장 A2L 냉매 시장 : 유통 채널별
- 직접 판매(OEM)
- 판매 대리점 및 도매업체
- 기타
제13장 A2L 냉매 시장 : 최종 이용 산업별
- 주거용
- 상업용
- 자동차
- 데이터센터
- 제약
- 기타 최종 이용 산업
제14장 A2L 냉매 시장 : 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 프랑스
- 영국
- 이탈리아
- 스페인
- 기타 유럽
- 남미
- 브라질
- 아르헨티나
- 기타 남미
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 기타 아시아태평양
- 중동 및 아프리카
- GCC
- 기타 중동 및 아프리카
제15장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점, 2023-2026년
- 수익 분석, 2021-2025년
- 시장 점유율 분석(2025년)
- 제품 비교
- 기업 평가 매트릭스 : 주요 기업, 2025년
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹 : 스타트업/중소기업, 2025년
- 기업 평가 및 재무 지표
- 재무 지표
- 기업 가치 평가
- 경쟁 시나리오
- 제품 출시
- 거래
- 사업 확장
제16장 기업 개요
- 주요 기업
- THE CHEMOURS COMPANY
- SOLSTICE ADVANCED MATERIALS
- DONGYUE
- ARKEMA
- DAIKIN INDUSTRIES LTD.
- ZHEJIANG JUHUA
- ZHEJIANG SANMEI CHEMICAL
- ZHEJIANG YONGHE REFRIGERANT CO., LTD.
- ORBIA
- GUJARAT FLUOROCHEMICALS
- NAVIN FLUORINE INTERNATIONAL LIMITED
- 기타 주요 기업
- SRF LIMITED
- HARP INTERNATIONAL
- GAS SERVEI S.A.
- ZHEJIANG TURN YUAN CHEMICAL CO., LTD.
- JINHUA SLIHE CHEMICAL CO., LTD.
- HANGZHOU ICETOP REFRIGERATION CO., LTD.
- ZHANGZHOU RONGQIANG CHEMICAL CO., LTD.
- ZHEJIANG ZHONGLAN REFRIGERATION TECHNOLOGY CO., LTD.
- ZHEJIANG FOTECH INTERNATIONAL
- JIANGSU MEILAN CHEMICAL
- SHANDONG HUAAN NEW MATERIAL
- ZHEJIANG ZHONGLAN FLUORINE CHEMICAL
- SHANDONG YUEAN
- CHANGSHU 3F ZHONGHAO NEW CHEMICAL MATERIALS : COMPANY OVERVIEW
제17장 조사 방법
제18장 부록
KSM 26.10.29The A2L refrigerants market is projected to reach USD 5.92 billion by 2031 from USD 4.02 billion in 2026, at a CAGR of 8.1% during the forecast period. The A2L refrigerants market is experiencing rapid growth as a result of the transition toward lower-GWP refrigerants, increasingly stringent environmental regulations, and rising demand for energy-efficient air-conditioning and refrigeration systems. Major factors include the need for refrigerants with lower global warming potential for applications such as air conditioning, refrigeration, heat pumps, and chillers.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) Volume (Kiloton) |
| Segments | Type, Chemistry, Distribution Channel, Application, End-use Industry, and Region |
| Regions covered | North America, Europe, Asia Pacific, South America, and Middle East & Africa |
The phase-down of high-GWP HFC refrigerants and increasing adoption of lower-GWP alternatives are creating demand for A2L refrigerants such as R-32, R-454B, R-454A, R-454C, R-1234yf, and R-1234ze. The growing deployment of energy-efficient HVAC equipment and replacement of conventional refrigerants are further supporting market growth. Refrigerant technologies are advancing to provide suitable thermodynamic performance, energy efficiency, equipment compatibility, and safety characteristics. Advances in leak detection systems, refrigerant charge management, compressors, heat exchangers, electronic controls, and safety systems are enabling the development of equipment specifically designed for A2L refrigerants.
"R-454B accounts for the second-largest type in the A2L refrigerants market during the forecast period."
R-454B accounts for the second-largest type in the A2L refrigerants market based on its increasing adoption as a lower-GWP alternative to conventional refrigerants in air-conditioning and heat pump applications. R-454B is designed for use in new equipment and offers a substantially lower global warming potential than R-410A while providing suitable performance for residential and commercial HVAC systems. The transition away from higher-GWP refrigerants, supported by environmental regulations and the phase-down of HFCs, is increasing demand for R-454B. The refrigerant is increasingly being adopted by HVAC equipment manufacturers for new systems designed to accommodate A2L refrigerants. In addition, growing demand for energy-efficient air-conditioning and heat pump systems, replacement of legacy equipment, and development of A2L-compatible components are supporting the expansion of the R-454B segment.
"HFC/HFO blends account for the second-largest chemistry in the A2L refrigerants market during the forecast period."
HFC/HFO blends account for the second-largest chemistry in the A2L refrigerants market due to their ability to combine the performance characteristics of HFC and HFO components while achieving lower global warming potential than several conventional HFC refrigerants. Refrigerants such as R-454A, R-454B, and R-454C are being developed and adopted as lower-GWP alternatives for air-conditioning, refrigeration, and heat pump applications. These blends provide equipment manufacturers with refrigerant options that can meet evolving environmental requirements while maintaining suitable thermodynamic performance. The transition away from high-GWP refrigerants, together with increasing regulatory pressure and demand for energy-efficient cooling systems, is supporting the adoption of HFC/HFO blends. In addition, ongoing development of equipment and components compatible with A2L refrigerants is expanding the application potential of these blends. The combination of lower GWP, suitable system performance, and compatibility with next-generation HVAC and refrigeration equipment is expected to support continued growth of HFC/HFO blends.
"Refrigeration accounted for the second-largest application in the A2L refrigerants market during the forecast period."
Refrigeration accounted for the second-largest application in the A2L refrigerants market due to the increasing transition toward lower-GWP refrigerants across commercial and industrial refrigeration systems. Refrigerants with lower global warming potential are increasingly being considered for applications such as commercial refrigeration equipment, cold storage, food processing, and other cooling systems as regulations encourage the reduction of high-GWP refrigerants. The growing demand for efficient refrigeration systems, expansion of cold-chain infrastructure, and replacement of conventional refrigerants are supporting the adoption of A2L refrigerants. Advances in compressors, heat exchangers, controls, leak detection, and safety systems are also enabling refrigeration equipment manufacturers to develop systems suitable for mildly flammable refrigerants. Increasing investment in energy-efficient refrigeration equipment and the need to comply with evolving environmental requirements are expected to further support the use of A2L refrigerants in refrigeration applications.
"The North America market is the second-largest region in the A2L refrigerants market during the forecast period."
North America is the second-largest region in the A2L refrigerants market, supported by the transition toward lower-GWP refrigerants, established HVAC infrastructure, and increasing adoption of A2L-compatible air-conditioning and heat pump equipment. The US represents a major market in the region due to its large installed base of air-conditioning and refrigeration equipment and increasing demand for lower-GWP alternatives. Regulatory measures aimed at reducing the use of high-GWP refrigerants are encouraging equipment manufacturers and end users to transition toward A2L refrigerants. The region also benefits from the presence of major refrigerant manufacturers, HVAC equipment manufacturers, and established distribution networks. Increasing demand for energy-efficient cooling systems and replacement of legacy refrigerants is further supporting market growth. In addition, ongoing development of A2L-compatible equipment, leak detection technologies, safety controls, and system components is supporting the transition toward mildly flammable refrigerants. While Asia Pacific is leading in market growth, North America is the second-largest region due to its regulatory framework, established HVAC market, strong manufacturing capabilities, and continued investment in lower-GWP refrigerant technologies.
Extensive primary interviews were conducted to determine and verify the market size for several segments and subsegments, and to validate the information gathered through secondary research.
The breakdown of primary interviews is given below:
- By Company Type: Tier 1: 40%, Tier 2: 30%, and Tier 3: 30%
- By Designation: Directors: 30%, Managers: 20%, and Others: 50%
- By Region: Asia Pacific: 40%, Europe: 10%, North America: 20%, Middle East & Africa 20%, and South America: 10%
Chemours (US), Solstice Advanced Materials (US), Dongyue Group (China), Arkema (France), Daikin Chemicals (Japan), Zhejiang Juhua (China), Zhejiang Sanmei Chemical (China), Zhejiang Yonghe (China), Gujarat Fluorochemicals (India), Orbia (Mexico), and Navin Fluorine (India), among others, are some of the key players in the A2L Refrigerants market.
The study includes an in-depth competitive analysis of these key players in the A2L Refrigerants market, with their company profiles, recent developments, and key market strategies.
Research Coverage
The market study covers the A2L refrigerants market across various segments. It aims to estimate the market size and the growth potential of this market across different segments based on type, chemistry, application, distribution channel, end-use industry, and region. The study also includes an in-depth competitive analysis of key players in the market, their company profiles, key observations related to their products and business offerings, recent developments undertaken by them, and key growth strategies adopted by them to improve their position in the A2L refrigerants market.
Key Benefits of Buying the Report
The report is expected to help the leaders/new entrants in this market share the closest approximations of the revenue numbers of the overall A2L Refrigerants market and its segments and sub-segments. This report is projected to help stakeholders understand the competitive landscape of the market, gain insights to improve the position of their businesses, and plan suitable go-to-market strategies. The report also aims to help stakeholders understand the pulse of the market and provides them with information on the key market drivers, restraints, challenges, and opportunities.
The report provides insights on the following pointers:
- Analysis of key drivers (phase-down of high-GWP HFC refrigerants, increasing demand for energy-efficient cooling systems, growing adoption of heat pumps and air-conditioning equipment), restraints (mild flammability and associated safety requirements, equipment redesign and retrofit limitations), opportunities (expansion of A2L refrigerants in emerging markets, growing adoption of A2L refrigerants in heat pumps, development of advanced A2L-compatible HVAC systems), and challenges (compliance with evolving safety standards and regulations, limited technician expertise and training requirements).
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and product & service launches in the A2L refrigerants market
- Market Development: Comprehensive information about lucrative markets - the report analyses the A2L refrigerants market across varied regions
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the A2L refrigerants market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players like Chemours (US), Solstice Advanced Materials (US), Dongyue Group (China), Arkema (France), Daikin Chemicals (Japan), Zhejiang Juhua (China), Zhejiang Sanmei Chemical (China), Zhejiang Yonghe (China), Gujarat Fluorochemicals (India), Orbia (Mexico), and Navin Fluorine (India), among others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS OF STUDY
- 1.3.3 MARKET DEFINITION AND INCLUSIONS, BY TYPE
- 1.3.4 MARKET DEFINITION AND INCLUSIONS, BY CHEMISTRY
- 1.3.5 MARKET DEFINITION AND INCLUSIONS, BY APPLICATION
- 1.3.6 MARKET DEFINITION AND INCLUSIONS, BY DISTRIBUTION CHANNEL
- 1.3.7 MARKET DEFINITION AND INCLUSIONS, BY END-USE INDUSTRY
- 1.3.8 YEARS CONSIDERED
- 1.3.9 CURRENCY CONSIDERED
- 1.3.10 UNIT CONSIDERED
- 1.4 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN A2L REFRIGERANTS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN A2L REFRIGERANTS MARKET
- 3.2 A2L REFRIGERANTS MARKET, BY TYPE
- 3.3 A2L REFRIGERANTS MARKET, BY CHEMISTRY
- 3.4 A2L REFRIGERANTS MARKET, BY APPLICATION
- 3.5 A2L REFRIGERANTS MARKET, BY DISTRIBUTION CHANNEL
- 3.6 A2L REFRIGERANTS MARKET, BY END-USE INDUSTRY
- 3.7 A2L REFRIGERANTS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Stringent HFC phase-down regulations
- 4.2.1.2 Growing demand for energy-efficient cooling
- 4.2.1.3 OEM transition toward A2L-compatible equipment
- 4.2.2 RESTRAINTS
- 4.2.2.1 High equipment conversion costs
- 4.2.2.2 Limited technician readiness
- 4.2.2.3 Refrigerant and equipment availability
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Rapid replacement of high-GWP refrigerants
- 4.2.3.2 Expansion of heat pump applications
- 4.2.3.3 Emergence of new A2L refrigerant blends
- 4.2.4 CHALLENGES
- 4.2.4.1 Flammability-related safety requirements
- 4.2.4.2 Regulatory fragmentation
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS IN A2L REFRIGERANTS MARKET
- 4.3.1 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 VALUE CHAIN ANALYSIS
- 5.2.1 RAW MATERIAL & COMPONENT SUPPLIERS
- 5.2.2 A2L REFRIGERANT MANUFACTURERS/TECHNOLOGY PROVIDERS
- 5.2.3 OEM, EQUIPMENT MANUFACTURING, AND SERVICE PROVIDERS
- 5.2.4 END USERS
- 5.3 ECOSYSTEM ANALYSIS
- 5.4 PRICING ANALYSIS
- 5.4.1 AVERAGE SELLING PRICE TREND, BY REGION, 2023-2025
- 5.4.2 PRICING TREND OF A2L REFRIGERANTS, BY END-USE INDUSTRY, 2023-2025
- 5.5 MACROECONOMIC OUTLOOK
- 5.5.1 GLOBAL GDP TRENDS
- 5.6 IMPACT OF US TARIFFS ON A2L REFRIGERANTS MARKET
- 5.6.1 INTRODUCTION
- 5.6.2 KEY TARIFF RATES
- 5.6.3 PRICE IMPACT ANALYSIS
- 5.6.4 IMPACT ON COUNTRIES/REGIONS
- 5.6.4.1 US
- 5.6.4.2 Europe
- 5.6.4.3 Asia Pacific
- 5.6.5 IMPACT ON END-USE INDUSTRIES
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 290342)
- 5.7.2 EXPORT SCENARIO (HS CODE 290342)
- 5.7.3 IMPORT SCENARIO (HS CODE 290351)
- 5.7.4 EXPORT SCENARIO (HS CODE 290351)
- 5.7.5 IMPORT SCENARIO (HS CODE 382763)
- 5.7.6 EXPORT SCENARIO (HS CODE 382763)
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 BUSTAMANTE REFRIGERATION IMPLEMENTS OPTEON XL20 (R-454C) FOR FIRST A2L COLD STORAGE INSTALLATION IN ARIZONA, US
- 5.10.2 HONEYWELL AND KMW EQUIP EDEKA WITH COST-EFFECTIVE AND SUSTAINABLE SOLSTICE L40X (R-455A) SOLUTION, ERXLEBEN, GERMANY
- 5.10.3 ASDA IMPLEMENTS OPTEON XL40 (R-454A) TO REPLACE R-744 CO2 SYSTEM AT BOOTLE SUPERMARKET, UK
- 5.11 KEY CONFERENCES AND EVENTS, 2026-2027
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Low-GWP A2L Refrigerant Formulation
- 6.1.1.2 HFO-Based A2L Refrigerant Technology
- 6.1.1.3 A2L Refrigerant Blending Technology
- 6.1.2 COMPLEMENTARY TECHNOLOGIES
- 6.1.2.1 Refrigerant Recovery, Recycling, and Reclamation
- 6.1.2.2 A2L-Compatible Compressors and Components
- 6.1.2.3 A2L-Compatible Lubricants and Materials
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.2.1 SHORT TERM (2025-2027) | LOW-GWP REFRIGERANT COMMERCIALIZATION & SYSTEM ADAPTATION
- 6.2.2 MID-TERM (2027-2030) | ADVANCED LOW-GWP REFRIGERANTS & INTEGRATED SAFETY TECHNOLOGIES
- 6.2.3 LONG TERM (2030-2035+) | NEXT-GENERATION REFRIGERANTS & INTELLIGENT REFRIGERANT MANAGEMENT
- 6.3 PATENT ANALYSIS
- 6.3.1 LEGAL STATUS OF PATENTS
- 6.3.2 JURISDICTION ANALYSIS
- 6.4 FUTURE APPLICATIONS
- 6.4.1 LOW-GWP A2L REFRIGERANTS FOR RESIDENTIAL & COMMERCIAL AIR CONDITIONING
- 6.4.2 HFO-BASED & ADVANCED HFC/HFO A2L REFRIGERANT BLENDS
- 6.4.3 A2L LEAK DETECTION, SAFETY & LOW-CHARGE SYSTEM TECHNOLOGIES
- 6.4.4 A2L-COMPATIBLE EQUIPMENT, COMPONENTS & DIGITAL REFRIGERANT MANAGEMENT
- 6.5 IMPACT OF AI/GEN AI ON A2L REFRIGERANTS MARKET
- 6.5.1 TOP USE CASES AND MARKET POTENTIAL OF A2L REFRIGERANTS
- 6.5.2 BEST PRACTICES IN A2L REFRIGERANTS PROCESSING
- 6.5.3 CASE STUDIES OF AI IMPLEMENTATION IN A2L REFRIGERANTS MARKET
- 6.5.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN A2L REFRIGERANTS MARKET
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES
- 7.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYING BEHAVIOUR
- 8.1 INTRODUCTION
- 8.2 DECISION-MAKING PROCESS
- 8.3 KEY STAKEHOLDERS & BUYING CRITERIA
- 8.3.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.3.2 BUYING CRITERIA
- 8.4 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.5 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.6 MARKET PROFITABILITY
- 8.6.1 REVENUE POTENTIAL
- 8.6.2 COST DYNAMICS
- 8.6.3 MARGIN OPPORTUNITIES IN KEY END-USE INDUSTRIES
9 A2L REFRIGERANTS MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 R-32
- 9.2.1 R-32 LEADING ESTABLISHED HIGH-VOLUME A2L TRANSITION
- 9.3 R-454B
- 9.3.1 R-454B DRIVING R-410A REPLACEMENT PATHWAY
- 9.4 R-454C
- 9.4.1 R-454C STRENGTHENING LOW-GWP REFRIGERATION TRANSITION
- 9.5 R-1234YF
- 9.5.1 R-1234YF DOMINATES AUTOMOTIVE A2L PATHWAY
- 9.6 R-1234ZE
- 9.6.1 R-1234ZE TARGETS SPECIALIZED LOW-GWP COOLING APPLICATIONS
- 9.7 R-454A
- 9.7.1 R-454A EXPANDS IN COMMERCIAL REFRIGERATION APPLICATIONS
- 9.8 OTHER TYPES
10 A2L REFRIGERANTS MARKET, BY CHEMISTRY
- 10.1 INTRODUCTION
- 10.2 HFC
- 10.2.1 OFFERS REGULATORY COMPLIANCE, ESTABLISHED EQUIPMENT TECHNOLOGY, OEM FAMILIARITY, AND ENERGY EFFICIENCY
- 10.3 HFO
- 10.3.1 ADOPTION IN APPLICATIONS DEMANDING ULTRA-LOW GWP TO DRIVE GROWTH
- 10.4 HFC/HFO BLEND
- 10.4.1 OFFERS FLEXIBLE TRANSITION PATHWAY BETWEEN PERFORMANCE AND GWP REDUCTION
11 A2L REFRIGERANTS MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 AIR CONDITIONING
- 11.2.1 TRANSITION FROM R-410A TO LOWER-GWP REFRIGERANTS TO DRIVE MARKET GROWTH
- 11.3 REFRIGERATION
- 11.3.1 TRANSITION TOWARD LOWER-GWP A2L SOLUTIONS TO DRIVE ADOPTION
- 11.4 HEAT PUMPS
- 11.4.1 INCREASING HEATING ELECTRIFICATION DRIVING MARKET GROWTH
- 11.5 CHILLERS
- 11.5.1 DEMAND FOR LOW-GWP REFRIGERANTS TO INCREASE ADOPTION
- 11.6 OTHER APPLICATIONS
12 A2L REFRIGERANTS MARKET, BY DISTRIBUTION CHANNEL
- 12.1 INTRODUCTION
- 12.2 DIRECT (OEM)
- 12.2.1 DIRECT OEM DEMAND ACCELERATING AS MANUFACTURERS EMBED A2L REFRIGERANTS INTO NEW EQUIPMENT PLATFORMS
- 12.3 DISTRIBUTORS & WHOLESALERS
- 12.3.1 INCREASING INSTALLED BASE OF A2L EQUIPMENT TO SUPPORT MARKET GROWTH
- 12.4 OTHERS
13 A2L REFRIGERANTS MARKET, BY END-USE INDUSTRY
- 13.1 INTRODUCTION
- 13.2 RESIDENTIAL
- 13.2.1 STRONG DEMAND FOR R-32 IN RESIDENTIAL AIR CONDITIONING IN ASIA PACIFIC TO DRIVE MARKET
- 13.3 COMMERCIAL
- 13.3.1 REPLACEMENT OF HIGH-GWP REFRIGERANTS DRIVING MARKET GROWTH
- 13.4 AUTOMOTIVE
- 13.4.1 INCREASING ADOPTION OF R-1234YF TO SUPPORT MARKET EXPANSION
- 13.5 DATA CENTERS
- 13.5.1 INCREASING COOLING REQUIREMENTS FOR AI-DRIVEN COMPUTING TO FUEL DEMAND
- 13.6 PHARMACEUTICAL
- 13.6.1 TRANSITION TOWARD LOWER-GWP REFRIGERANTS CREATING OPPORTUNITIES FOR A2L REFRIGERANTS
- 13.7 OTHER END-USE INDUSTRIES
14 A2L REFRIGERANTS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Stringent environmental regulations and continued investment in emission control infrastructure to support demand
- 14.2.2 CANADA
- 14.2.2.1 Stringent environmental standards and modernization of power and industrial infrastructure to support market growth
- 14.2.3 MEXICO
- 14.2.3.1 Industrial modernization and environmental regulations to fuel market growth
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Strong industrial base and stringent emission control requirements to facilitate market growth
- 14.3.2 FRANCE
- 14.3.2.1 Continued industrial activity and brownfield projects to stimulate market growth
- 14.3.3 UK
- 14.3.3.1 Stringent emission standards and established industrial base to contribute to market growth
- 14.3.4 ITALY
- 14.3.4.1 Rising need for brownfield retrofits and established cement industry to boost demand
- 14.3.5 SPAIN
- 14.3.5.1 Emphasis on industrial decarbonization, energy efficiency, renewable energy to accelerate market growth
- 14.3.6 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 SOUTH AMERICA
- 14.4.1 BRAZIL
- 14.4.1.1 Established thermal power capacity to drive market
- 14.4.2 ARGENTINA
- 14.4.2.1 Thermal power generation efforts to create growth opportunities
- 14.4.3 REST OF SOUTH AMERICA
- 14.4.1 BRAZIL
- 14.5 ASIA PACIFIC
- 14.5.1 CHINA
- 14.5.1.1 Strong focus on low-GWP refrigerant transition and sustainable cooling to drive market
- 14.5.2 JAPAN
- 14.5.2.1 Strong focus on refrigerant transition and energy-efficient cooling to create growth opportunities
- 14.5.3 INDIA
- 14.5.3.1 Rising cooling demand and HFC phasedown initiatives to foster market growth
- 14.5.4 SOUTH KOREA
- 14.5.4.1 Stringent HFC phasedown measures and advanced cooling infrastructure to contribute to market growth
- 14.5.5 REST OF ASIA PACIFIC
- 14.5.1 CHINA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 GCC
- 14.6.1.1 Saudi Arabia
- 14.6.1.1.1 High cooling demand and HFC phasedown measures to support A2L refrigerant adoption
- 14.6.1.2 UAE
- 14.6.1.2.1 High cooling demand and HFC phasedown measures to support A2L refrigerant adoption
- 14.6.1.3 Rest of GCC
- 14.6.1.4 South Africa
- 14.6.1.4.1 HFC phasedown and expansion of low-GWP cooling technologies to support A2L refrigerant adoption
- 14.6.1.1 Saudi Arabia
- 14.6.2 REST OF MIDDLE EAST & AFRICA
- 14.6.1 GCC
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER COMPETITIVE STRATEGIES/ RIGHT TO WIN, 2023-2026
- 15.3 REVENUE ANALYSIS, 2021-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 PRODUCT COMPARISON
- 15.6 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.6.1 STARS
- 15.6.2 EMERGING LEADERS
- 15.6.3 PERVASIVE PLAYERS
- 15.6.4 PARTICIPANTS
- 15.6.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.6.5.1 Company footprint
- 15.6.5.2 Region footprint
- 15.6.5.3 Type footprint
- 15.6.5.4 Chemistry footprint
- 15.6.5.5 Application footprint
- 15.6.5.6 Distribution channel footprint
- 15.6.5.7 End-use industry footprint
- 15.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.7.1 PROGRESSIVE COMPANIES
- 15.7.2 RESPONSIVE COMPANIES
- 15.7.3 DYNAMIC COMPANIES
- 15.7.4 STARTING BLOCKS
- 15.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.7.5.1 Detailed list of key startups/SMEs
- 15.7.5.2 Competitive benchmarking of key startups/SMEs
- 15.8 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
16 COMPANY PROFILES
- 16.1 MAJOR PLAYERS
- 16.1.1 THE CHEMOURS COMPANY
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Services/Solutions offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 SOLSTICE ADVANCED MATERIALS
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Services/Solutions offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Deals
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key strengths
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 DONGYUE
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Services/Solutions offered
- 16.1.3.3 MnM view
- 16.1.3.3.1 Key strengths
- 16.1.3.3.2 Strategic choices
- 16.1.3.3.3 Weaknesses and competitive threats
- 16.1.4 ARKEMA
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Services/Solutions offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Deals
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key strengths
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 DAIKIN INDUSTRIES LTD.
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Services/Solutions offered
- 16.1.5.3 MnM view
- 16.1.5.3.1 Key strengths
- 16.1.5.3.2 Strategic choices
- 16.1.5.3.3 Weaknesses and competitive threats
- 16.1.6 ZHEJIANG JUHUA
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Services/Solutions offered
- 16.1.6.3 MnM view
- 16.1.7 ZHEJIANG SANMEI CHEMICAL
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Services/Solutions offered
- 16.1.7.3 MnM view
- 16.1.8 ZHEJIANG YONGHE REFRIGERANT CO., LTD.
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Services/Solutions offered
- 16.1.8.3 MnM view
- 16.1.9 ORBIA
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Services/Solutions offered
- 16.1.9.3 MnM view
- 16.1.10 GUJARAT FLUOROCHEMICALS
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Services/Solutions offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Expansions
- 16.1.10.4 MnM view
- 16.1.11 NAVIN FLUORINE INTERNATIONAL LIMITED
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Services/Solutions offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Deals
- 16.1.11.3.2 Expansions
- 16.1.11.4 MnM view
- 16.1.1 THE CHEMOURS COMPANY
- 16.2 OTHER PLAYERS
- 16.2.1 SRF LIMITED
- 16.2.2 HARP INTERNATIONAL
- 16.2.3 GAS SERVEI S.A.
- 16.2.4 ZHEJIANG TURN YUAN CHEMICAL CO., LTD.
- 16.2.5 JINHUA SLIHE CHEMICAL CO., LTD.
- 16.2.6 HANGZHOU ICETOP REFRIGERATION CO., LTD.
- 16.2.7 ZHANGZHOU RONGQIANG CHEMICAL CO., LTD.
- 16.2.8 ZHEJIANG ZHONGLAN REFRIGERATION TECHNOLOGY CO., LTD.
- 16.2.9 ZHEJIANG FOTECH INTERNATIONAL
- 16.2.10 JIANGSU MEILAN CHEMICAL
- 16.2.11 SHANDONG HUAAN NEW MATERIAL
- 16.2.12 ZHEJIANG ZHONGLAN FLUORINE CHEMICAL
- 16.2.13 SHANDONG YUEAN
- 16.2.14 CHANGSHU 3F ZHONGHAO NEW CHEMICAL MATERIALS: COMPANY OVERVIEW
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.2.3 Breakdown of primary interviews
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.3 DATA TRIANGULATION
- 17.4 STUDY ASSUMPTIONS
- 17.5 RESEARCH LIMITATIONS
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS

(주말 및 공휴일 제외)


