

|
시장보고서
상품코드
2154197
상업용 가습 시장 : 기술별, 제품 유형별 - 세계 예측(-2032년)Commercial Humidification Market by Technology, Product Type - Global Forecast to 2032 |
||||||

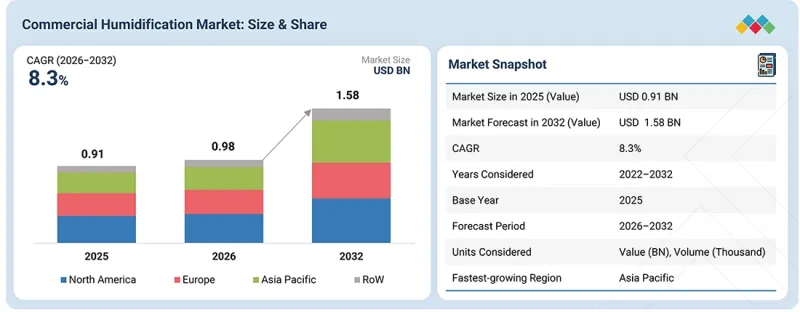
상업용 가습 시장은 2026년 9억 8,000만 달러에서 2032년까지 15억 8,000만 달러로 성장할 것으로 예상되며, 예측 기간 동안 연평균 성장률(CAGR)은 8.3%에 달할 것으로 전망됩니다.
이 시장은 상업용 건물, 의료 시설, 호텔·리조트 시설, 데이터센터에서 정확한 습도 수준을 유지해야 할 필요성이 높아짐에 따라 강력한 성장이 예상됩니다. 시설 운영자들은 HVAC 인프라 및 빌딩 관리 시스템과 연동하여 습도를 제어할 수 있는 가습 시스템 도입을 점점 더 확대하고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2032년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 기술별, 제품 유형별, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양(APAC), 기타 지역(RoW) |
또한, 스마트 센서, 자동 제어 시스템, 원격 모니터링의 도입이 확대됨에 따라 운영자는 수동 개입을 최소화하면서도 습도 수준을 일정하게 유지하는 능력을 높이고 있습니다. 실내 환경을 개선하고, 민감한 장비와 자재를 보호하며, 에너지 효율과 운영 성능을 최적화하는 솔루션에 대한 수요 증가가 시장 확장을 더욱 뒷받침하고 있습니다.
“2026년에는 상업용 건물 부문이 가장 큰 시장 점유율을 차지할 것으로 전망됩니다.”
최종사용자별로는 사무실, 소매점, 호텔·리조트 시설, 기타 상업 시설에서 실내 공기질, 입주자의 쾌적성, 그리고 에너지 효율이 높은 HVAC 운영에 대한 관심이 높아지고 있어, 2026년에는 상업용 건물 부문이 상업용 가습 시장에서 가장 큰 점유율을 차지할 것으로 예상됩니다. 스마트 빌딩 기술 및 통합형 HVAC 시스템의 도입 확대에 따라, 건물 운영자들은 정밀한 습도 관리를 실현하기 위한 자동 제어 기능과 센서를 갖춘 가습 시스템의 도입을 촉진하고 있습니다. 또한, 상업용 건물의 확대, 제어된 실내 환경에 대한 요구 증가, 에너지 최적화 및 건물 성능에 대한 중요성 증대가 상업용 가습 시스템 도입을 촉진하고 있으며, 이는 해당 부문의 성장을 뒷받침하고 있습니다.
“2026년부터 2032년까지 실외 설치형 가습기 부문이 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다.”
제품 유형별로는, 중앙 집중식 습도 제어가 필요한 대규모 상업 시설 및 공공 시설의 도입이 증가하고 있어, 실외 설치형 가습기 부문은 예측 기간 동안 상업용 가습 시장에서 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 데이터센터, 의료 시설, 사무실, 호텔 및 레저 시설의 확장은 대용량 HVAC 인프라에 대한 수요를 견인하고 있으며, 실외에 설치되어 공기조화 장치(AHU)와 통합된 가습 장치에 대한 기회를 창출하고 있습니다. 또한, 실외 설치형 구성은 실내 설비 공간의 한계라는 과제를 해결하는 데 도움이 될 뿐만 아니라, 대규모 시설 전체에 걸친 중앙 집중식 공기 처리를 지원합니다. 중앙 집중식 HVAC 시스템의 도입 확대와 대규모 상업 시설의 개발로 인해 실외 설치형 가습기의 도입이 촉진될 것으로 예상됩니다.
“2032년에는 유럽이 상업용 가습 시장에서 2위의 점유율을 차지할 전망”
지역별로 보면 에너지 효율, 실내 공기질, 그리고 기존 건축 인프라의 현대화에 대한 강력한 집중으로 인해 2032년에는 유럽이 두 번째로 큰 시장 점유율을 차지할 것으로 예상됩니다. 고효율 HVAC 시스템의 도입 확대에 더해, 엄격한 건축 성능 및 환경 요건으로 인해 상업용 건물 운영자들은 첨단 가습 솔루션으로의 업그레이드 및 통합을 촉진하고 있습니다. 또한, 정평이 나 있는 가습기 제조사의 존재, 스마트 빌딩 기술에 대한 투자, 그리고 사무실, 의료 시설, 호텔·관광 업계, 데이터센터에서의 습도 제어에 대한 수요 증가가 이 지역의 시장 성장을 뒷받침하고 있습니다. 기존 상업용 건물의 지속적인 개보수 및 에너지 효율 향상을 위한 개조 또한 상업용 가습 시스템의 도입을 더욱 촉진하고 있으며, 이는 이 지역이 2위 시장으로서의 입지를 확고히 하는 요인 중 하나입니다.
2차 조사를 통해 수집된 각종 부문 및 하위 부문의 시장 규모를 파악하고 검증하기 위해 상업용 가습 솔루션을 제공하는 주요 업계 전문가들을 대상으로 광범위한 1차 인터뷰가 실시되었습니다. 본 보고서의 1차 인터뷰 대상자 구성은 다음과 같습니다:
본 조사에는 부품 공급업체부터 Tier 1 기업, OEM에 이르기까지 다양한 업계 전문가들의 인사이트이 포함되어 있습니다. 1차 조사 대상자의 구성은 다음과 같습니다:
- 기업 유형별 : Tier 1 - 35%, Tier 2 - 40%, Tier 3 - 25%
- 직책별 : C레벨 임원 - 30%, 이사 - 40%, 기타 - 30%
- 지역별 : 북미 - 40%, 유럽 - 30%, 아시아태평양 - 25%, 기타 지역 - 5%
조사 범위
본 조사 보고서에서는 상업용 가습 시장을 기술, 설치 형태, 용량, 제품 유형, 유통 채널, 최종사용자 및 지역별로 분류하고 있습니다. 본 보고서에서는 상업용 가습과 관련된 주요 시장 촉진요인, 제약, 과제 및 기회에 대해 해설하고, 2032년까지의 전망을 제시하고 있습니다. 또한, 본 보고서에는 상업용 가습 생태계에 포함된 모든 기업의 리더십 매핑 및 분석도 포함되어 있습니다.
본 보고서를 구매할 때의 주요 이점
본 보고서는 이 시장의 시장 선도 기업 및 신규 진입 기업에게 상업용 가습 시장 전체 및 각 하위 부문의 수치에 대한 가장 정확한 추정치를 제공합니다. 본 보고서는 이해관계자가 경쟁 구도를 이해하고, 자사의 비즈니스를 더 나은 위치로 이끌며, 적절한 시장 진입 전략을 수립하기 위한 추가적인 인사이트를 얻는 데 도움이 됩니다. 또한, 본 보고서는 이해관계자가 시장 동향을 파악할 수 있도록 지원하며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
본 보고서는 다음 사항에 대한 인사이트를 제공합니다:
- 시장 역학 : 주요 촉진요인(전 세계 건축 재고의 확대 및 급속한 도시화, AI 기반 데이터센터의 폭발적인 성장), 제약요인(중앙 집중식 가습 시스템에 대한 막대한 초기 투자, 관할 구역별로 상이한 규제 기준 및 규정 준수의 복잡성), 기회(IoT 지원 및 센서 기반 습도 모니터링에 대한 수요 증가, 고밀도 데이터센터에서의 가습 솔루션 도입 확대), 그리고 과제(높은 에너지 소비와 건물의 탈탄소화 요구, 담수 자원 제약 및 물 이용 효율에 대한 압박) 등, 상업용 가습 시장의 성장에 영향을 미치는 요인
- 제품 개발/혁신 : 시장의 향후 기술, 연구개발 활동 및 신제품·서비스 출시에 관한 상세한 인사이트
- 시장 개발 : 수익성이 높은 시장에 대한 종합적인 정보--본 보고서에서는 다양한 지역에 걸친 시장을 분석하고 있습니다
- 시장 다각화 : 신제품·서비스, 미개척 지역, 최근 동향 및 시장 투자에 관한 종합적인 정보
- 경쟁 분석 : CAREL INDUSTRIES S.p.A.(이탈리아), Condair Group(스위스), Munters Group AB(스웨덴), Armstrong International Inc(미국), DRISTEEM(미국) 등 시장을 선도하는 주요 기업의 시장 점유율, 성장 전략 및 서비스 제공 내용에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 상업용 가습 시장에서 사업자에게 매력적인 비즈니스 기회
- 상업용 가습 시장 : 기술별
- 상업용 가습 시장 : 설치 유형별
- 상업용 가습 시장 : 용량별
- 상업용 가습 시장 : 제품 유형별
- 상업용 가습 시장 : 유통 채널별
- 상업용 가습 시장 : 최종사용자별
- 상업용 가습 시장 : 국가별
제4장 시장 개요
- 시장 역학
- 성장 촉진요인
- 성장 억제요인
- 기회
- 과제
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업들의 전략적 움직임
제5장 업계 동향
- Porter's Five Forces 분석
- 신규 진입자의 위협
- 대체품의 위협
- 공급업체의 협상력
- 구매자의 협상력
- 경쟁 기업 간의 적대적 관계
- 거시경제 전망
- GDP 동향 및 전망
- 세계 가습기 업계 동향
- 세계 상업용 건축 업계의 동향
- 밸류체인 분석
- 생태계 분석
- 가격 분석
- 기술별 상업용 가습 시스템의 평균 판매 가격 동향(2022-2025년)
- 지역별 상업용 가습 시스템 평균 판매 가격 동향(2022-2025년)
- 무역 분석
- 수입 시나리오(HS 코드 841583)
- 수출 시나리오(HS 코드 841583)
- 주요 회의 및 행사(2026-2027년)
- 고객의 사업에 영향을 미치는 동향 및 변화
- 2022-2025년 투자 및 자금 조달 시나리오
- 사례 연구 분석
- CONDAIR, 증발 가습 기술을 통해 마이크로소프트 데이터센터 냉각 성능 개선 실현
- CONDAIR, 저에너지 가습 기술로 후지쯔의 데이터센터 지원
- DRISTEEM, 저항식 전기 증기 가습기를 통해 BOSTON SCIENTIFIC의 습도 제어를 개선하고 운영 비용을 절감
- MUNTERS, 에너지 효율이 뛰어난 저항식 가습기를 사용하여 레딩 대학교의 습도 제어를 개선
- ARMSTRONG INTERNATIONAL, EHU-700 전극식 가습기를 통해 CHINA TELECOM의 습도 제어를 개선
- 미국 관세의 영향 - 상업용 가습 시장
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가 및 지역에 미치는 영향
- 최종사용자에 미치는 영향
제6장 기술 발전, AI의 영향, 특허, 혁신 및 향후 응용
- 주요 신흥 기술
- 스마트 및 IoT 지원 가습 시스템
- 디지털 트윈
- 절수 및 물 회수 기술
- 보완 기술
- 수처리 기술
- 빌딩 관리 시스템
- 고급 여과 및 미스트 제거 기술
- 기술 로드맵
- 특허 분석
- 미래의 응용
- AI가 상업용 가습 시장에 미치는 영향
- 주요 사용 사례 및 시장 잠재력
- 상업용 가습 시장에서 기업의 모범 사례
- 상업용 가습 시장에서의 AI 도입에 관한 사례 연구
- 상호 연계된 생태계와 시장 참여자에 미치는 영향
- AI 통합형 상업용 가습 솔루션 도입에 대한 고객의 준비 현황
제7장 규제 현황
- 규제 기관, 정부 기관 및 기타 조직
- 규격
제8장 고객 현황 및 구매 행동
- 의사결정 과정
- 구매 과정에 관여하는 주요 이해관계자와 그 평가 기준
- 구매 과정에 관여하는 주요 이해관계자
- 구매 기준
- 도입 장벽과 사내 과제
- 다양한 최종사용자의 충족되지 않은 요구
제9장 상업용 가습 시장 : 기술별
- 증기(등온) 가습 시스템
- 증발식(단열) 가습 시스템
- 하이브리드 시스템
제10장 상업용 가습 시장 : 설치 형태별
- 신규 설치
- 개조 설치
제11장 상업용 가습 시장 : 용량별
- 저용량(50 KG/H 이하)
- 중용량(50-500 KG/H)
- 대용량(500 KG/H 초과)
제12장 상업용 가습 시장 : 제품 유형별
- 집중형 가습기(AHU 일체형)
- 독립형/실내용 가습기
- 덕트 설치형 가습기
- 실외 설치형 가습기
제13장 상업용 가습 시장 : 유통 채널별
- 직판
- HVAC 시공업체/통합업체
- 도매업체 및 판매점
- EPC 시공사
제14장 상업용 가습 시장 : 최종사용자별
- 상업용 건물
- 공공 시설
- 데이터센터
- 기타
제15장 상업용 가습 시장 : 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 영국
- 독일
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 호주
- 기타 아시아태평양
- 기타 지역
- 중동
- 아프리카
- 남미
제16장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점, 2023-2026년
- 수익 분석(2021-2025년)
- 시장 점유율 분석(2025년)
- 기업 가치 평가 및 재무 지표
- 브랜드 비교
- CONDAIR GROUP(SWITZERLAND)
- CAREL INDUSTRIES S.P.A.(ITALY)
- MUNTERS GROUP AB(SWEDEN)
- ARMSTRONG INTERNATIONAL INC.(US)
- DRISTEEM(US)
- 기업 평가 매트릭스 : 주요 기업, 2025년
- 스타
- 신흥 리더
- 광범위한 참여 기업
- 진입 기업
- 기업 사업 전개 : 주요 기업, 2025년
- 기업 평가 매트릭스 : 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹 : 스타트업/중소기업, 2025년
- 경쟁 시나리오
- 제품 출시
- 거래
- 사업 확장
제17장 기업 개요
- 주요 기업
- CONDAIR GROUP
- CAREL INDUSTRIES S.P.A.
- MUNTERS GROUP AB
- ARMSTRONG INTERNATIONAL INC.
- DRISTEEM
- STULZ GMBH
- SPIRAX SARCO LIMITED
- NEPTRONIC
- PURE HUMIDIFIER CO.
- UCAN CO., LTD.
- FOGCO ENVIRONMENTAL SYSTEMS
- MEE INDUSTRIES INC.
- AIR DISTRIBUTION TECHNOLOGIES, INC.
- HUMIDITY SOLUTIONS
- WETMASTER CO., LTD.
- 기타 주요 기업
- BOGA GERATETECHNIK GMBH
- LAVAIR AG KLIMATECHNIK
- CELLKRAFT
- LUFTBEFEUCHTUNG PROKLIMA GMBH
- TROTEC GMBH
- VENTA AIR TECHNOLOGIES, INC.
- AIRMEX GMBH
- PURMIST
- NORTEK GLOBAL HVAC
- RESPIRAQ
제18장 조사 방법론
제19장 부록
KSM 26.10.29The commercial humidification market is anticipated to grow from USD 0.98 billion in 2026 to USD 1.58 billion by 2032, at a CAGR of 8.3% during the forecast period. The market is expected to witness strong growth due to the increasing need to maintain precise humidity levels across commercial buildings, healthcare facilities, hospitality spaces, and data centers. Facility operators are increasingly adopting humidification systems that can provide controlled humidity while integrating with HVAC infrastructure and building management systems.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | By Technology, Product Type and Region |
| Regions covered | North America, Europe, APAC, RoW |
In addition, the growing deployment of smart sensors, automated controls, and remote monitoring is improving the ability of operators to maintain consistent humidity levels with limited manual intervention. Growing demand for solutions that improve indoor environmental conditions, protect sensitive equipment and materials, and optimize energy and operational performance is further supporting the market expansion.
"Commercial buildings segment to account for the largest market share in 2026"
By end user, the commercial buildings segment is expected to hold the largest share of the commercial humidification market in 2026, owing to the increasing focus on indoor air quality, occupant comfort, and energy-efficient HVAC operations across offices, retail spaces, hospitality facilities, and other commercial properties. The growing adoption of smart building technologies and integrated HVAC systems is encouraging building operators to deploy humidification systems with automated controls and sensors for precise humidity management. Moreover, the expansion of commercial buildings, rising requirements for controlled indoor environments, and increasing emphasis on energy optimization and building performance are strengthening the adoption of commercial humidification systems, thereby supporting the segmental growth.
"Outdoor-mounted humidifiers segment to record the highest CAGR between 2026 and 2032"
By product type, the outdoor-mounted humidifiers segment is projected to exhibit the highest CAGR in the commercial humidification market during the forecast period due to the increasing deployment of large-scale commercial and institutional facilities requiring centralized humidity control. The expansion of data centers, healthcare facilities, offices, and hospitality properties is driving demand for high-capacity HVAC infrastructure, creating opportunities for humidification equipment installed externally and integrated with air handling units (AHUs). Moreover, outdoor-mounted configurations can help address limited indoor equipment space while supporting centralized air treatment across large facilities. The growing adoption of centralized HVAC systems and development of large commercial facilities are expected to boost the adoption of outdoor-mounted humidifiers.
"Europe to capture the second-largest share of the commercial humidification market in 2032"
By region, Europe is expected to hold the second-largest market share in 2032 due to the strong focus on energy efficiency, indoor air quality, and modernization of existing building infrastructure. The increasing adoption of efficient HVAC systems, along with stringent building performance and environmental requirements, is encouraging commercial building operators to upgrade and integrate advanced humidification solutions. Moreover, the presence of established humidification manufacturers, investments in smart building technologies, and increasing demand for humidity control across offices, healthcare facilities, hospitality, and data centers are supporting market growth in the region. The ongoing renovation and energy-efficiency upgrades of existing commercial buildings are further contributing to the adoption of commercial humidification systems, supporting its position as the second-largest regional market.
Extensive primary interviews were conducted with key industry experts offering commercial humidification solutions to determine and verify the market size for various segments and subsegments gathered through secondary research. The breakdown of primary participants for the report is provided below:
The study contains insights from various industry experts, from component suppliers to Tier 1 companies and OEMs. The breakdown of the primary participants is as follows:
- By Company Type: Tier 1-35%, Tier 2-40%, and Tier 3-25%
- By Designation: C-level Executives-30%, Directors-40%, and Others-30%
- By Region: North America-40%, Europe-30%, Asia Pacific-25%, and RoW-5%
The report profiles key players in the commercial humidification market with their respective market ranking analysis. Prominent players profiled in this report are CAREL INDUSTRIES S.p.A. (Italy), Condair Group (Switzerland), Munters Group AB (Sweden), Armstrong International Inc (US), and DRISTEEM (US). Apart from this, Spirax Sarco Limited (US), Neptronic (Canada), PURE Humidifier Co. (US), STULZ GMBH (Germany), UCAN Co., Ltd. (Japan), Fogco Environmental Systems (US), Mee Industries Inc. (US), Air Distribution Technologies, Inc. (US), Humidity Solutions (UK), and WETMASTER Co., Ltd. (Japan), among others, are among the few other companies in the market.
Research Coverage
This research report categorizes the commercial humidification market based on technology, installation type, capacity, product type, distribution channel, end user, and region. The report describes the major drivers, restraints, challenges, and opportunities pertaining to commercial humidification and forecasts the same till 2032. Apart from this, the report also consists of leadership mapping and analysis of all the companies included in the commercial humidification ecosystem.
Key Benefits of Buying the Report
The report will help the market leaders/new entrants in this market with information on the closest approximations of the numbers for the overall commercial humidification market and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Market Dynamics: Analysis of key drivers (Expanding global building stock and rapid urbanization, Explosive growth of AI-driven data centers), restraints (High initial investment for centralized humidification systems, Fragmented regulatory standards and compliance complexity across jurisdictions), opportunities (Increasing demand for IoT-enabled and sensor-based humidity monitoring, Mounting adoption of humidification solutions in high-density data centers), and challenges (High energy consumption and building decarbonization imperative, Freshwater resource constraints and water-use efficiency pressures) influencing the growth of the commercial humidification market
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and new product & service launches in the market
- Market Development: Comprehensive information about lucrative markets-the report analyzes the market across varied regions
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as CAREL INDUSTRIES S.p.A. (Italy), Condair Group (Switzerland), Munters Group AB (Sweden), Armstrong International Inc (US), and DRISTEEM (US) in the market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 LIMITATIONS
- 1.7 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN COMMERCIAL HUMIDIFICATION MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN COMMERCIAL HUMIDIFICATION MARKET
- 3.2 COMMERCIAL HUMIDIFICATION MARKET, BY TECHNOLOGY
- 3.3 COMMERCIAL HUMIDIFICATION MARKET, BY INSTALLATION TYPE
- 3.4 COMMERCIAL HUMIDIFICATION MARKET, BY CAPACITY
- 3.5 COMMERCIAL HUMIDIFICATION MARKET, BY PRODUCT TYPE
- 3.6 COMMERCIAL HUMIDIFICATION MARKET, BY DISTRIBUTION CHANNEL
- 3.7 COMMERCIAL HUMIDIFICATION MARKET, BY END USER
- 3.8 COMMERCIAL HUMIDIFICATION MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Expanding global building stock and urbanization
- 4.2.1.2 Rising AI-driven data center capacity
- 4.2.1.3 Increasing development of pharmaceutical manufacturing and healthcare infrastructure
- 4.2.2 RESTRAINTS
- 4.2.2.1 High initial investment for centralized humidification systems
- 4.2.2.2 Fragmented regulatory standards and compliance complexity across jurisdictions
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Mounting deployment of connected sensors and digital building-control technologies
- 4.2.3.2 Rapid expansion of high-density data centers
- 4.2.4 CHALLENGES
- 4.2.4.1 High energy consumption and building decarbonization imperative
- 4.2.4.2 Freshwater resource constraints and water-use efficiency pressures
- 4.2.4.3 Microbial contamination risks and burden of waterborne pathogen regulation
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 THREAT OF NEW ENTRANTS
- 5.2.2 THREAT OF SUBSTITUTES
- 5.2.3 BARGAINING POWER OF SUPPLIERS
- 5.2.4 BARGAINING POWER OF BUYERS
- 5.2.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN GLOBAL HUMIDIFIER INDUSTRY
- 5.3.4 TRENDS IN GLOBAL COMMERCIAL BUILDINGS INDUSTRY
- 5.4 VALUE CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND OF COMMERCIAL HUMIDIFICATION SYSTEMS, BY TECHNOLOGY, 2022-2025
- 5.6.2 AVERAGE SELLING PRICE TREND OF COMMERCIAL HUMIDIFICATION SYSTEMS, BY REGION, 2022-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 841583)
- 5.7.2 EXPORT SCENARIO (HS CODE 841583)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO, 2022-2025
- 5.11 CASE STUDY ANALYSIS
- 5.11.1 CONDAIR ENABLES MICROSOFT TO IMPROVE DATA CENTER COOLING THROUGH EVAPORATIVE HUMIDIFICATION
- 5.11.2 CONDAIR SUPPORTS FUJITSU DATA CENTER WITH LOW-ENERGY HUMIDIFICATION
- 5.11.3 DRISTEEM IMPROVES HUMIDITY CONTROL AND REDUCES OPERATING COSTS AT BOSTON SCIENTIFIC WITH RESISTIVE ELECTRIC STEAM HUMIDIFIERS
- 5.11.4 MUNTERS IMPROVES HUMIDITY CONTROL AT UNIVERSITY OF READING USING ENERGY-EFFICIENT RESISTIVE HUMIDIFIERS
- 5.11.5 ARMSTRONG INTERNATIONAL IMPROVES HUMIDITY CONTROL FOR CHINA TELECOM THROUGH EHU-700 ELECTRODE-TYPE HUMIDIFIERS
- 5.12 IMPACT OF US TARIFFS - COMMERCIAL HUMIDIFICATION MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 Asia Pacific
- 5.12.5 IMPACT ON END USERS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 SMART AND IOT-ENABLED HUMIDIFICATION SYSTEMS
- 6.1.2 DIGITAL TWIN
- 6.1.3 LOW-WATER-CONSUMPTION AND WATER-RECOVERY TECHNOLOGIES
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 WATER TREATMENT TECHNOLOGIES
- 6.2.2 BUILDING MANAGEMENT SYSTEMS
- 6.2.3 ADVANCED FILTRATION AND MIST-ELIMINATION TECHNOLOGIES
- 6.3 TECHNOLOGY ROADMAP
- 6.4 PATENT ANALYSIS
- 6.5 FUTURE APPLICATIONS
- 6.6 IMPACT OF AI ON COMMERCIAL HUMIDIFICATION MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 BEST PRACTICES FOLLOWED BY COMPANIES IN COMMERCIAL HUMIDIFICATION MARKET
- 6.6.3 CASE STUDIES RELATED TO AI IMPLEMENTATION IN COMMERCIAL HUMIDIFICATION MARKET
- 6.6.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.5 CLIENTS' READINESS TO ADOPT AI-INTEGRATED COMMERCIAL HUMIDIFICATION SOLUTIONS
7 REGULATORY LANDSCAPE
- 7.1 INTRODUCTION
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 STANDARDS
- 7.1.2.1 ASHRAE Standard 164.3
- 7.1.2.2 ASHRAE Standard 164.4
- 7.1.2.3 ASHRAE Standard 55
- 7.1.2.4 ISO 17772-1
- 7.1.2.5 EN 16798-1
- 7.1.2.6 EN 13053
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END USERS
9 COMMERCIAL HUMIDIFICATION MARKET, BY TECHNOLOGY
- 9.1 INTRODUCTION
- 9.2 STEAM (ISOTHERMAL) HUMIDIFICATION SYSTEMS
- 9.2.1 ELECTRIC STEAM HUMIDIFIERS
- 9.2.1.1 Simple installation and accurate and responsive humidity control to bolster segmental growth
- 9.2.2 GAS-FIRED STEAM HUMIDIFIERS
- 9.2.2.1 Suitability for large commercial buildings and facilities to contribute to segmental growth
- 9.2.3 STEAM-TO-STEAM HUMIDIFIERS
- 9.2.3.1 Requirement for hygienic and reliable humidity control to accelerate segmental growth
- 9.2.1 ELECTRIC STEAM HUMIDIFIERS
- 9.3 EVAPORATIVE (ADIABATIC) HUMIDIFICATION SYSTEMS
- 9.3.1 HIGH-PRESSURE SPRAY SYSTEMS
- 9.3.1.1 Ability to provide humidification and cooling to bolster segmental growth
- 9.3.2 ULTRASONIC HUMIDIFIERS
- 9.3.2.1 Rapid response to changes in humidity demand and compact design to expedite segmental growth
- 9.3.3 WETTED MEDIA SYSTEMS
- 9.3.3.1 Focus on improving media design, evaporation efficiency, and resistance to scaling and microbial growth to spur demand
- 9.3.4 FOGGING SYSTEMS
- 9.3.4.1 Emphasis on achieving uniform droplet distribution and improving system hygiene to fuel segmental growth
- 9.3.1 HIGH-PRESSURE SPRAY SYSTEMS
- 9.4 HYBRID SYSTEMS
- 9.4.1 ABILITY TO ADJUST MOISTURE OUTPUT AND TECHNOLOGICAL ADVANCEMENTS TO FACILITATE SEGMENTAL GROWTH
10 COMMERCIAL HUMIDIFICATION MARKET, BY INSTALLATION TYPE
- 10.1 INTRODUCTION
- 10.2 NEW INSTALLATION
- 10.2.1 INCREASING CONSTRUCTION OF COMMERCIAL AND INSTITUTIONAL FACILITIES TO AUGMENT SEGMENTAL GROWTH
- 10.2.2 GREENFIELD CONSTRUCTION
- 10.2.3 HVAC SYSTEM INTEGRATION
- 10.3 RETROFIT INSTALLATION
- 10.3.1 GROWING FOCUS ON IMPROVING INDOOR AIR QUALITY AND OCCUPANT COMFORT TO EXPEDITE SEGMENTAL GROWTH
- 10.3.2 EXISTING HVAC UPGRADES
- 10.3.3 ENERGY EFFICIENCY RETROFITS
11 COMMERCIAL HUMIDIFICATION MARKET, BY CAPACITY
- 11.1 INTRODUCTION
- 11.2 LOW CAPACITY (<=50 KG/H)
- 11.2.1 COMPACT DESIGN, RELATIVELY SIMPLE INSTALLATION, AND ABILITY TO PROVIDE CONTROLLED HUMIDITY LEVELS TO SPUR DEMAND
- 11.3 MEDIUM CAPACITY (>50-500 KG/H)
- 11.3.1 REQUIREMENT FOR CONSISTENT HUMIDITY MANAGEMENT ACROSS MULTIPLE ZONES TO ACCELERATE SEGMENTAL GROWTH
- 11.4 HIGH CAPACITY (>500 KG/H)
- 11.4.1 ABILITY TO SUPPORT CENTRALIZED DISTRIBUTION AND AUTOMATED HUMIDITY CONTROL TO FOSTER SEGMENTAL GROWTH
12 COMMERCIAL HUMIDIFICATION MARKET, BY PRODUCT TYPE
- 12.1 INTRODUCTION
- 12.2 CENTRAL HUMIDIFIERS (AHU-INTEGRATED)
- 12.2.1 NEED TO MAINTAIN CONSISTENT RELATIVE HUMIDITY ACROSS LARGE INDOOR AREAS TO BOOST SEGMENTAL GROWTH
- 12.3 STANDALONE/ROOM HUMIDIFIERS
- 12.3.1 FLEXIBLE INSTALLATION AND ABILITY TO CONTROL HUMIDITY CLOSE TO POINT OF USE TO FACILITATE SEGMENTAL GROWTH
- 12.4 DUCT-MOUNTED HUMIDIFIERS
- 12.4.1 EXPANSION OF CENTRALIZED HVAC SYSTEMS IN COMMERCIAL BUILDINGS TO CONTRIBUTE TO SEGMENTAL GROWTH
- 12.5 OUTDOOR-MOUNTED HUMIDIFIERS
- 12.5.1 SPACE CONSTRAINTS AND LARGE-SCALE HVAC REQUIREMENTS TO ACCELERATE SEGMENTAL GROWTH
13 COMMERCIAL HUMIDIFICATION MARKET, BY DISTRIBUTION CHANNEL
- 13.1 INTRODUCTION
- 13.2 DIRECT SALES
- 13.2.1 GROWING PREFERENCE FOR INTEGRATED SOLUTIONS OVER STANDALONE HUMIDIFICATION EQUIPMENT TO FUEL SEGMENTAL GROWTH
- 13.3 HVAC CONTRACTORS/INTEGRATORS
- 13.3.1 RISING COMPLEXITY OF COMMERCIAL PROJECTS AND NEED FOR COORDINATED INSTALLATION AND CONTROL TO DRIVE MARKET
- 13.4 DISTRIBUTORS & DEALERS
- 13.4.1 INCREASING LOCAL MARKET REACH AND FOCUS ON IMPROVING PRODUCT AVAILABILITY TO BOLSTER SEGMENTAL GROWTH
- 13.5 EPC CONTRACTORS
- 13.5.1 RISING INTEGRATION OF HUMIDIFICATION SYSTEMS INTO BROADER MECHANICAL AND ENVIRONMENTAL-CONTROL SYSTEMS TO DRIVE MARKET
14 COMMERCIAL HUMIDIFICATION MARKET, BY END USER
- 14.1 INTRODUCTION
- 14.2 COMMERCIAL BUILDINGS
- 14.2.1 OFFICES
- 14.2.1.1 Increasing need for environmental control in modernized spaces to contribute to segmental growth
- 14.2.2 RETAIL
- 14.2.2.1 Growing emphasis on limiting product damage through moisture control to augment segmental growth
- 14.2.3 HOSPITALITY
- 14.2.3.1 Rapid expansion of wellness-oriented facilities to contribute to segmental growth
- 14.2.4 AIRPORTS/TRANSPORTATION HUBS
- 14.2.4.1 Strong focus on addressing operational and environmental requirements within terminal facilities to fuel segmental growth
- 14.2.1 OFFICES
- 14.3 INSTITUTIONAL
- 14.3.1 HEALTHCARE
- 14.3.1.1 Rising need for area-specific humidity control to boost segmental growth
- 14.3.2 EDUCATION
- 14.3.2.1 Growing focus on maintaining stable environmental conditions and protecting institutional assets to foster segmental growth
- 14.3.3 GOVERNMENT
- 14.3.3.1 High emphasis on renovation and maintenance of aging public infrastructure to expedite segmental growth
- 14.3.1 HEALTHCARE
- 14.4 DATA CENTERS
- 14.4.1 RISING DEPLOYMENT OF AI, HPC, AND OTHER COMPUTE-INTENSIVE WORKLOADS TO CONTRIBUTE TO SEGMENTAL GROWTH
- 14.5 OTHERS
15 COMMERCIAL HUMIDIFICATION MARKET, BY REGION
- 15.1 INTRODUCTION
- 15.2 NORTH AMERICA
- 15.2.1 US
- 15.2.1.1 AI-driven data center expansion and advanced HVAC adoption to bolster market growth
- 15.2.2 CANADA
- 15.2.2.1 Commercial infrastructure development and increasing data center investments to foster market growth
- 15.2.3 MEXICO
- 15.2.3.1 Nearshoring-related investments, expanding data center capacity, and HVAC infrastructure modernization to drive market
- 15.2.1 US
- 15.3 EUROPE
- 15.3.1 UK
- 15.3.1.1 Increasing investment in data centers, healthcare, offices, and hospitality facilities to boost market growth
- 15.3.2 GERMANY
- 15.3.2.1 Strong focus on improving building energy performance and environmental sustainability to augment market growth
- 15.3.3 FRANCE
- 15.3.3.1 Large commercial and institutional building base and need to improve indoor environmental quality to drive market
- 15.3.4 ITALY
- 15.3.4.1 Rising emphasis on building renovation, energy efficiency, and modernization of public infrastructure to expedite market growth
- 15.3.5 SPAIN
- 15.3.5.1 Increasing investment in commercial buildings, data centers, and energy-efficient HVAC systems to bolster market growth
- 15.3.6 REST OF EUROPE
- 15.3.1 UK
- 15.4 ASIA PACIFIC
- 15.4.1 CHINA
- 15.4.1.1 Rapid urbanization, expanding healthcare infrastructure, and adoption of modern HVAC systems to augment market growth
- 15.4.2 JAPAN
- 15.4.2.1 Mounting adoption of energy-efficient heating and ventilation systems to contribute to market growth
- 15.4.3 INDIA
- 15.4.3.1 Rising development of commercial buildings and healthcare infrastructure to support market growth
- 15.4.4 SOUTH KOREA
- 15.4.4.1 Growing need for indoor humidity management to accelerate market growth
- 15.4.5 AUSTRALIA
- 15.4.5.1 Strong emphasis on sustainable building performance to expedite market growth
- 15.4.6 REST OF ASIA PACIFIC
- 15.4.1 CHINA
- 15.5 ROW
- 15.5.1 MIDDLE EAST
- 15.5.1.1 Rising need for indoor humidity management due to hot and arid climate to augment market growth
- 15.5.1.2 GCC countries
- 15.5.1.3 Rest of Middle East
- 15.5.2 AFRICA
- 15.5.2.1 South Africa
- 15.5.2.1.1 Rapid modernization of commercial and institutional buildings to contribute to market growth
- 15.5.2.2 Rest of Africa
- 15.5.2.1 South Africa
- 15.5.3 SOUTH AMERICA
- 15.5.3.1 Brazil
- 15.5.3.1.1 Increasing adoption of modern HVAC systems to foster market growth
- 15.5.3.2 Argentina
- 15.5.3.2.1 Continued modernization of HVAC systems and commercial building upgrades to drive market
- 15.5.3.3 Rest of South America
- 15.5.3.1 Brazil
- 15.5.1 MIDDLE EAST
16 COMPETITIVE LANDSCAPE
- 16.1 OVERVIEW
- 16.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026
- 16.3 REVENUE ANALYSIS, 2021-2025
- 16.4 MARKET SHARE ANALYSIS, 2025
- 16.5 COMPANY VALUATION AND FINANCIAL METRICS
- 16.6 BRAND COMPARISON
- 16.6.1 CONDAIR GROUP (SWITZERLAND)
- 16.6.2 CAREL INDUSTRIES S.P.A. (ITALY)
- 16.6.3 MUNTERS GROUP AB (SWEDEN)
- 16.6.4 ARMSTRONG INTERNATIONAL INC. (US)
- 16.6.5 DRISTEEM (US)
- 16.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.7.1 STARS
- 16.7.2 EMERGING LEADERS
- 16.7.3 PERVASIVE PLAYERS
- 16.7.4 PARTICIPANTS
- 16.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.7.5.1 Company footprint
- 16.7.5.2 Region footprint
- 16.7.5.3 Product type footprint
- 16.7.5.4 End user footprint
- 16.7.5.5 Technology footprint
- 16.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.8.1 PROGRESSIVE COMPANIES
- 16.8.2 RESPONSIVE COMPANIES
- 16.8.3 DYNAMIC COMPANIES
- 16.8.4 STARTING BLOCKS
- 16.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.8.5.1 Detailed list of key startups/SMEs
- 16.8.5.2 Competitive benchmarking of key startups/SMEs
- 16.9 COMPETITIVE SCENARIO
- 16.9.1 PRODUCT LAUNCHES
- 16.9.2 DEALS
- 16.9.3 EXPANSIONS
17 COMPANY PROFILES
- 17.1 KEY PLAYERS
- 17.1.1 CONDAIR GROUP
- 17.1.1.1 Business overview
- 17.1.1.2 Products/Solutions/Services offered
- 17.1.1.3 Recent developments
- 17.1.1.3.1 Product launches
- 17.1.1.3.2 Expansions
- 17.1.1.4 MnM view
- 17.1.1.4.1 Key strengths/Right to win
- 17.1.1.4.2 Strategic choices
- 17.1.1.4.3 Weaknesses/Competitive threats
- 17.1.2 CAREL INDUSTRIES S.P.A.
- 17.1.2.1 Business overview
- 17.1.2.2 Products/Solutions/Services offered
- 17.1.2.3 Recent developments
- 17.1.2.3.1 Product launches
- 17.1.2.4 MnM view
- 17.1.2.4.1 Key strengths/Right to win
- 17.1.2.4.2 Strategic choices
- 17.1.2.4.3 Weaknesses/Competitive threats
- 17.1.3 MUNTERS GROUP AB
- 17.1.3.1 Business overview
- 17.1.3.2 Products/Solutions/Services offered
- 17.1.3.3 Recent developments
- 17.1.3.3.1 Expansions
- 17.1.3.4 MnM view
- 17.1.3.4.1 Key strengths/Right to win
- 17.1.3.4.2 Strategic choices
- 17.1.3.4.3 Weaknesses/Competitive threats
- 17.1.4 ARMSTRONG INTERNATIONAL INC.
- 17.1.4.1 Business overview
- 17.1.4.2 Products/Solutions/Services offered
- 17.1.4.3 Recent developments
- 17.1.4.3.1 Product launches
- 17.1.4.3.2 Deals
- 17.1.4.4 MnM view
- 17.1.4.4.1 Key strengths/Right to win
- 17.1.4.4.2 Strategic choices
- 17.1.4.4.3 Weaknesses/Competitive threats
- 17.1.5 DRISTEEM
- 17.1.5.1 Business overview
- 17.1.5.2 Products/Solutions/Services offered
- 17.1.5.3 Recent developments
- 17.1.5.3.1 Deals
- 17.1.5.3.2 Other developments
- 17.1.5.4 MnM view
- 17.1.5.4.1 Key strengths/Right to win
- 17.1.5.4.2 Strategic choices
- 17.1.5.4.3 Weaknesses/Competitive threats
- 17.1.6 STULZ GMBH
- 17.1.6.1 Business overview
- 17.1.6.2 Products/Solutions/Services offered
- 17.1.6.3 Recent developments
- 17.1.6.3.1 Expansions
- 17.1.7 SPIRAX SARCO LIMITED
- 17.1.7.1 Business overview
- 17.1.7.2 Products/Solutions/Services offered
- 17.1.8 NEPTRONIC
- 17.1.8.1 Business overview
- 17.1.8.2 Products/Solutions/Services offered
- 17.1.8.3 Recent developments
- 17.1.8.3.1 Expansions
- 17.1.8.3.2 Other developments
- 17.1.9 PURE HUMIDIFIER CO.
- 17.1.9.1 Business overview
- 17.1.9.2 Products/Solutions/Services offered
- 17.1.10 UCAN CO., LTD.
- 17.1.10.1 Business overview
- 17.1.10.2 Products/Solutions/Services offered
- 17.1.10.3 Recent developments
- 17.1.10.3.1 Product launches
- 17.1.11 FOGCO ENVIRONMENTAL SYSTEMS
- 17.1.11.1 Business overview
- 17.1.11.2 Products/Solutions/Services offered
- 17.1.12 MEE INDUSTRIES INC.
- 17.1.12.1 Business overview
- 17.1.12.2 Products/Solutions/Services offered
- 17.1.12.3 Recent developments
- 17.1.12.3.1 Developments
- 17.1.13 AIR DISTRIBUTION TECHNOLOGIES, INC.
- 17.1.13.1 Business overview
- 17.1.13.2 Products/Solutions/Services offered
- 17.1.14 HUMIDITY SOLUTIONS
- 17.1.14.1 Business overview
- 17.1.14.2 Products/Solutions/Services offered
- 17.1.14.3 Recent developments
- 17.1.14.3.1 Product launches
- 17.1.15 WETMASTER CO., LTD.
- 17.1.15.1 Business overview
- 17.1.15.2 Products/Solutions/Services offered
- 17.1.15.3 Recent developments
- 17.1.15.3.1 Product launches
- 17.1.1 CONDAIR GROUP
- 17.2 OTHER PLAYERS
- 17.2.1 BOGA GERATETECHNIK GMBH
- 17.2.2 LAVAIR AG KLIMATECHNIK
- 17.2.3 CELLKRAFT
- 17.2.4 LUFTBEFEUCHTUNG PROKLIMA GMBH
- 17.2.5 TROTEC GMBH
- 17.2.6 VENTA AIR TECHNOLOGIES, INC.
- 17.2.7 AIRMEX GMBH
- 17.2.8 PURMIST
- 17.2.9 NORTEK GLOBAL HVAC
- 17.2.10 RESPIRAQ
18 RESEARCH METHODOLOGY
- 18.1 RESEARCH DATA
- 18.1.1 SECONDARY AND PRIMARY RESEARCH
- 18.1.2 SECONDARY DATA
- 18.1.2.1 List of key secondary sources
- 18.1.2.2 Key data from secondary sources
- 18.1.3 PRIMARY DATA
- 18.1.3.1 List of primary interview participants
- 18.1.3.2 Breakdown of primary interviews
- 18.1.3.3 Key data from primary sources
- 18.1.3.4 Key industry insights
- 18.2 MARKET SIZE ESTIMATION
- 18.2.1 TOP-DOWN APPROACH
- 18.2.1.1 Approach to arrive at market size using top-down analysis (supply side)
- 18.2.2 BOTTOM-UP APPROACH
- 18.2.2.1 Approach to arrive at market size using bottom-up analysis (demand side)
- 18.2.1 TOP-DOWN APPROACH
- 18.3 DATA TRIANGULATION
- 18.4 RESEARCH ASSUMPTIONS
- 18.5 RISK ANALYSIS
- 18.6 RESEARCH LIMITATIONS
19 APPENDIX
- 19.1 DISCUSSION GUIDE
- 19.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 19.3 CUSTOMIZATION OPTIONS
- 19.4 RELATED REPORTS
- 19.5 AUTHOR DETAILS


