

|
시장보고서
상품코드
2121258
유전자 검사 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Genetic Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
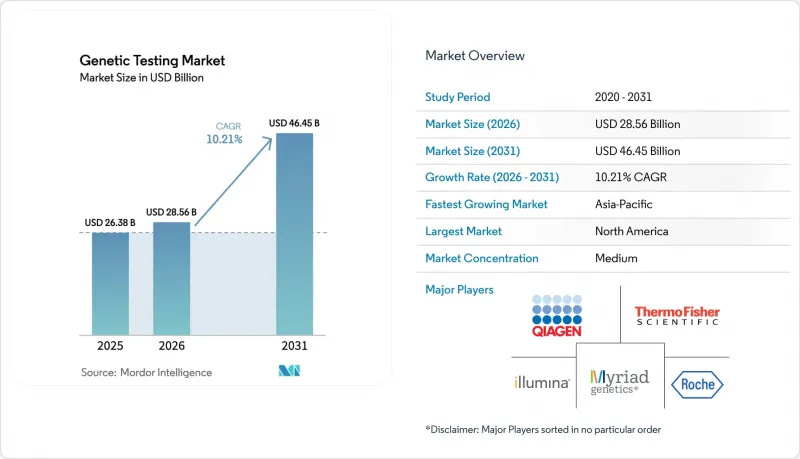
에 따르면 유전자 검사 시장 규모는 2025년 263억 8,000만 달러에서 2026년에는 285억 6,000만 달러로 확대되어 2031년까지 464억 5,000만 달러에 달할 것으로 예상되며, 2026년부터 2031년까지 CAGR 10.21%로 성장할 것으로 전망됩니다.
본 보고서는 제품·서비스별(소모품·시약, 기기·장치, 소프트웨어·서비스), 검사 유형별(진단, 산전·신생아, 기타), 기술별(NGS, 기타), 용도별(종양학, 유전성 질환 진단, 기타), 최종사용자별(병원·클리닉, 기타), 지역별(북미, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 유전자 검사 시장의 동향 및 인사이트
NIPT 및 신생아 선별 검사의 급속한 보급
미국의 민간 보험사들은 2025년까지 사전 승인 없이 13번 삼염색체증, 18번 삼염색체증, 21번 삼염색체증에 대한 NIPT의 보험 적용을 시작했으며, 보급률은 80%를 넘어섰습니다. 30개 주가 동시에 신생아 선별 검사 항목을 35가지 주요 질환으로 확대함에 따라, Natera의 ‘Panorama’와 PerkinElmer 플랫폼에 대한 수요가 증가했습니다. 미국 산부인과 학회(ACOG)의 개정 지침에 따라 2024년에 NIPT가 모든 임신에서 첫 번째 선택으로 지정되어, 위험에 따른 장벽이 제거되었습니다. 이러한 변화로 인해 산전 검사는 틈새 시장 부문에서 보편적인 보험 적용 대상으로 전환되었으며, 보험 지급 주기가 단축됨과 동시에 소비자에게 직접 유통하는 채널이 가능해졌습니다. 중국에서는 2025년에 1선 도시에서 NIPT에 대한 보험 적용이 시작되었지만, 농촌 지역이 있는 성에서는 여전히 본인 부담이 적용되어 도입 상황에 편차가 발생하고 있습니다.
다유전자 패널의 보험 적용이 주류화
메디케어는 2024년, NCCN 가이드라인에 따라 유전성 암 패널의 보험 적용 대상에 BRCA1/2, PALB2, ATM을 추가했습니다. 민간 보험사들도 이에 발맞춰 대상 가입자에게 25-80개 유전자로 구성된 패널의 보험 적용을 시작함에 따라, Myriad의 ‘MyRisk’와 Invitae의 검사 건수는 전년 대비 40% 증가했습니다. 패널 검사의 평균 보상액은 250달러 전후로 안정되었으나, 이는 과거 수준에 비해 대폭 하락한 것으로, 진행성 암의 치료비 부담을 줄이는 데 중점을 두는 보험사들에게 예방적 검사 시행이 경제적으로 매력적인 선택지가 되고 있습니다. 독일에서는 여전히 BRCA 검사가 진단 후 사용으로만 제한되어 있어, 예방적 검사의 보급이 억제되고 있습니다.
국경을 넘는 데이터 주권에 관한 규제
2025년 5월에 시행될 EU의 ‘헬스 데이터 스페이스(Health Data Space)’ 규정에 따르면, 유전체 데이터를 EU 내 서버에 저장해야 할 의무가 부과되어 다국적 데이터세트가 분할될 것입니다. 마찬가지로 중국의 규제에서도 국내 저장이 의무화되어 있으며, 인간의 유전 물질을 해외와 공유하려면 정부의 승인이 필요하기 때문에 국제적인 협력이 제한되고 있습니다. 이러한 조치로 인해 검사 기관은 서로 다른 인프라를 유지하고 상충되는 동의 체계에 대응해야 하므로, 규정 준수 비용이 증가하고 국경을 넘는 검사 서비스의 시작이 지연될 것입니다.
부문 분석
2025년 매출액 중 소모품과 시약이 37.57%를 차지하며, 유전자 검사 시장에서 소모품으로서의 핵심적인 역할을 강화하고 있습니다. 그러나 시퀀싱보다 결과 해석이 주요 병목 현상으로 대두됨에 따라, 소프트웨어 및 서비스는 2031년까지 연평균 성장률(CAGR) 14.57%로 성장할 것으로 전망됩니다. 검사 기관이 막대한 설비 투자가 필요한 서버에서 연간 5만 달러 이하의 클라우드 구독으로 전환함에 따라, 유전자 검사 시장의 소프트웨어 제품 시장 규모는 확대될 것으로 예측됩니다. CE 마크가 부착된 분석 소프트웨어를 의무화하는 EU의 IVDR(체외진단용 의료기기 규정)은 사내 파이프라인에서의 전환을 더욱 촉진하고 있습니다. 장비 판매는 반도체 공급 지연으로 인해 납기 기간이 1년에 달하는 문제에 직면해 있지만, 시약 구매는 지속적이고 예측 가능한 수요를 유지하고 있습니다.
지속적인 수익 모델은 벤더의 현금 흐름을 개선하는 동시에 중견 검사 기관의 설립 비용을 절감합니다. 2025년에 출하될 NovaSeq X 1대당, 완전 가동 시 연간 약 100만 달러 상당의 시약을 소비하므로, 일루미나(Illumina)사에게는 연금과 같은 안정적인 매출을 가져다줍니다. 소프트웨어 공급업체는 단계적인 분석을 통해 변이 데이터베이스를 수익화하여, 지역 병원이 전담 바이오인포매틱스 전문가 없이도 범암 패널 검사를 실시할 수 있도록 합니다. 상담, 결과 해석, 청구 지원을 패키지로 묶은 유전자 검사 업계 사업자들은 치료 전 과정의 비용을 평가하는 보험사에 대해 경쟁 우위를 확보하고 있습니다.
2025년에는 산전 및 신생아 검사가 시장의 36.25%를 차지했지만, 지침이 범민족 패널로 전환됨에 따라 보인자 선별 검사는 연평균 성장률(CAGR) 13.34%로 성장할 전망입니다. 검사 메뉴가 확대되어, 이전에는 아슈케나지계 혈통에 중점을 두었던 것이 현재는 400개 이상의 질환을 포괄하게 되었기 때문에 보인자 선별 유전자 검사 시장 규모는 더욱 확대될 것으로 보입니다. 진단 검사는 여전히 검사 건수가 많지만, 엑솜 시퀀싱이 단일 유전자 검사를 대체함에 따라 가격 면에서 압박을 받고 있습니다. 예측 패널은 메디케어 및 민간 보험사의 보험 적용으로 계속해서 혜택을 받고 있지만, GINA(유전정보차별금지법)에 의한 보호가 있음에도 불구하고, 개인정보 보호에 대한 우려로 인해 영향을 받지 않는 성인층의 이용률은 여전히 낮은 수준을 유지하고 있습니다.
2024년 ACMG가 유니버설 패널의 채택을 권장함에 따라, 확대된 보인자 선별 검사가 급증했습니다. 2025년에는 불임 치료 클리닉에서 Natera Horizon의 도입률이 50% 증가했습니다. 그러나 보험사들은 엑솜 시퀀싱 청구를 승인하기 전에 대상 검사의 음성 결과에 대한 증거를 점점 더 요구하고 있으며, 이러한 추세로 인해 환자들은 단계적인 검사를 받도록 권장받고 있습니다. 약리유전체학 패널은 연평균 성장률(CAGR) 약 10%로 확대되고 있지만, 전자건강기록(EHR)의 의사결정 지원 기능이 부족하여 의사에 의한 도입이 더딘 실정입니다. 소비자 직접 판매(DTC) 조상 유전자 검사는 2024년에 규모가 축소되었습니다. 이는 개인정보 보호에 대한 우려로 인해 23andMe가 치료 부문에서 철수하고 인력 감축에 나섰기 때문입니다.
지역별 분석
북미는 2025년 유전자 검사 시장 매출의 43.13%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 9.8%로 확대될 전망입니다. 메디케어와 대형 보험사들은 유전성 암, NIPT(태아 비침습적 검사), 체액 생검 검사의 비용을 보상하고 있는 반면, 고용주들은 유전체 웰니스 관련 복리후생 혜택을 확대하고 있습니다. FDA는 2024년에 12건의 유전자 검사를 승인했으며, ‘정밀 의학 이니셔티브(Precision Medicine Initiative)’에 따라 승인 주기를 18개월에서 9개월로 단축했습니다. 캐나다에서는 온타리오주와 브리티시컬럼비아주에서 DPYD 유전자형 검사에 대한 보험 적용이 이루어지고 있지만, 멕시코에서는 여전히 본인 부담이 주를 이루며, 도시 지역의 민간 시설에서만 이용이 제한되어 있습니다.
아시아태평양은 중국의 전국적인 시퀀싱 인프라와 인도의 확대되는 진단 네트워크에 힘입어 연평균 성장률(CAGR) 12.63%를 기록할 것으로 예측됩니다. BGI는 세계 최대의 시퀀싱 허브를 운영하고 있으며, 매월 100만 건 이상의 검체를 처리하고 있을 뿐만 아니라, 2025년에는 100달러짜리 유전체 분석 서비스를 시작할 예정입니다. 일본에서는 진행성 암에 대한 종합적인 유전체 프로파일링이 보험 적용 대상입니다. 인도의 주요 체인에서는 NIPT를 300달러에 제공하고 있으며, 이는 미국 가격의 3분의 1 수준입니다. 한국은 2024년에 BRCA 검사를 추가했으며, 호주에서는 티오퓨린 계열 약물에 대한 약물유전학 검사가 150호주달러(100달러)에 보험 적용되고 있습니다.
유럽에서는 검사실 상황이 재편되고 있습니다. 독일에서는 유전성 암 패널 검사에 대해 1,500유로(1,650달러)의 보험 적용이 이루어지고 있으며, 영국의 NHS는 10만 건의 암 유전체 시퀀싱을 실시하여 그중 30%에서 임상적으로 활용 가능한 소견을 얻었습니다. 프랑스는 ‘유전체 의료 계획’에 6억 7,000만 유로(7억 3,700만 달러)를 투자했습니다. 중동 및 아프리카는 2030년까지 100만 명의 아랍에미리트 국민의 유전체 시퀀싱을 진행하겠다는 아랍에미리트의 계획에 힘입어 연평균 성장률(CAGR) 11%로 성장할 전망입니다. 남미는 연평균 성장률(CAGR) 10.5%로 발전하고 있으며, 브라질의 Fleury와 Dasa는 3,000 브라질 레알(600 달러)에 유전성 암 패널을 도입하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the genetic testing market size is expected to increase from USD 26.38 billion in 2025 to USD 28.56 billion in 2026 and reach USD 46.45 billion by 2031, growing at a CAGR of 10.21% over 2026-2031.
This report is Segmented by Product & Service (Consumables and Reagents, Equipment and Instruments, Software and Services), Test Type (Diagnostic, Prenatal & Newborn, and More), Technology (NGS, and More), Application (Oncology, Genetic Disease Diagnosis, and More), End User (Hospitals & Clinics, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Genetic Testing Market Trends and Insights
Rapid Adoption of NIPT & Newborn Screening
Commercial payers in the United States covered NIPT for trisomies 13, 18, and 21 without prior authorization by 2025, lifting penetration above 80%. Thirty states simultaneously expanded newborn panels to 35 core conditions, boosting demand for Natera Panorama and PerkinElmer platforms. Updated American College of Obstetricians and Gynecologists guidance designated NIPT as a first-tier option for all pregnancies in 2024, removing risk-based barriers. The shift converted prenatal testing from niche to universal coverage, shortening reimbursement cycles and enabling direct-to-consumer channels. China began reimbursing NIPT in tier-1 cities in 2025, yet rural provinces remain self-pay, creating uneven adoption.
Mainstream Insurance Coverage for Multigene Panels
Medicare added BRCA1/2, PALB2, and ATM to its hereditary cancer panel coverage in 2024, aligning with NCCN guidelines. Commercial payers followed by reimbursing 25- to 80-gene panels for eligible members, pushing Myriad MyRisk and Invitae volumes up 40% year-over-year. Average panel reimbursement settled near USD 250, down steeply from historical levels, making proactive testing financially attractive to payers focused on avoiding late-stage cancer costs. Germany still limits BRCA testing to post-diagnosis use, curbing preventive uptake.
Cross-Border Data Sovereignty Restrictions
The EU Health Data Space regulation effective May 2025 mandates EU server residency for genomic data, fragmenting multinational datasets. China's rules likewise require domestic storage and government approval for sharing human genetic material abroad, limiting global collaboration. These policies raise compliance costs as labs must maintain separate infrastructures and navigate conflicting consent frameworks, delaying cross-border assay launches.
Other drivers and restraints analyzed in the detailed report include:
- Falling NGS Cost below USD 100/Genome
- Cloud-Based AI Genomic Interpretation Ecosystems
- Skilled Genetic Counselor Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables and reagents held 37.57% of 2025 revenue, reinforcing their role as the consumable backbone of the genetic testing market. Software and services, however, will advance at a 14.57% CAGR to 2031 as interpretation rather than sequencing becomes the primary bottleneck. The genetic testing market size for software offerings is projected to widen as laboratories shift from high-capex servers to cloud subscriptions billed below USD 50,000 per year. EU IVDR rules that require CE-marked interpretation software further drive migration away from in-house pipelines. Equipment sales face semiconductor delays that stretch instrument lead times to a year, but reagent purchases remain recurring and predictable.
Recurring revenue models improve vendor cash flows while lowering startup costs for mid-tier labs. Each NovaSeq X shipped in 2025 consumes roughly USD 1 million in reagents annually at full utilization, creating annuity-like sales for Illumina. Software vendors monetize variant databases through tiered analytics, enabling community hospitals to run pan-cancer panels without dedicated bioinformaticians. Genetic testing industry players offering bundled counseling, interpretation, and billing support gain a competitive edge with payers that assess total episode cost.
Prenatal and newborn assays accounted for 36.25% in 2025, yet carrier screening is poised to grow at 13.34% CAGR as guidelines shift toward pan-ethnic panels. The genetic testing market size for carrier screening will broaden because expanded menus now cover over 400 conditions, replacing earlier Ashkenazi-focused offerings. Diagnostic testing remains high-volume but faces price pressure as exome sequencing displaces single-gene assays. Predictive panels continue to benefit from Medicare and commercial payer coverage, although uptake among unaffected adults remains modest due to privacy concerns despite GINA protections.
Expanded carrier screening surged after ACMG recommended universal panels in 2024. Adoption among fertility clinics rose 50% in 2025 for Natera Horizon. Payers, however, increasingly demand evidence of negative targeted tests before approving exome claims, a dynamic that pushes patients through stepwise testing. Pharmacogenomic panels advance at roughly 10% CAGR, but lack of EHR decision support slows physician adoption. Direct-to-consumer ancestry tests saw contraction in 2024 as privacy concerns drove 23andMe to pivot away from therapeutics and cut staff.
Complete Report Scope:
- By Product & Service
- Consumables and Reagents
- Equipments and Instruments
- Software and Services
- By Test Type
- Diagnostic
- Prenatal & Newborn
- Predictive & Presymptomatic
- Carrier
- Pharmacogenomic
- By Technology
- Next-Generation Sequencing (NGS)
- Polymerase Chain Reaction (PCR)
- Microarray
- Cytogenetic / FISH
- Other Technologies
- By Application
- Oncology
- Genetic Disease Diagnosis
- Reproductive Health
- Ancestry & DTC Wellness
- Others
- By End User
- Hospitals & Clinics
- Diagnostic Laboratories
- Research & Academic Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 43.13% of 2025 revenue in the genetic testing market and will rise at 9.8% CAGR through 2031. Medicare and major insurers reimburse hereditary cancer, NIPT, and liquid biopsy assays, while employers broaden genomic wellness benefits. The FDA cleared 12 genetic tests in 2024, cutting approval cycles from 18 to 9 months under its Precision Medicine Initiative. Canada reimburses DPYD genotyping in Ontario and British Columbia, whereas Mexico remains largely self-pay, restricting access to urban private facilities.
Asia-Pacific is forecast to log a 12.63% CAGR, underpinned by China's national sequencing infrastructure and India's expanding diagnostics network. BGI runs the world's largest sequencing hub, processing over 1 million samples monthly and launching a USD 100 genome service in 2025. Japan reimburses comprehensive genomic profiling for advanced cancer; India's leading chains offer NIPT at USD 300, one-third U.S. prices. South Korea added BRCA testing in 2024, and Australia reimburses pharmacogenomics for thiopurine drugs at AUD 150 (USD 100).
Europe reshapes the laboratory landscape. Germany reimburses hereditary cancer panels at EUR 1,500 (USD 1,650); the U.K. NHS sequenced 100,000 cancer genomes with 30% actionable findings. France invested EUR 670 million (USD 737 million) in its Genomic Medicine Plan. Middle East and Africa will grow at an 11% CAGR, led by the UAE's plan to sequence 1 million Emirati genomes by 2030. South America advances at a 10.5% CAGR, with Brazil's Fleury and Dasa introducing hereditary panels at BRL 3,000 (USD 600).
- 23andMe
- Abbott Laboratories
- Agilent Technologies
- BGI
- Centogene
- Color Health
- Eurofins
- Exact Sciences
- Roche
- Guardant Health
- Illumina
- Invitae
- LabCorp
- Myriad Genetics
- Natera
- Oxford Nanopore Technologies
- Pacific Biosciences
- PerkinElmer
- QIAGEN
- Quest Diagnostics
- Thermo Fisher Scientific
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of NIPT & Newborn Screening
- 4.2.2 Mainstream Insurance Coverage for Multigene Panels
- 4.2.3 Falling NGS Cost Less Than USD 100/Whole Genome (Post-2027)
- 4.2.4 Cloud-Based AI Genomic Interpretation Ecosystems
- 4.2.5 Liquid-Biopsy-Ready Regulatory Pathways
- 4.2.6 Employer-Sponsored Genomic-Wellness Benefits Surge
- 4.3 Market Restraints
- 4.3.1 Cross-Border Data-Sovereignty Restrictions
- 4.3.2 Skilled-Genetic-Counsellor Shortage Bottlenecks
- 4.3.3 Patchy Reimbursement in Emerging Economies
- 4.3.4 NGS Chip Supply-Chain Dependency on 2 Fabs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product & Service
- 5.1.1 Consumables and Reagents
- 5.1.2 Equipments and Instruments
- 5.1.3 Software and Services
- 5.2 By Test Type
- 5.2.1 Diagnostic
- 5.2.2 Prenatal & Newborn
- 5.2.3 Predictive & Presymptomatic
- 5.2.4 Carrier
- 5.2.5 Pharmacogenomic
- 5.3 By Technology
- 5.3.1 Next-Generation Sequencing (NGS)
- 5.3.2 Polymerase Chain Reaction (PCR)
- 5.3.3 Microarray
- 5.3.4 Cytogenetic / FISH
- 5.3.5 Other Technologies
- 5.4 By Application
- 5.4.1 Oncology
- 5.4.2 Genetic Disease Diagnosis
- 5.4.3 Reproductive Health
- 5.4.4 Ancestry & DTC Wellness
- 5.4.5 Others
- 5.5 By End User
- 5.5.1 Hospitals & Clinics
- 5.5.2 Diagnostic Laboratories
- 5.5.3 Research & Academic Institutes
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 23andMe
- 6.3.2 Abbott Laboratories
- 6.3.3 Agilent Technologies
- 6.3.4 BGI Genomics
- 6.3.5 Centogene
- 6.3.6 Color Health
- 6.3.7 Eurofins Scientific
- 6.3.8 Exact Sciences
- 6.3.9 F. Hoffmann-La Roche
- 6.3.10 Guardant Health
- 6.3.11 Illumina
- 6.3.12 Invitae
- 6.3.13 Laboratory Corporation of America
- 6.3.14 Myriad Genetics
- 6.3.15 Natera
- 6.3.16 Oxford Nanopore Technologies
- 6.3.17 Pacific Biosciences
- 6.3.18 PerkinElmer
- 6.3.19 QIAGEN
- 6.3.20 Quest Diagnostics
- 6.3.21 Thermo Fisher Scientific
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


