

|
시장보고서
상품코드
2120274
안료 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pigments - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
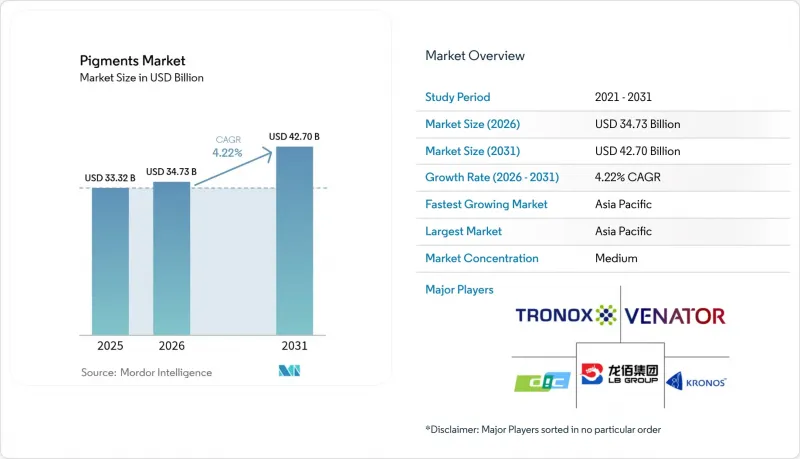
에 따르면 안료 시장 규모는 2025년에 333억 2,000만 달러, 2026년에 347억 3,000만 달러에 달하며, 2031년까지 427억 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 4.22%로 성장할 것으로 전망되고 있습니다.
이 보고서는 제품 유형(무기 안료 [이산화티타늄,산화아연, 기타 제품 유형], 유기 안료, 특수 안료 및 기타 제품 유형), 용도(페인트·코팅, 섬유, 인쇄 잉크, 플라스틱, 가죽, 기타 용도) 및 지역(아시아태평양, 북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 안료 시장의 동향 및 인사이트
신흥 경제국에서의 페인트·코팅 수요 급증
인도 및 동남아시아의 대규모 인프라 투자로 인해 높은 은폐력을 지닌 루틸형 이산화티타늄(TiO2) 및 산화철계 착색제가 필요한 건축용 도료의 출하량이 확대되고 있습니다. 인도의 공공 자본 지출은 계속해서 GDP를 상회하는 속도로 증가하고 있으며, 중국의 도시 재생 프로그램에 따른 정부의 경기 부양책이 주택 시장의 둔화를 완화하고 있습니다. 또한 중국의 2급 및 3급 도시에서는 저VOC 에멀전으로의 전환이 진행되고 있으며, 착색 시스템내 유기 안료의 배합량이 증가하고 있습니다. 베트남 건설 부문의 호조는 휘발성 유기 화합물(VOC) 상한치를 준수하는 수성 라텍스 도료에 대한 유사한 수요를 지원하고 있습니다. 이러한 동향들이 맞물려 범용 등급 및 특수 등급 모두에서 견고한 소비 기반이 강화되며, 아시아태평양 전체의 안료 시장을 촉진하고 있습니다.
친환경/바이오 유래 안료에 대한 규제 동향
유럽식품안전청(EFSA)이 2022년에 이산화티타늄(TiO2, E171)의 식품 사용 금지 조치를 취함에 따라 화장품 및 퍼스널 케어 제품의 성분 재검토로 파급되고 있습니다. 각 브랜드는 양산화 과정에서 해결되지 않은 과제가 있음에도 불구하고 미세조류 및 균류 유래 착색제의 시험적 도입을 추진하고 있습니다. 미국에서는 TSCA(유해물질관리법)에 따른 나노 물질 특정 보고 의무로 인해 규정 준수 비용이 증가하고 있습니다. 이러한 이중적인 압박으로 인해 전략은 양극화되고 있습니다. 범용 제조업체는 건축용 도료용 루틸형 TiO₂에 대한 투자를 강화하는 한편, 특수 제조업체는 상용화될 경우 고가 책정이 가능한 바이오 발효 경로에 대한 연구개발에 주력하고 있습니다.
엄격한 환경·독성 규제
전담 규제 대응 팀을 갖추지 못한 중견 제조업체는 REACH 및 TSCA 준수로 인해 안료 1개당 서류 작성 비용이 상당한 수준까지 치솟아 이익률이 압박받고 있습니다. 미국에서는 나노 물질에 대한 PMN 심사 기간이 12개월로 연장되어 신제품 출시가 지연되는 동시에, 조달 대상이 사전 승인을 받은 안료로 전환되고 있습니다. 한편, 다양한 제품 포트폴리오를 보유한 대형 공급업체들은 이러한 비용을 원활하게 흡수하고 있으며, 안료 시장의 통합 추세를 더욱 가속화하고 있습니다.
부문 분석
2025년 매출 중 무기 안료가 75.45%를 차지하고 있으며, 이는 안료 시장 점유율에서 가장 큰 하위 부문인 건축용 및 산업용 도료 분야에서 TiO2가 확고한 입지를 차지하고 있음을 보여줍니다. 반면, 유기 안료는 내광성 및 규제 준수가 요구되는 플라스틱 및 포장 용도에 힘입어 연평균 5.21%의 성장률을 기록하고 있습니다. 전기자동차 및 민생용 전자 기기의 보급으로 인해 범용 TiO2보다 적외선 반사 복합 무기 착색 안료와 같은 특수 하위 카테고리에 대한 프리미엄 수요가 증가하고 있습니다. 이러한 특수 등급 안료 시장 규모는 비교적 작지만, 그 높은 부가가치가 업계 전반의 활발한 연구개발 활동을 지원하고 있습니다.
규제의 파편화로 인해 급속한 대체화 추세가 가속화되고 있습니다. 화장품 브랜드에서는 현재 산화철 블렌드나 바이오 유래 발색제에 대한 실험이 진행되고 있습니다. 한편, 카본 블랙은 오랫동안 인쇄 잉크 및 자동차 언더바디 시장을 독점해 왔으나, 현재는 용광로내 연소에 의한 흑색 입자상 물질 배출 감축을 목표로 하는 그래핀 분산액이나 재활용 대체품과의 경쟁에 직면해 있습니다. 천연 유래의 시에나 계열 안료와 울트라마린 블루는 예술계에서 여전히 높은 평가를 받고 있지만, 안료 시장 전체에서 차지하는 비중은 극히 미미합니다.
지역별 분석
아시아태평양은 2025년에 매출의 45.68%를 차지하며, 2031년까지 연평균 성장률(CAGR) 5.36%로 다른 모든 지역을 능가하는 성장을 보일 것으로 전망됩니다. 중국의 도시 재생 프로젝트에 대한 경기 부양책이 신축 건설 부진을 상쇄하여, 실내용 에멀전 도료 시장에서 한 자릿수 중반대의 성장률을 유지하고 있습니다. 인도의 인프라 정비 계획은 특수 산화철 안료 및 유기 안료가 필요한 고성능 에폭시 및 폴리우레탄 도료의 수요를 촉진하고 있습니다. 일본의 열변색 및 광변색 화학 분야에서의 점진적인 기술 혁신과 더불어, 한국의 자동차·조선 업계에서 요구하는 적외선 반사 및 방식 등급의 사양 요건이 특수 안료의 시장 침투를 촉진하고 있습니다. 아세안(ASEAN) 국가들의 제조업 확대는 유지보수용 도료 및 플라스틱 분야를 통해 판매량을 더욱 끌어올리고 있습니다.
북미와 유럽은 성숙한 시장이지만 고급화가 진행되고 있습니다. ‘인플레이션 억제법(Inflation Reduction Act)’의 생산 세액 공제로 인해 미국에서는 이산화티타늄(TiO2)의 생산 능력이 재개되고 있습니다. 한편, 유럽에서는 중국산 원자재에 대해 CBAM(탄소국경조정메커니즘) 및 반덤핑 관세가 부과되고 있으며, 비용은 높아지지만, 현지 조달이 진행되고 있습니다. 독일, 영국, 이탈리아, 프랑스, 스페인은 자동차 재도장, 건축물 개보수, 산업용 유지보수 등 각 분야에서 유럽의 수요를 지탱하고 있습니다. 제재로 인해 고립된 러시아는 여전히 국내의 산화철 및 카본 블랙 공급에 의존하고 있습니다.
남미의 안료 수요는 브라질의 건설 및 자동차 생산을 중심으로 전개되고 있으며, 인프라 사업이 보호 코팅 수요를 지원하고 있습니다. 아르헨티나와 칠레는 규모는 작지만 수요가 증가하는 추세를 보이고 있습니다. 중동 및 아프리카의 점유율은 가장 낮지만, 사우디아라비아의 NEOM이나 남아프리카의 광업 프로젝트와 같은 메가 프로젝트와 관련하여 때때로 수요가 급증하는 경향이 있습니다. 이 지역들은 규제 체제가 여전히 완만하므로 특정 산업 분야에서는 납크롬산염이나 카드뮴계 안료의 사용이 계속되고 있지만, 다국적 브랜드들은 자발적으로 이러한 사용을 단계적으로 폐지하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.02According to Mordor Intelligence, the pigments market size is projected to be USD 33.32 billion in 2025, USD 34.73 billion in 2026, and reach USD 42.70 billion by 2031, growing at a CAGR of 4.22% from 2026 to 2031.
This report is Segmented by Product Type (Inorganic Pigments [Titanium Dioxide, Zinc Oxide, and Other Product Types], Organic Pigments, and Specialty Pigments and Other Product Types), Application (Paints and Coatings, Textiles, Printing Inks, Plastics, Leather, and Other Applications), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Pigments Market Trends and Insights
Surging Paints and Coatings Demand in Emerging Economies
Strong infrastructure outlays in India and Southeast Asia are scaling architectural-coating volumes that require high-hiding rutile TiO2 and iron-oxide tints. India's public capital expenditure pipeline continues to run ahead of GDP, and government stimulus in Chinese urban-renewal programs is cushioning the residential slowdown. Tier-2 and tier-3 Chinese cities are additionally shifting toward low-VOC emulsions, elevating organic pigment loading in tinting systems. Vietnam's construction-sector momentum feeds similar demand for water-based latex paints that observe volatile-organic-compound ceilings. Collectively, these developments reinforce a sturdy consumption base for both commodity and specialty grades, bolstering the pigments market across Asia-Pacific.
Regulatory Push Toward Eco-Friendly/Bio-Based Pigments
The European Food Safety Authority's 2022 enforcement of the TiO2 (E171) food ban is cascading into cosmetics and personal-care reformulations. Brands are piloting microalgal and fungal colorants despite unresolved scaling hurdles. In the United States, nanomaterial-specific reporting under TSCA intensifies compliance costs. The dual pressure is bifurcating strategies: commodity producers double down on rutile TiO2 for construction paints, while specialty houses channel research and development toward bio-fermentation routes that can command premium pricing once commercialized.
Stringent Environmental and Toxicology Regulations
Mid-tier producers, lacking dedicated regulatory teams, find their margins pinched as compliance with REACH and TSCA can push dossier costs to significant levels per pigment. In the U.S., PMN reviews for nanomaterials have extended to 12 months, causing delays in new-product launches and shifting procurement focus to pre-approved pigments. Meanwhile, larger suppliers, with their diversified portfolios, seamlessly absorb these costs, further fueling consolidation trends in the pigments market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of High-Performance and Effect Pigments
- Nano-Enabled Digital and 3D Printing Applications
- Raw-Material Price Volatility (TiO2, Iron-Oxide Feedstocks)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Inorganic pigments held 75.45% of 2025 revenue, illustrating the entrenched role of TiO2 in architectural and industrial coatings, the largest sub-segment within the pigments market share. Organic pigments, however, are advancing 5.21% annually, driven by plastics and packaging applications that demand lightfastness and regulatory compliance. Electric vehicles and consumer electronics are driving a premium for specialty sub-categories like infrared-reflective complex inorganic color pigments over commodity TiO2. While the market size for these specialty-grade pigments is relatively modest, their significant value contribution fuels robust research and development efforts across the industry.
Regulatory fragmentation is spurring rapid substitution trends. Cosmetics brands are now experimenting with iron-oxide blends and bio-derived colorants. Meanwhile, while carbon black has long dominated printing inks and automotive underbodies, it is now facing competition from graphene dispersions and recycled alternatives, which aim to reduce furnace-black particulate emissions. Earth-based siennas and ultramarine blues, though still cherished in artistic circles, make up a small portion of the overall pigments market.
Complete Report Scope:
- By Product Type
- Inorganic Pigments
- Titanium Dioxide
- Zinc Oxide
- Other Product Types (Carbon Pigments, Dry Earth, Ultramarine Pigments, Cadmium, Lead Chromate, and Others)
- Organic Pigments
- Specialty Pigments and Other Product Types (Functional Pigments, Magnetic Pigments, and Others)
- Inorganic Pigments
- By Application
- Paints and Coatings
- Textiles
- Printing Inks
- Plastics
- Leather
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 45.68% of revenue in 2025 and will outpace all other regions at a 5.36% CAGR through 2031. China's stimulus programs in urban-renewal projects offset softness in new-build construction, sustaining mid-single-digit gains in interior emulsions. India's infrastructure agenda spurs demand for high-performance epoxy and polyurethane coatings requiring specialty iron-oxide and organic pigments. Japan's incremental innovations in thermochromic and photochromic chemistries and South Korea's automotive and shipbuilding specifications for infrared-reflective and anti-corrosive grades enhance specialty-pigment penetration. ASEAN manufacturing expansions further pull volume through maintenance coatings and plastics.
North America and Europe are mature yet premiumizing markets. The Inflation Reduction Act's production credits entice U.S. TiO2 capacity restarts, while Europe's CBAM and anti-dumping levies on Chinese inputs drive localized sourcing, albeit at higher costs. Germany, the United Kingdom, Italy, France, and Spain anchor European demand across automotive refinish, architectural renovation, and industrial maintenance. Russia, isolated by sanctions, remains reliant on local iron-oxide and carbon-black supply.
South America's pigments demand centers on Brazil's construction and automotive production, with infrastructure concessions sustaining protective-coating needs. Argentina and Chile add smaller yet rising contributions. The Middle-East and Africa hold the smallest share but see episodic spikes tied to mega-projects such as NEOM in Saudi Arabia and mining ventures in South Africa. Regulatory regimes in these regions remain less stringent, allowing continued use of lead chromate and cadmium pigments in select industrial niches, although multinational brands are voluntarily phasing them out.
- ALTANA
- Cathay Industries
- DIC Corporation
- Heubach GmbH
- Kronos Worldwide, Inc.
- Lanxess
- LB Group
- Shepherd Color
- Sudarshan Chemical Industries Limited (Heubach GmbH)
- The Chemours Company
- Tronox Holdings Plc
- Trust Chem Co., Ltd.
- Venator Materials PLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging paints and coatings demand in emerging economies
- 4.2.2 Regulatory push toward eco-friendly/bio-based pigments
- 4.2.3 Rising adoption of high-performance and effect pigments
- 4.2.4 Nano-enabled digital and 3-D printing applications
- 4.2.5 Supply-chain localization incentives in US-EU
- 4.3 Market Restraints
- 4.3.1 Stringent environmental and toxicology regulations
- 4.3.2 Raw-material price volatility (TiO2, iron-oxide feedstocks)
- 4.3.3 Nano-particle food-grade bans (E171, cosmetics limits)
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Inorganic Pigments
- 5.1.1.1 Titanium Dioxide
- 5.1.1.2 Zinc Oxide
- 5.1.1.3 Other Product Types (Carbon Pigments, Dry Earth, Ultramarine Pigments, Cadmium, Lead Chromate, and Others)
- 5.1.2 Organic Pigments
- 5.1.3 Specialty Pigments and Other Product Types (Functional Pigments, Magnetic Pigments, and Others)
- 5.1.1 Inorganic Pigments
- 5.2 By Application
- 5.2.1 Paints and Coatings
- 5.2.2 Textiles
- 5.2.3 Printing Inks
- 5.2.4 Plastics
- 5.2.5 Leather
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 ALTANA
- 6.4.2 Cathay Industries
- 6.4.3 DIC Corporation
- 6.4.4 Heubach GmbH
- 6.4.5 Kronos Worldwide, Inc.
- 6.4.6 Lanxess
- 6.4.7 LB Group
- 6.4.8 Shepherd Color
- 6.4.9 Sudarshan Chemical Industries Limited (Heubach GmbH)
- 6.4.10 The Chemours Company
- 6.4.11 Tronox Holdings Plc
- 6.4.12 Trust Chem Co., Ltd.
- 6.4.13 Venator Materials PLC
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


