

|
시장보고서
상품코드
2122311
전기 이중층 커패시터(EDLC) : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Electric Double-layer Capacitor (EDLC) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 전기 이중층 커패시터 시장 규모는 2025년에 8억 8,000만 달러로 평가되었고, 2026년 9억 9,458만 달러에서 2031년까지 18억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 13.02%를 기록할 전망입니다.
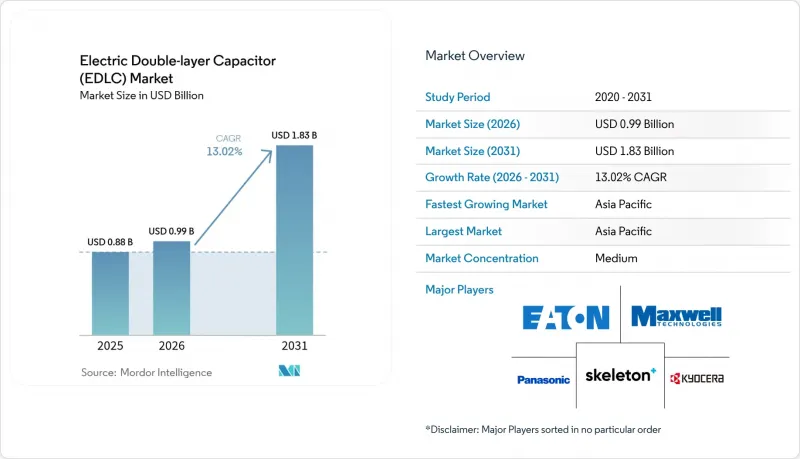
본 보고서는 제품 폼 팩터별(원통형 셀, 기타), 모듈 전압별(10V 이하, 10-25V, 기타),전극 재료별(활성탄, 그래핀·그래핀 복합재료, 기타), 최종 사용자 산업별(가정용 전자기기, 에너지·유틸리티, 기타), 지역(북미, 남미, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 전기 이중층 커패시터(EDLC) 시장 동향 및 인사이트
EV/HEV에서의 회생 제동 채택 급증
각 자동차 제조업체는 리튬 이온 배터리로서는 신속하게 흡수할 수 없는 제동 에너지를 회수하기 위해, 48V 마일드 하이브리드 플랫폼에 전기 이중층 커패시터(EDLC) 시장의 솔루션을 통합하고 있습니다. EDLC 모듈은 밀리초 단위의 충전 펄스를 포착하여 도시 지역의 연비를 15-20% 향상시키는 동시에, 풀 하이브리드로의 전환 없이도 유럽의 CO2 배출 목표를 달성할 수 있게 해줍니다. 버스 및 경전철 운영 사업자들은 제동 마모에 따른 유지보수를 줄이고, 중량 감소를 통해 적재량의 경제성을 향상시키는 기술을 우선시하고 있습니다.
계통 규모의 주파수 조정 및 재생에너지 평활화에 대한 수요 증가
전력 회사는 태양광 및 풍력 발전의 비중을 늘리고 있으며, 이로 인해 관성력이 저하되고 주파수 변동이 심화되고 있습니다. 스켈레톤 테크놀로지스의 ‘SkelGrid 2.0’ 캐비닛은 1초 이내에 최대 3MW를 공급하며, 왕복 효율 99%로 합성 관성력을 제공합니다. 미국과 독일의 부가 서비스 경매에서는 1초 미만의 응답 속도가 높이 평가되고 있으며, EDLC 기반의 고속 주파수 응답 자산은 3년 이내에 투자 회수가 가능합니다.
리튬 이온 배터리와 비교했을 때 1Wh당 달러 기준 비용이 높은 점
EDLC 팩의 가격은 여전히 1kWh당 800-1,200달러 수준을 유지하고 있지만, 이에 비해 리튬 이온 배터리의 벤치마크 가격은 1kWh당 150달러 이하이며, 에너지 밀도가 경제성 판단을 좌우하는 부문에서는 EDLC의 채택이 제한되고 있습니다. 총 소유 비용(TCO) 측면에서 우위가 인정되는 것은 고사이클 용도로 한정되기 때문에 공급업체들은 향후 시행될 EU 규제에 따라 수명 주기 내 유지보수 비용 절감 및 재활용을 통한 크레딧을 강조할 수밖에 없는 상황에 놓여 있습니다.
부문 분석
원통형 유닛은 자동차용 스타터 모듈 및 산업용 UPS 뱅크에서 입증된 신뢰성을 바탕으로 2025년 매출의 35.42%를 차지했습니다. 원통형 설계의 전기 이중층 커패시터(EDLC) 시장 규모는 48V 마일드 하이브리드 차량의 보급에 따라 확대되어 2031년까지 6억 5,200만 달러에 달할 것으로 예측됩니다. 기계적 치수가 표준화되어 있어 기존 배터리 트레이에의 통합이 간소화되고, 설계 부담이 경감됩니다. 한편, 코인형과 칩형은 웨어러블 기기, 스마트 패치, 타이어 공기압 센서 등에서 서브 mm급의 얇은 두께가 요구됨에 따라 연평균 성장률(CAGR) 14.88%로 확대되고 있습니다. 각 제조업체는 1세제곱센티미터당 에너지 밀도를 높이기 위해 레이저 패터닝을 적용한 집전체나 고체 전해질을 채택하고 있습니다. 예측 기간 동안, 조립 설계(DFA)가 직사각형 리튬이온 코어 주위에 EDLC 층을 내장한 배터리와 커패시터의 하이브리드형 코패키징 구조로 전환됨에 따라 폼 팩터의 경계는 모호해질 것입니다.
원통형 배터리 공급업체들은 열 저항을 30% 감소시키는 알루미늄 압출 성형 하우징과 같은 냉각 기술 혁신에 주력하고 있습니다. 코인형 배터리의 혁신 기업들은 비용 절감을 위해 롤투롤 방식의 전극 인쇄를 확대되고 있습니다. 파우치형 및 각형 제품은 특히 항공우주용 항공전자 장비나 폭 제약 하에서 운행되는 무인 운반차(AGV)와 같이 설계자가 불규칙한 공동을 관리해야 하는 상황에서 가교 역할을 수행하고 있습니다. 모듈 및 시스템 통합사업자들은 IEC 62040 클래스 C UPS 안전 기준을 충족하기 위해 플러그 앤 플레이 방식의 버스바 레이아웃과 셀 수준의 퓨즈 보호 기능에 중점을 두고 있습니다.
10-25V 정격 모듈은 12V 자동차용 서브시스템 및 24V 산업용 제어 시스템과의 호환성을 바탕으로 2025년 시장 점유율의 40.12%를 차지했습니다. 설계자들은 기존 와이어 하네스 표준을 활용하고 고전압 클리어런스 요건을 회피함으로써 전기 이중층 커패시터(EDLC) 시장에서 선도적인 입지를 확립하고 있습니다. 상업용 배송 밴이 납산 시동 배터리에서 100만 사이클의 작동을 견딜 수 있는 EDLC 크랭킹 부스터로 전환됨에 따라 성장은 계속되고 있습니다. 100V를 초과하는 고전압 스택은 재생에너지의 그리드 버퍼 수요를 충족하고 전기 버스 구동을 지원하기 위해 연평균 성장률(CAGR) 14.63%로 성장이 가속화될 것으로 예측됩니다. Skeleton사의 162V 모듈은 안전한 핫 스왑 기능, 갈바닉 절연, 열 폭주 방지 분리기를 특징으로 하며, 전력 회사의 조달 사양을 충족합니다.
저전압(10V 이하) 마이크로 모듈은 안전성 측면에서 접촉 안전 한계가 요구되는 스마트 카드, 약물 투여 펌프, 체내 이식형 의료기기의 기반이 되고 있습니다. 중전압(25-50V) 유닛은 데이터센터의 배전반에 채택되어 48V 버스바와 서버 마더보드를 연결하고 있습니다. 제품 로드맵에서는 CANopen을 통한 능동형 균형 회로와 상태 모니터링(SOH) 분석의 통합에 중점을 두어, 예측 유지보수를 지원하는 것을 목표로 하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 42.10%를 차지했습니다. 이는 중국의 송전망 규모 주파수 조정 시범 사업, 일본의 가전제품 소형화, 한국의 배터리 생태계 집적화에 힘입은 결과입니다. 각 지역 정부는 국내 에너지 저장 밸류체인을 위해 자본 보조금 예산을 배정하고 있으며, 이를 통해 제조 비용 측면에서의 우위가 강화되고 있습니다. 공급업체들은 인도네시아와 베트남에 위치한 활성탄 처리 거점과의 근접성을 활용하여 물류 효율화를 실현하고 리드 타임을 단축하고 있습니다. 현지 자동차 제조업체가 조달량의 기반을 형성하고 있으며, 규모의 경제를 창출함으로써 수출 시장에서 가격 경쟁력을 유지하고 있습니다.
북미에서는 송전 사업자들이 기록적인 태양광 발전 설비 도입에 따른 네트워크 안정화를 도모하기 위해 EDLC 어레이를 도입하고 있어, 해당 지역 시장 점유율이 확대되고 있습니다. 미국의 데이터센터 사업자들은 유지보수가 필요 없고 대기 시 손실이 적다는 점 때문에 플라이휠보다 48V EDLC 랙을 선호하여 채택하고 있습니다. 방위 부문의 조달을 통해 지향성 에너지 프로토타입에 사용되는 CNT(탄소나노튜브)가 충전된 펄스 전력 모듈의 연구 개발 자금이 지원되고 있습니다. 캐나다는 국내 흑연 정제를 지원하기 위한 광업 개혁을 추진하고 있으며, 공급망 다각화 전략의 일환으로 대체 원료 공급원으로서의 입지를 확립하고 있습니다.
유럽에서는 배터리 규정 2023/1542에 따른 엄격한 수명 주기 규정 준수가 뒷받침되면서 채택이 진행되고 있습니다. 이 규정에 따라 전기 이중층 커패시터(EDLC) 시장 제품에도 제조자 책임이 확대되었습니다. 자동차 제조업체들은 에코디자인 크레딧을 확보하기 위해 EDLC 모듈을 채택하고 있는 반면, 전력 회사들은 에너지 및 전력 품질 요건을 모두 충족하는 하이브리드형 배터리·슈퍼커패시터 저장 블록의 검사 및 운영을 수행하고 있습니다. 각 제조업체들은 2030년까지 의무화된 90%의 자재 회수 목표를 달성하기 위해 자동화된 사용 후 제품 해체 라인에 투자하고 있습니다. 중동 및 아프리카에서는 아직 발전 가능성이 보입니다. 이 지역들은 주변 온도가 높기 때문에 EDLC 시스템이 통신 타워의 백업 전원으로 매력적이며, 공조(HVAC)로 냉각되는 컨테이너형 리튬 이온 배터리 뱅크의 필요성을 없애줍니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the electric double-layer capacitor market size was valued at USD 0.88 billion in 2025 and estimated to grow from USD 994.58 million in 2026 to reach USD 1.83 billion by 2031, at a CAGR of 13.02% during the forecast period (2026-2031).
This report is Segmented by Product Form Factor (Cylindrical Cell, and More), Module Voltage (Less Than 10V, 10-25V, and More), Electrode Material (Activated Carbon, Graphene/Graphene Composite, and More), End-User Industry (Consumer Electronics, Energy and Utilities, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Electric Double-layer Capacitor (EDLC) Market Trends and Insights
Surging adoption of regenerative braking in EV/HEV
Automakers integrate Electric Double-layer Capacitor market solutions into 48V mild-hybrid platforms to harvest braking energy that lithium-ion cells cannot absorb quickly. EDLC modules capture millisecond-scale charge pulses, raising urban fuel efficiency by 15-20% and allowing compliance with European CO2 targets without requiring a shift to full hybrids. Fleet operators of buses and light-rail vehicles prioritize technology to reduce brake-wear maintenance and unlock weight reductions that improve payload economics.
Growing demand for grid-scale frequency regulation and renewable smoothing
Utilities increase their share of solar and wind energy, lowering inertia and intensifying frequency volatility. Skeleton Technologies' SkelGrid 2.0 cabinets supply up to 3 MW within one second, delivering synthetic inertia with 99% round-trip efficiency. Ancillary-service auctions in the United States and Germany reward sub-second response, enabling paybacks under three years for EDLC-based fast-frequency-response assets.
Higher USD-per-Wh cost versus Li-ion batteries
EDLC packs remain priced at USD 800-1,200/kWh, compared with lithium-ion's sub-USD 150/kWh benchmark, which restricts adoption where energy density dominates the economic calculus. The total-cost-of-ownership argument only prevails in high-cycle applications, compelling suppliers to emphasize lifecycle maintenance savings and recycling credits under forthcoming EU regulations.
Other drivers and restraints analyzed in the detailed report include:
- Miniaturization trend in consumer electronics requiring burst-power buffers
- Rapid roll-out of 5 G macro and micro-cells needing peak-power support
- Design-in complexity owing to standards fragmentation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cylindrical units held 35.42% of 2025 revenue, underpinned by proven reliability in automotive starter modules and industrial UPS banks. The Electric Double-layer Capacitor market size for cylindrical designs is projected to reach USD 652 million by 2031, expanding in line with the adoption of 48 V mild-hybrid vehicles. Standardized mechanical dimensions simplify integration with existing battery trays, curbing engineering overhead. Meanwhile, coin and chip formats scale at a 14.88% CAGR as wearables, smart patches, and tire-pressure sensors require sub-millimeter profiles. Manufacturers deploy laser-patterned current collectors and solid-state electrolytes to elevate energy per cubic centimeter. Over the forecast horizon, form-factor boundaries blur as design-for-assembly shifts to co-packaged battery-capacitor hybrids that embed EDLC layers around prismatic lithium-ion cores.
Cylindrical suppliers focus on cooling innovations, such as aluminum extrusion housings, which reduce thermal resistance by 30%. Coin-cell innovators scale roll-to-roll electrode printing to control costs. Pouch and prismatic options play a bridging role where designers manage irregular cavities, notably in aerospace avionics and automated-guided vehicles navigating width constraints. Module and system integrators emphasize plug-and-play busbar layouts and fused cell-level protection to meet IEC 62040 class-C UPS safety levels.
Modules rated 10-25 V captured 40.12% 2025 share thanks to compatibility with 12 V automotive subsystems and 24 V industrial controls. Designers achieve leadership in the Electric Double-layer Capacitor market by leveraging existing wiring harness standards and avoiding high-voltage clearance requirements. Growth persists as commercial delivery vans migrate from lead-acid starting batteries to EDLC cranking boosters that survive million-cycle duty. High-voltage stacks above 100 V are expected to accelerate at a 14.63% CAGR to meet renewable grid buffers and support electric-bus traction. Skeleton's 162 V modules highlight safe hot-swapping, galvanic isolation, and thermal-runaway-proof separators, addressing utility procurement specs.
Low-voltage (<10 V) micro-modules underpin smartcards, drug-delivery pumps, and implantables where safety dictates touch-safe limits. Mid-voltage (25-50 V) units populate data-center power distribution units, bridging 48 V busbars and server motherboards. The product roadmap focuses on integrating active balancing circuits and State-of-Health analytics via CANopen to support predictive maintenance.
Complete Report Scope:
- By Product Form Factor
- Cylindrical Cell
- Pouch / Prismatic Cell
- Coin / Chip Cell
- Module (Greater than equal to 10 F)
- Pack / System
- By Module Voltage
- Less than 10 V
- 10 - 25 V
- 25 - 50 V
- 50 - 100 V
- Greater than 100 V
- By Electrode Material
- Activated Carbon
- Graphene / Graphene Composite
- Carbon Nanotube (CNT)
- Conductive Polymer
- Metal-Oxide-Enhanced
- By End-user Industry
- Consumer Electronics
- Energy and Utilities
- Industrial
- Automotive / Transportation
- Bus and Truck
- Rail and Tram
- 48 V Mild Hybrid Car
- Micro-hybrids and Other Cars
- Heavy Vehicles
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific maintained 42.10% of global revenue in 2025, underpinned by China's grid-scale frequency-regulation pilots, Japan's consumer-electronics miniaturization, and South Korea's battery-ecosystem clustering. Regional governments allocate capital-subsidy pools for domestic energy-storage value chains, reinforcing manufacturing cost leadership. Suppliers benefit from proximity to activated-carbon processing hubs in Indonesia and Vietnam, which streamlines logistics and reduces lead times. Local automakers anchor procurement volumes, fostering economies of scale that sustain price competitiveness for export markets.
North America is capturing a rising share as transmission operators deploy EDLC arrays to stabilize networks that are dealing with record solar installations. Data-center operators in the United States prefer 48 V EDLC racks over flywheels due to their zero maintenance requirements and lower standby losses. Defense procurement underpins R&D funding for CNT-loaded pulse-power modules used in directed-energy prototypes. Canada champions mining reforms to support domestic graphite purification, positioning itself as an alternative raw material source amid supply chain diversification strategies.
Europe advances adoption driven by stringent lifecycle compliance under Battery Regulation 2023/1542, which extends producer responsibility to Electric Double-layer Capacitor market products. Automakers incorporate EDLC modules to secure eco-design credits, while utilities pilot hybrid battery-supercapacitor storage blocks that satisfy both energy and power-quality mandates. Manufacturers invest in automated end-of-life disassembly lines to meet mandated 90% material-recovery targets by 2030. The Middle East and Africa present nascent potential, where high ambient temperatures make EDLC systems attractive for telecom tower backup, eliminating the need for HVAC-cooled containerized lithium-ion banks.
- Tesla Inc. - Maxwell Technologies
- Skeleton Technologies OU
- Panasonic Holdings Corporation
- LS Mtron Ltd.
- Nippon Chemi-Con Corp.
- Eaton Corporation
- Kyocera Corporation
- CAP-XX Ltd.
- Supreme Power Solutions Ltd.
- Cornell Dubilier Electronics Inc.
- TDK Corporation
- Vishay Intertechnology Inc.
- Seiko Instruments Inc.
- Taiyo Yuden Co., Ltd.
- Yunasko Ltd.
- Tavrima Canada Inc.
- Shanghai Aowei Technology Development Co., Ltd.
- Nantong Jianghai Capacitor Co., Ltd.
- Jinzhou Kaimei Power Co., Ltd.
- Beijing HCC Energy Tech Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging adoption of regenerative braking in EV/HEV
- 4.2.2 Growing demand for grid-scale frequency regulation and renewable smoothing
- 4.2.3 Miniaturisation trend in consumer electronics requiring burst-power buffers
- 4.2.4 Rapid roll-out of 5G macro and micro-cells needing peak-power support
- 4.2.5 Emergence of 48 V edge-data-centre backup architectures
- 4.2.6 Defence transition to high-pulse directed-energy platforms
- 4.3 Market Restraints
- 4.3.1 Higher USD-per-Wh cost v. Li-ion batteries
- 4.3.2 Design-in complexity owing to standards fragmentation
- 4.3.3 Volatile activated-carbon feed-stock pricing
- 4.3.4 Prospective EU "battery-take-back" extension to EDLC modules
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Form Factor
- 5.1.1 Cylindrical Cell
- 5.1.2 Pouch / Prismatic Cell
- 5.1.3 Coin / Chip Cell
- 5.1.4 Module (Greater than equal to 10 F)
- 5.1.5 Pack / System
- 5.2 By Module Voltage
- 5.2.1 Less than 10 V
- 5.2.2 10 - 25 V
- 5.2.3 25 - 50 V
- 5.2.4 50 - 100 V
- 5.2.5 Greater than 100 V
- 5.3 By Electrode Material
- 5.3.1 Activated Carbon
- 5.3.2 Graphene / Graphene Composite
- 5.3.3 Carbon Nanotube (CNT)
- 5.3.4 Conductive Polymer
- 5.3.5 Metal-Oxide-Enhanced
- 5.4 By End-user Industry
- 5.4.1 Consumer Electronics
- 5.4.2 Energy and Utilities
- 5.4.3 Industrial
- 5.4.4 Automotive / Transportation
- 5.4.4.1 Bus and Truck
- 5.4.4.2 Rail and Tram
- 5.4.4.3 48 V Mild Hybrid Car
- 5.4.4.4 Micro-hybrids and Other Cars
- 5.4.4.5 Heavy Vehicles
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Tesla Inc. - Maxwell Technologies
- 6.4.2 Skeleton Technologies OU
- 6.4.3 Panasonic Holdings Corporation
- 6.4.4 LS Mtron Ltd.
- 6.4.5 Nippon Chemi-Con Corp.
- 6.4.6 Eaton Corporation
- 6.4.7 Kyocera Corporation
- 6.4.8 CAP-XX Ltd.
- 6.4.9 Supreme Power Solutions Ltd.
- 6.4.10 Cornell Dubilier Electronics Inc.
- 6.4.11 TDK Corporation
- 6.4.12 Vishay Intertechnology Inc.
- 6.4.13 Seiko Instruments Inc.
- 6.4.14 Taiyo Yuden Co., Ltd.
- 6.4.15 Yunasko Ltd.
- 6.4.16 Tavrima Canada Inc.
- 6.4.17 Shanghai Aowei Technology Development Co., Ltd.
- 6.4.18 Nantong Jianghai Capacitor Co., Ltd.
- 6.4.19 Jinzhou Kaimei Power Co., Ltd.
- 6.4.20 Beijing HCC Energy Tech Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


