

|
시장보고서
상품코드
2062090
알루민산 칼슘 시멘트 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Calcium Aluminate Cement - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
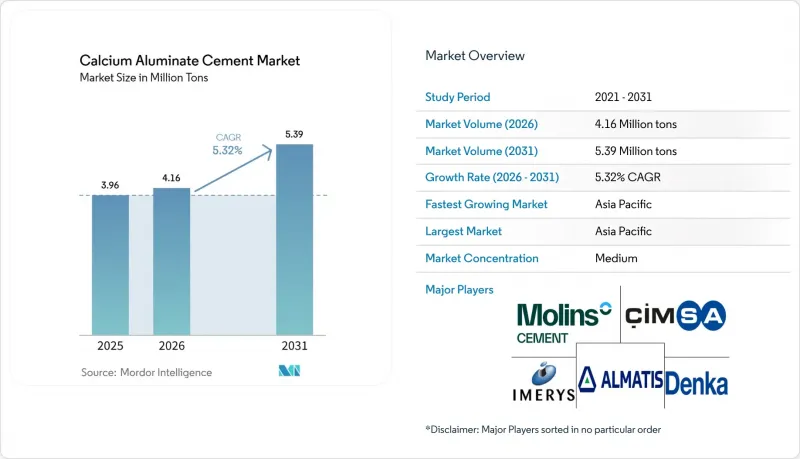
에 의하면, 알루민산 칼슘 시멘트 시장 규모는 2025년 396만 톤으로 평가되었고, 2026년에는 416만 톤으로 추정되고, 2031년까지 539만 톤에 이를 것으로 예상되고 있으며, 2026-2031년 CAGR 5.32%로 성장할 전망입니다.
본 보고서는 유형별(고알루미나 시멘트, 프리믹스형 알루민산 칼슘 시멘트 등), 형태별(분말, 프리믹스 봉지 포장 등), 용도별(내화물 등), 최종 사용자 산업별(철강 및 야금, 석유 및 가스 등), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 수량(톤) 기준으로 제시되어 있습니다.
세계 칼슘 알루미나트 시멘트 시장 동향 및 분석
내화물 분야 수요 증가
인도의 전기 아크로로 전환에 따라 2023-2024년에는 내화 캐스터블 수요가 22% 증가했으며, 포틀랜드계 결합재로는 강도를 유지할 수 없는 상황에서도 강도를 유지할 수 있다는 특성 덕분에 칼슘 알루미나이트 시멘트(CAC)의 소비 확대가 촉진되었습니다. 이러한 전환으로 인해 철강 1톤당 60-70%의 에너지 절감 효과가 나타나고 있으며, 또한 의무화된 탈탄소화를 위한 인도의 'Perform, Achieve, and Trade(PAT)' 제도 준수가 지속적인 수요 증가를 뒷받침하고 있습니다. 마찬가지로, 중동 및 중국의 석유화학 크래커 개보수 공사에서는 CAC와 반응성 알루미나를 조합한 초저시멘트 캐스터블이 채택되고 있습니다. 이를 통해 1,400℃에서 12메가파스칼(MPa)을 초과하는 고온 파단 탄성률을 달성하여, 라이닝의 수명을 15-20% 연장했습니다.
초경화성 및 고성능 콘크리트의 도입
칼슘설포알루미나이트계 콘크리트는 해수를 사용함으로써 72시간 이내에 35-40MPa의 강도를 달성합니다. 이를 통해 연안 지역의 프리캐스트 공장에서 담수를 사용할 필요가 없어지며, 일반 포틀랜드 시멘트(OPC)에 비해 이산화탄소(CO2) 배출량을 최대 48%까지 줄일 수 있습니다. 미국에서는 '인프라 투자 및 고용법'의 자금을 활용한 교량 상판 오버레이 공사에서 이러한 속경성 재료의 사용이 의무화되어 있습니다. 마찬가지로, 아세안(ASEAN)의 '연결성 마스터플랜'에서는 2030년까지 2,100억 달러에 달하는 인프라 격차를 해소하기 위해 알루민산 칼슘 시멘트(CAC) 바인더의 사용이 허용되고 있습니다.
높은 제조 비용 대 포틀랜드 시멘트
포틀랜드계 시멘트보다 100-150°C 높은 온도에서 소결하기 때문에 알루민산 칼슘 시멘트(CAC)의 에너지 소비량은 15-20% 증가하며, 25-30%의 가격 프리미엄이 발생합니다. 따라서, 속경제를 첨가한 일반 포틀랜드 시멘트(OPC)로도 충분히 대응할 수 있는 용도의 경우, 그 사용이 제한되고 있습니다. 2025년, 인도의 바이어들은 중국산 수입품이 10-15% 더 저렴한 가격에 판매되는 상황에 직면했고, 이는 국내 이익률에 영향을 미쳐 생산 능력 확장을 지연시켰습니다.
부문별 분석
그 밖의 특수 칼슘 알루미나 시멘트(CAC)는 2025년 판매량의 28.00%를 차지할 것으로 예측됩니다. 한편, 고알루미나 시멘트는 연평균 6.12%의 성장률을 보일 것으로 전망되는데, 이는 특히 전기 아크로 개조 시 1,600°C 이상의 열충격에 견딜 수 있는 모놀리식 내화물 수요에 힘입은 결과입니다. 이 부문의 기업들은 설계 지원을 제공함으로써 시장 규모에서의 우위를 활용하고 있으며, 철강 제조업체들이 제품 수명 연장에 주력함에 따라 고알루미나 시멘트 시장 점유율은 확대될 것으로 예측됩니다. 알루미나 함량 40-50%의 범용 등급은 중국 제조업체와의 경쟁으로 인해 이익률 압박에 직면해 있습니다. 그러나 EcoCaltrix와 같이 지속가능성에 중점을 둔 제품은 유럽의 공공 조달 시장에서 15-20%의 가격 프리미엄을 얻고 있습니다.
분말 형태는 내화물 배합 업체들이 수분 함량, 유동성 및 고온 강도를 조절할 수 있는 유연성을 요구하고 있기 때문에 2025년 수요의 46.00%를 차지하며 계속해서 주류를 이룰 것으로 전망됩니다. 한편, 프리믹스 포장은 특히 긴급 포장 보수 분야에서 작업 효율성과 배치 품질의 일관성을 추구하는 시공업체들 수요에 힘입어 연평균 성장률(CAGR) 6.23%로 성장할 것으로 전망됩니다. 페이스트 및 슬러리 형태는 틈새 제품으로 남아 있지만, 펌프 이송이 가능하고 고온의 기판에 대한 강력한 접착력을 갖추고 있어 25-30%의 매출 총이익률을 달성할 것으로 예측됩니다. 이러한 특성들은 도자기 가마나 가마 껍데기 보수와 같은 용도에서 필수적인 요소입니다.
분말은 2025년 예상 판매량의 46.00%를 차지하고 있어, 벌크 내화 캐스터블 혼합에서 그 중요성을 보여주고 있습니다. 제조업체는 특정 유변학적 특성 및 경화 시간 요건을 충족하기 위해 분말을 사용하여 알루미나 골재, 실리카 퓸, 분산제 및 알루미나 칼슘을 혼합하고 있습니다. 프리믹스 포장은 특히 신속한 보수 및 긴급 대응 용도에서 일관된 단일 공급원의 배합을 요구하는 시공업체 수요에 힘입어 연평균 성장률(CAGR) 6.23%를 나타낼 것으로 예측됩니다. 페이스트 및 슬러리 형태는 일반적으로 스프레이 도포나 흙손 도포용으로 설계된 틱소트로피성 배합으로, 유지보수 및 보수 분야에 적합합니다. 이러한 형태는 펌프 공급이 가능하고 고온의 기판(최대 800℃)에 대한 밀착성이 뛰어나다는 점이 높이 평가받고 있으며, 가마 외벽 보수나 용해로 패치 작업 등의 용도에 적합합니다. 형태별 세분화는 맞춤화와 편의성의 균형을 반영하고 있습니다. 분말은 내화물 용도에 맞춘 정밀한 배합 설계를 가능하게 하는 반면, 프리믹스 봉지는 사용 편의성과 숙련도가 낮은 작업자도 다룰 수 있다는 점에 중점을 두고 있어, 성능 면에서 약간의 타협이 필요합니다.
지역별 분석
아시아태평양은 2031년까지 46.50%의 시장 점유율을 유지하며 연평균 성장률(CAGR) 6.15%를 나타낼 것으로 전망됩니다. 이러한 성장은 인도 내 전기 아크로 보급률이 18% 상승하여 내화물 수요를 끌어올리고 있는 점, 그리고 가격 경쟁의 압박에도 불구하고 중국 생산자들이 생산 능력을 확대하고 있는 점이 주요 요인으로 작용하고 있습니다. 일본과 한국은 양보다 질을 중시하는 반면, 아세안(동남아시아국가연합) 국가들은 인프라 프로젝트, 특히 교량 건설 사업을 뒷받침하기 위해 수입된 포장형 알루민산 칼슘 시멘트(CAC)에 의존하고 있습니다.
북미에서는 2025년 RHI 마그네시타가 레스코를 인수한 것이 호재가 될 것으로 보입니다. 연방 정부의 인프라 자금이 신속한 복구 솔루션에 대한 수요를 견인할 것으로 예상되는 한편, 미주리주에 건설된 칼데리스사의 신규 공장으로 인해 중서부 지역 구매자에 대한 납기 기간이 30-40% 단축될 것으로 전망됩니다.
유럽은 지속가능성 혁신 분야에서 여전히 주도적인 위치를 차지하고 있지만, 2025년에는 산업용 시멘트 생산량이 12% 감소했습니다. 그럼에도 불구하고, DWA-A 143 기준에 따른 하수도 개량 사업과 탄소국경조정메커니즘(CBAM)의 탄소 가격 책정 체계는 저탄소(CO2) 시멘트 등급의 장기적인 성장 가능성을 시사하고 있습니다. 북유럽 국가들의 1인당 지출액이 높은 점은 생산량은 비교적 적음에도 불구하고 프리미엄 CAC에 대한 틈새 수요를 뒷받침하고 있습니다.
남미 시장 전망은 현지 생산자를 보호할 가능성이 있는 브라질의 반덤핑 관세 향방에 좌우될 것입니다. 또한, 아르헨티나의 광업 부문은 규모는 작지만 내화물 수요의 안정적인 기반을 제공합니다.
중동 및 아프리카의 성장은 사우디아라비아와 남아프리카공화국에 집중되어 있습니다. 이란에서는 주요 현지 공급업체들이 국내 수요의 90% 이상을 충당하고 있으며, 인근 석유화학 허브로도 수출을 진행함으로써 지역 시장의 안정에 기여하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.06.22According to Mordor Intelligence, the calcium aluminate cement market size is expected to increase from 3.96 million tons in 2025 to 4.16 million tons in 2026 and reach 5.39 million tons by 2031, growing at a CAGR of 5.32% over 2026-2031.
This report is Segmented by Type (High-Alumina Cement, Pre-Mixed Calcium Aluminate Cement, and More), Form (Powder, Premixed Bags, and More), Application (Refractories and More), End-User Industry(Steel and Metallurgy, Oil and Gas, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Calcium Aluminate Cement Market Trends and Insights
Growing Demand in Refractory Applications
India's transition to electric-arc furnaces increased the demand for refractory castables by 22% in 2023-24, driving higher consumption of calcium aluminate cement (CAC) due to its ability to maintain strength where Portland binders fail. This shift also results in energy savings of 60-70% per ton of steel, while compliance with India's Perform, Achieve, and Trade (PAT) scheme for mandated decarbonization supports sustained demand growth. Similarly, petrochemical cracker upgrades in the Middle East and China are adopting ultra-low cement castables, which combine CAC with reactive alumina to achieve a hot modulus of rupture exceeding 12 megapascals (MPa) at 1,400 degrees Celsius (°C), extending lining lifespans by 15-20%.
Rapid-Setting/High-Performance Concrete Adoption
Calcium sulfoaluminate variants achieve a strength of 35-40 MPa within 72 hours when using seawater, eliminating the need for freshwater in coastal precast yards and reducing carbon dioxide (CO2) emissions by up to 48% compared to Ordinary Portland Cement (OPC). In the United States, bridge-deck overlays funded under the Infrastructure Investment and Jobs Act require such fast-setting materials. Similarly, the Association of Southeast Asian Nations (ASEAN) Connectivity Master Plan permits the use of Calcium Aluminate Cement (CAC) binders to address a USD 210 billion infrastructure gap by 2030.
High Production Costs vs Portland Cement
Sintering at temperatures 100-150°C higher than Portland variants increases Calcium Aluminate Cement (CAC) energy consumption by 15-20% and results in a 25-30% price premium, limiting its adoption in applications where Ordinary Portland Cement (OPC) with accelerators is sufficient. In 2025, Indian buyers faced Chinese imports priced 10-15% lower, which impacted domestic margins and delayed capacity expansions.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Use in Sewerage and Waste-Water Infrastructure
- 3-D Printed Refractory Shapes Enable New CAC Binders
- Energy-Intensive, CO2-Heavy Manufacturing Process
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Other Specialty Calcium Aluminate Cement (CAC) is projected to account for 28.00% of the 2025 volume, while High-Alumina Cement is expected to grow at an annual rate of 6.12%, driven by the demand for monolithic refractories capable of withstanding thermal shocks of greater than or equal to 1,600 °C, particularly in electric-arc furnace retrofits. Companies in the segment utilize their market size advantage by offering design support, with High-Alumina Cement's market share anticipated to increase as steel producers focus on achieving longer campaign lifespans. Commodity grades with 40-50% alumina content face margin pressures due to competition from Chinese manufacturers. However, sustainability-focused products, such as EcoCaltrix, command a 15-20% price premium in Europe's public procurement channels.
Powder forms are expected to remain dominant, accounting for 46.00% of 2025 demand, as refractory formulators require flexibility to adjust water demand, flow characteristics, and hot strength. Premixed bags, on the other hand, are forecasted to grow at a compound annual growth rate (CAGR) of 6.23%, driven by contractors seeking labor efficiency and consistent batch quality, particularly for emergency pavement repairs. Paste and slurry forms will remain niche products but achieve 25-30% gross margins due to their pumpability and strong adhesion to hot substrates, which are essential for applications such as ladle and kiln-shell patching.
Powder accounted for 46.00% of the projected 2025 volume, indicating its significance in bulk refractory castable mixing. Producers use powder to blend calcium aluminate with alumina aggregates, silica fume, and dispersants to achieve specific rheology and setting time requirements. Premixed bags are expected to grow at a CAGR of 6.23%, driven by contractor demand for consistent, single-source formulations, particularly in rapid-repair and emergency-response applications. Paste/Slurry forms, which are typically thixotropic formulations designed for gunning or troweling, cater to maintenance and repair segments. These forms are valued for their pumpability and ability to adhere to hot substrates (up to 800 degrees Celsius), making them suitable for applications such as kiln-shell repairs and ladle patching. The segmentation by form reflects a balance between customization and convenience: powder allows for precise mix designs tailored to refractory applications, while premixed bags focus on ease of use and reduced labor skill requirements, with some trade-offs in performance potential.
Geography Analysis
Asia-Pacific is projected to retain its 46.50% market share through 2031, with an annual growth rate of 6.15%. This growth is driven by India's 18-percentage-point increase in electric-arc furnace penetration, boosting refractory demand, and capacity expansions by Chinese producers despite competitive pricing pressures. Japan and South Korea prioritize quality over volume, while ASEAN (Association of Southeast Asian Nations) countries depend on imported bagged calcium aluminate cement (CAC) to support infrastructure projects, particularly bridge construction programs.
North America is expected to benefit from RHI Magnesita's acquisition of Resco in 2025. Federal infrastructure funding is anticipated to drive demand for rapid-repair solutions, while Calderys' new plant in Missouri is projected to reduce lead times by 30-40% for buyers in the Midwest region.
Europe continues to lead in sustainability innovations, but experienced a 12% contraction in industrial cement production in 2025. Despite this, sewer upgrades under DWA-A 143 standards and the Carbon Border Adjustment Mechanism's (CBAM) carbon pricing framework indicate long-term growth potential for low-carbon dioxide (CO2) cement grades. High per-capita spending in Nordic countries supports niche demand for premium CAC, despite relatively low production volumes.
South America's market outlook hinges on Brazil's pending antidumping duties, which could protect local producers. Additionally, Argentina's mining sector provides a stable, though modest, baseline for refractory demand.
Growth in the Middle East and Africa is concentrated in Saudi Arabia and South Africa. In Iran, a dominant local supplier meets over 90% of domestic demand and exports to neighboring petrochemical hubs, contributing to regional market stability.
- Almatis
- Caltra Nederland B.V.
- Carborundum Universal Ltd. (CUMI)
- Cimsa
- Denka Company Limited
- Elfusa S/A
- Etex (Ex-Kerneos Latin America)
- Fengrun Metallurgy Material
- Gorka Cement
- Imerys
- Molins
- Refratechnik Group
- RHI Magnesita
- Royal White Cement
- Taiheiyo Cement Corp.
- Target Products Ltd.
- Union Cement Company
- Vicat Group
- Zhengzhou Dengfeng Smelting Materials
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand in refractory applications
- 4.2.2 Rapid-setting/high-performance concrete adoption
- 4.2.3 Expanding use in sewerage and waste-water infrastructure
- 4.2.4 3-D printed refractory shapes enable new CAC binders
- 4.2.5 Low-CO2, energy-efficient CAC production processes
- 4.3 Market Restraints
- 4.3.1 High production costs vs Portland cement
- 4.3.2 Energy-intensive, CO2-heavy manufacturing process
- 4.3.3 Supply risk of high-purity bauxite feedstock
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 High-Alumina Cement (CA-50/60)
- 5.1.2 Low-Cement Castables
- 5.1.3 Pre-Mixed/Premixed CAC
- 5.1.4 Ultra-Low Cement and Insulating Grades
- 5.1.5 Other Specialty CAC (FCA 40-90)
- 5.2 By Form
- 5.2.1 Powder
- 5.2.2 Paste / Slurry
- 5.2.3 Premixed Bags
- 5.3 By Application
- 5.3.1 Refractories
- 5.3.2 Construction and Rapid-Repair
- 5.3.3 Chemicals and Petrochemicals
- 5.3.4 Water and Waste-Water Treatment
- 5.3.5 Mining and Power Generation
- 5.4 By End-user Industry
- 5.4.1 Steel and Metallurgy
- 5.4.2 Oil and Gas
- 5.4.3 Infrastructure and Public Works
- 5.4.4 Manufacturing and Process Plants
- 5.4.5 Others (Marine, Energy Storage)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Almatis
- 6.4.2 Caltra Nederland B.V.
- 6.4.3 Carborundum Universal Ltd. (CUMI)
- 6.4.4 Cimsa
- 6.4.5 Denka Company Limited
- 6.4.6 Elfusa S/A
- 6.4.7 Etex (Ex-Kerneos Latin America)
- 6.4.8 Fengrun Metallurgy Material
- 6.4.9 Gorka Cement
- 6.4.10 Imerys
- 6.4.11 Molins
- 6.4.12 Refratechnik Group
- 6.4.13 RHI Magnesita
- 6.4.14 Royal White Cement
- 6.4.15 Taiheiyo Cement Corp.
- 6.4.16 Target Products Ltd.
- 6.4.17 Union Cement Company
- 6.4.18 Vicat Group
- 6.4.19 Zhengzhou Dengfeng Smelting Materials
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Demand for corrosion-resistant, high-performance binders in circular infrastructure
- 7.3 Green-cement technology integration and sustainable construction pathways


