|
시장보고서
상품코드
2062145
텍스처 페인트 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Texture Paints - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, texture 페인트 시장 규모는 2025년 147억 3,000만 달러에서 2026년에는 154억 8,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 5.12%로 성장을 지속하여, 2031년에는 198억 8,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 제품 유형(샌드 텍스처, 스무스 텍스처, 팝콘 및 녹다운 등), 기질 유형(내벽, 외벽, 천장, 목재 및 금속 표면), 최종 사용자 산업(주택, 상업, 산업) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 텍스처 페인트 시장 동향 및 분석
저VOC 텍스처를 장려하는 그린빌딩 인증
LEED, BREEAM, WELL 등의 인증 프로그램에서는 현재 실내용 도료의 VOC 함량을 30-50 g/L로 제한하고 있으며, 이에 따라 용제형 바인더에서 수성 아크릴계 및 바이오 수지로의 전환이 진행되고 있습니다. EU 에코라벨은 2026년을 목표로 반휘발성 물질의 기준치를 더욱 엄격히 하고, 미세 플라스틱의 수명 주기 공개를 의무화하고 있으며, 이에 따라 기존의 아크릴 코폴리머는 사실상 단계적으로 폐지될 예정입니다. 아르케마의 ‘Synaqua 4804’ 분산액이나 슈윈 윌리엄스의 ‘Repacor SW-1000’ 시스템과 같은 제품들은 텍스처 페인트 시장이 이러한 변화에 적응하고 있음을 보여줍니다. 대형 건설사들은 로트 단위의 VOC 인증 혜택을 받고 있으며, 이를 통해 고객은 그린빌딩 포인트를 획득할 수 있습니다. 그 결과, 2단계 가격 체계가 형성되어 인증을 받은 저VOC 텍스처 도료는 15-20%의 프리미엄 가격이 붙는 반면, 비용을 중시하는 신흥 시장에서는 용제계 대체품이 여전히 일반적입니다.
밀레니얼 세대의 주택 소유 프리미엄화 동향
30-44세 주택 소유자들이 베네치안 플라스터, 녹다운, 샌드스월과 같은 텍스처 마감재에 대한 수요를 주도하고 있습니다. 이 제품들은 촉감과 미적 매력 덕분에 평면 마감 제품보다 25-40% 높은 가격으로 책정되어 있습니다. 인도에서는 ‘프라단 만트리 아와스 요자나(Pradhan Mantri Awas Yojana)’ 프로그램을 통해 2026년에는 장식용 도료 판매량이 4-5% 증가할 것으로 예상되며, 텍스처 마감재가 이러한 성장에 크게 기여하고 있습니다. 2024년에 출시된 ‘Birla White Textura’ 등의 제품은 미리 혼합된 시멘트 기반 텍스처를 제공하여 시공 시간을 30% 단축합니다. 유통망이 2선 도시로 확대됨에 따라, 텍스처 도료 시장은 틈새 시장 카테고리에서 대중 프리미엄 카테고리로 전환되고 있습니다. 각 제조업체는 자사 브랜드와의 경쟁에 직면한 가운데, 이익률을 유지하면서 생산 규모를 확대해야 하는 과제에 직면해 있습니다.
이산화티타늄(TiO2) 및 광물 골재 가격 변동
베네이터사의 파산과 트로녹스사의 공장 폐쇄를 배경으로, 이산화티타늄 가격은 2025년 톤당 3,200달러에서 2026년에는 3,500달러에 달할 것으로 전망됩니다. 중국산 이산화티타늄 수입에 대한 EU의 반덤핑 관세는 비용 부담을 더욱 가중시키고 있습니다. 300달러의 가격 인상은 소비자에게 전가되지 않는 한, 매출 총이익률을 3-5% 하락시킬 가능성이 있습니다. 이에 대해 각 제조업체는 이산화티타늄의 배합 비율을 낮추거나, 인도나 튀르키예에서 조달하거나, 혹은 안료 생산을 통합하는 등의 조치를 취하고 있습니다. 예를 들어, 아시안 페인트(Asian Paints)사가 2억 1,700만 달러를 투자해 추진 중인 인돌(Indore) 확장 계획에는 새로운 분산 생산 라인이 포함되어 있습니다. 단기적인 가격 변동으로 인해 2027년까지 가격은 톤당 4,000달러를 넘어설 가능성이 있습니다.
부문별 분석
2025년 기준으로, 샌드 텍스처는 텍스처 페인트 시장 점유율의 36.11%를 차지했습니다. 롤온 텍스처 시장은 색상 선택을 간소화하는 AI 도구와 배합 실수를 최소화하는 프리믹스 키트의 보급에 힘입어, 2031년까지 연평균 성장률(CAGR) 5.08%로 성장할 것으로 전망됩니다. 팝콘 마감이나 녹다운 텍스처는 미적 취향이 다양하다는 점과 방음 효과 덕분에, 공동 주택에서 서서히 다시 인기를 얻고 있습니다. 매끄러운 마감이 요구되는 고급 인테리어에서는 여전히 매끄러운 마감 처리가 선호되고 있습니다. 한편, 오렌지 필 텍스처는 베이스 코팅의 미세한 결점을 가리는 데 비용 효율이 뛰어나 일반 주택 시장에서 주류를 이루고 있습니다. 규제 동향은 수성 화학제품을 뒷받침하고 있으며, 규제를 준수하는 롤온 제품 라인을 보유한 제조업체는 시장 점유율을 점차 확대할 수 있을 것으로 보입니다.
지역별 선호도가 수요에 큰 영향을 미치고 있습니다. 밀레니얼 세대와 Z세대 구매층의 미니멀리즘 경향에 따라, 시장 점유율은 절제된 질감의 제품으로 이동하고 있습니다. 2026년부터 시행되는 EU 에코라벨 규정에 따라 수성 바인더의 사용이 의무화됨에 따라, 유럽 내 용제계 팝콘 스프레이의 단계적 폐지가 가속화되고 있습니다. 마찬가지로, 캘리포니아주 SCAQMD 규정 제1113호 역시 엄격한 VOC(휘발성 유기 화합물) 제한을 부과하고 있습니다. 저VOC의 매끄러운 마감이나 샌드 마감 제품에 투자해 온 제조업체들은 현재 매장 내 진열 공간 확대라는 혜택을 누리고 있는 반면, 기타 제조업체들은 배합 변경이라는 과제에 직면해 있습니다.
지역별 분석
아시아태평양은 2025년 텍스처 페인트 시장 매출의 38.89%를 차지해, 2031년까지 연평균 성장률(CAGR) 5.45%로 성장할 전망입니다. 2025년 중국의 도료 총생산량은 전년 대비 9.4% 감소했으나, 고급 인조석 및 아트 텍스처 제품 시장 점유율이 확대되고 있어, 생산량 감소 국면에서도 고부가가치 제품으로의 전환이 반영되고 있습니다. 동남아시아 및 중동에서는 차열 및 항균 도료를 지정하는 대규모 프로젝트에 힘입어 성장이 예상됩니다.
북미의 텍스처 페인트 시장은 상업용 건축물과 엄격한 저VOC 규제에 힘입어 성장하고 있습니다. 캘리포니아주의 VOC 상한치 50g/L는 수성 제품의 도입을 가속화하고 있습니다. 경제의 불확실성이 수요를 위축시키고 있는 반면, 독일과 프랑스의 리모델링 지원금 제도가 신축 착공 부진의 영향을 완화하고 있습니다. 중동 및 아프리카는 사우디아라비아와 아랍에미리트(UAE)의 대규모 개발로 인한 혜택을 누리고 있습니다. 라틴아메리카에서는 데이터의 적용 범위가 여전히 제한적이지만, 슈윈 윌리엄스가 수비닐을 11억 5,000만 달러에 인수한 것은 특히 브라질의 현지 원료 기반이 세계 가격 변동으로부터 이익률을 보호하는 데 일조하고 있다는 점을 고려할 때, 낙관적인 전망을 보여줍니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.06.19According to Mordor Intelligence, the texture paints market size is expected to grow from USD 14.73 billion in 2025 to USD 15.48 billion in 2026 and is forecast to reach USD 19.88 billion by 2031 at 5.12% CAGR over 2026-2031.
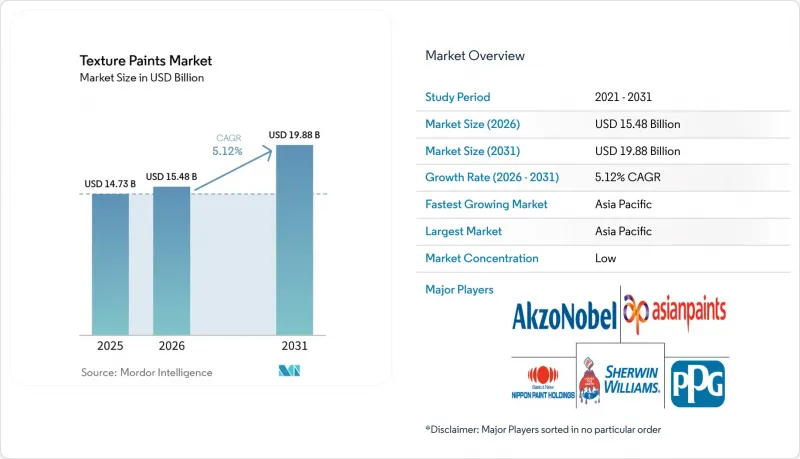
This report is Segmented by Product Type (Sand Texture, Smooth Texture, Popcorn and Knock-Down, and More), Substrate Type (Interior Walls, Exterior Walls, Ceilings, and Wood and Metal Surfaces), End-User Industry (Residential, Commercial, and Industrial), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Texture Paints Market Trends and Insights
Green-Building Certification Driving Low-VOC Textures
Programs like LEED, BREEAM, and WELL now limit VOC content in interior paints to 30-50 g/L, leading to a shift from solvent-borne binders to waterborne acrylics and bio-based resins. The EU Ecolabel has further tightened semi-volatile thresholds for 2026 and requires life-cycle disclosure of microplastics, effectively phasing out traditional acrylic copolymers. Products such as Arkema's Synaqua 4804 dispersion and Sherwin-Williams' Repacor SW-1000 system demonstrate the market's texture paints market's adaptation. Large contractors benefit from batch-level VOC certification, which helps clients earn green-building points. This has resulted in a two-tier pricing structure, with certified low-VOC textures commanding a 15-20% premium, while solvent-borne alternatives remain common in cost-sensitive emerging markets.
Premiumization Trend in Millennial Home Ownership
Homeowners aged 30-44 are driving demand for textured finishes like Venetian plaster, knockdown, and sand-swirl, which are priced 25-40% higher than flat finishes due to their tactile and aesthetic appeal. In India, the Pradhan Mantri Awas Yojana program has driven decorative paint volume growth of 4-5% in FY 2026, with textured finishes contributing significantly to value growth. Products such as Birla White Textura, launched in 2024, offer pre-mixed cement-based textures that reduce labor time by 30%. Distribution networks are expanding into tier-2 cities, transitioning texture paints from niche to mass-premium categories within the texture paints market. Manufacturers face the challenge of scaling production while maintaining margins against competition from private-label brands.
Volatile TiO2 and Mineral-Aggregate Prices
Titanium dioxide prices are projected to reach USD 3,500 per ton in 2026, up from USD 3,200 in 2025, driven by Venator's bankruptcy and the closure of Tronox's plant. EU anti-dumping duties on Chinese TiO2 imports further exacerbate cost pressures. A USD 300 price increase could reduce gross margins by 3-5% unless passed on to consumers. Manufacturers are responding by lowering TiO2 content, sourcing from India and Turkey, or integrating pigment production. For example, Asian Paints' USD 217 million Indore expansion includes new dispersion lines. Short-term volatility could push prices above USD 4,000 per ton by 2027.
Other drivers and restraints analyzed in the detailed report include:
- AI-Powered Color-Matching Tools Accelerating DIY Adoption
- Micro-Ceramic Additives Enabling Thermo-Regulating Textures
- Skill Gap in Spray-Applied High-Build Textures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sand texture accounted for 36.11% of the texture paints market share in 2025. Roll-on texture is anticipated to grow at a compound annual growth rate (CAGR) of 5.08% through 2031, supported by AI tools that simplify color selection and pre-mixed kits that minimize blending errors. Popcorn and knockdown textures are seeing a modest resurgence in multifamily housing due to their acoustic advantages, despite varying aesthetic preferences. Smooth finishes remain the preferred choice for premium interiors requiring seamless drywall, while orange peel textures dominate mass housing due to their cost-effectiveness in masking minor substrate imperfections. Regulatory trends favor waterborne chemistry, enabling producers with compliant roll-on lines to achieve incremental market gains.
Regional preferences significantly influence demand. Minimalist themes among millennial and Gen-Z buyers are shifting market share toward subtle textures. The EU Ecolabel regulations, effective since 2026, mandate waterborne binders, accelerating the phase-out of solvent-borne popcorn sprays in Europe. Similarly, California's SCAQMD Rule 1113 imposes stringent VOC limits. Manufacturers that invested in low-VOC smooth and sand products now benefit from expanded shelf space, while others face reformulation challenges.
Geography Analysis
Asia-Pacific generated 38.89% of texture paints market revenue in 2025 and is set to grow at a CAGR of 5.45% through 2031. Despite a 9.4% year-on-year decline in China's total coatings output in 2025, premium faux-stone and art textures gained market share, reflecting a shift toward higher-value products even amid volume contraction. Southeast Asia and the Middle-East are experiencing growth driven by large-scale projects specifying heat-reflective and bacteria-resistant coatings.
North America's texture paint industry market is supported by commercial construction and stringent low-VOC regulations. California's VOC limit of 50 g/L is accelerating the adoption of waterborne products. While economic uncertainty dampens demand, renovation subsidies in Germany and France are mitigating the impact of slower new construction. The Middle-East and Africa are benefiting from mega-developments in Saudi Arabia and the UAE. In Latin America, data coverage remains limited, but Sherwin-Williams' USD 1.15 billion acquisition of Suvinil highlights optimism, particularly given Brazil's local raw material base, which helps shield margins from global price fluctuations.
- Akzo Nobel N.V.
- Asian Paints Ltd.
- Behr Process LLC
- Benjamin Moore & Co.
- Berger Paints India
- DAW SE
- Hempel A/S
- Jazeera Paints
- Jotun
- JSW Paints Limited
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
- Tikkurila
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Green-building certification driving low-VOC textures
- 4.2.2 Premiumisation trend in millennial home ownership
- 4.2.3 AI-powered colour-matching tools accelerating DIY adoption
- 4.2.4 Micro-ceramic additives enabling thermo-regulating textures
- 4.2.5 3D-printed interior panels requiring high-adhesion coatings
- 4.3 Market Restraints
- 4.3.1 Volatile TiO2 and mineral-aggregate prices
- 4.3.2 Skill gap in spray-applied high-build textures
- 4.3.3 Competition from peel-and-stick architectural films
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Sand Texture
- 5.1.2 Smooth Texture
- 5.1.3 Popcorn and Knock-down
- 5.1.4 Orange Peel
- 5.1.5 Roll-on Texture
- 5.1.6 Other Product Types
- 5.2 By Substrate Type
- 5.2.1 Interior Walls
- 5.2.2 Exterior Walls
- 5.2.3 Ceilings
- 5.2.4 Wood and Metal Surfaces
- 5.3 By End-user Industry
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Asian Paints Ltd.
- 6.4.3 Behr Process LLC
- 6.4.4 Benjamin Moore & Co.
- 6.4.5 Berger Paints India
- 6.4.6 DAW SE
- 6.4.7 Hempel A/S
- 6.4.8 Jazeera Paints
- 6.4.9 Jotun
- 6.4.10 JSW Paints Limited
- 6.4.11 Kansai Paint Co., Ltd.
- 6.4.12 Nippon Paint Holdings Co., Ltd.
- 6.4.13 PPG Industries, Inc.
- 6.4.14 RPM International Inc.
- 6.4.15 The Sherwin-Williams Company
- 6.4.16 Tikkurila
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment