

|
시장보고서
상품코드
2066675
싱가포르의 접착제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Adhesives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
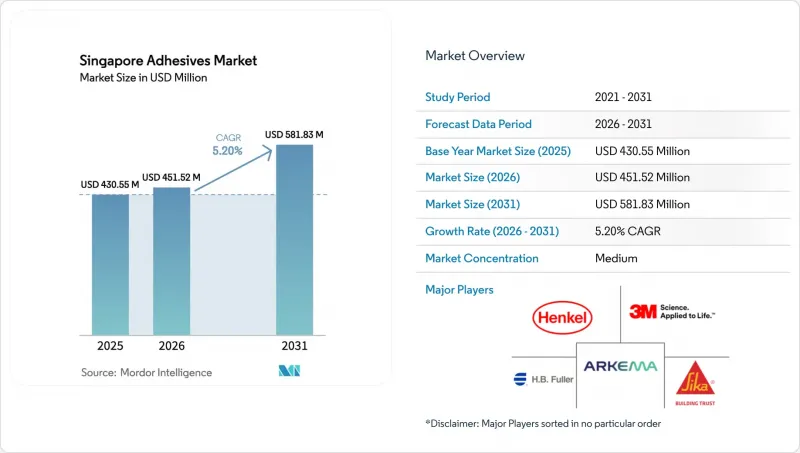
에 의하면, 싱가포르의 접착제 시장 규모는 2025년에 4억 3,055만 달러로 평가되었습니다. 2026년 4억 5,152만 달러에서 2031년까지 5억 8,183만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.20%를 나타낼 전망입니다.
본 보고서는 수지별(아크릴, 시아노아크릴레이트, 에폭시, 폴리우레탄, 실리콘 등), 기술별(핫멜트, 반응형, 용제형, UV 경화형, 수성), 최종 사용자 산업별(항공우주, 자동차, 건축 및 건설, 전자 및 전기, 신발·가죽, 헬스케어, 포장 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(톤) 단위로 제시되어 있습니다.
싱가포르의 접착제 시장 동향 및 분석
포장 분야 수요 증가
2026년에는 전 세계 소포 처리량이 2,660억 개에 달할 것으로 예상되며, 지역 물류 거점으로서 싱가포르의 역할 덕분에 그 흐름의 상당 부분이 창이 공항과 싱가포르 항구를 경유하고 있습니다. 현재, 최적화된 자동 포장 라인에서는 테이프 대신 핫멜트 접착제가 사용되고 있어, 자재 낭비를 줄이고 소포의 부피를 축소하는 동시에 재활용 공정과의 호환성을 확보하고 있습니다. 헨켈의 ‘Technomelt E-COM G5 Eco Cool’은 종이 재활용 공정을 위해 인증받은 바이오 저온 핫멜트 접착제의 대표적인 사례이며, 브랜드 소유주의 탄소 배출 감축 약속에 부합하는 제품입니다. 알케마(Arkema)가 2024년에 다우(Dow)의 연포장용 라미네이트 사업(2억 5,000만 달러 상당)을 인수함에 따라, 식품 및 의료용 필름을 위한 새로운 생산 능력이 확보되었습니다. 이들 모두 싱가포르의 수출 지향형 의약품 공급망을 활용하고 있습니다. 전반적으로, 2025년 포장 분야의 매출 점유율 38.55%는 운송 시 배출량과 총 소유 비용을 억제하는 고수익의 지속 가능한 솔루션으로의 전환을 이미 반영하고 있습니다.
지속 가능한 건축자재에 대한 정부의 장려
건축건설청(BCA)의 ‘그린마크’ 제도 및 싱가포르 그린빌딩 협의회(SGBC)의 제품 인증 체계에 따라, 입찰 서류에서 친환경 인증을 획득한 접착제의 중요성이 더욱 커지고 있습니다. 시카사의 ‘Davco Block Bond ECO’ 및 ‘Davco TTB ECO’는 재생 소재 함유율과 낮은 탄소 배출량을 바탕으로 현지 친환경 인증을 획득했습니다. NEA(환경청)가 2026년부터 시행할 도료 내 포름알데히드 금지 조치는 집성재 및 라미네이트용 접착제에 대한 향후 규제의 선구적 사례가 될 것이며, 2025년에 기록된 수성 기술 시장 점유율 42.25%를 더욱 끌어올리는 계기가 될 것입니다. 2028년까지 건설 부문의 연평균 성장률(CAGR)은 4.1%로 견조한 추세를 보이고 있으며, 여기에 더해 247억 싱가포르 달러 규모의 철도 건설 예산이 계획되어 있어 ‘그린마크’ 기준을 충족하는 타일용 접착제, 구조용 접착제, 실란트에 대한 수요가 유지되고 있습니다.
원자재 가격 변동
2026년 3월, 2-에틸헥실 아크릴레이트의 현물 가격이 53% 급등했습니다. 이는 원유 가격의 급등을 반영한 것으로, 프로파일렌 가격도 CFR 동남아시아 기준 42% 상승하여, 대부분의 원료를 수입하는 접착제 제조업체의 이익률을 압박했습니다. 와커 케미(Wacker Chemie)는 공급망 혼란을 이유로 2026년 4월부터 전 세계적으로 폴리머 분산액의 가격 인상을 단행했습니다. 원자재비는 총 생산 비용의 약 절반을 차지하기 때문에 싱가포르에 거점을 둔 가공업체들은 추가 비용을 소비자에게 전가할지, 아니면 이익률 하락을 감수할지 선택의 기로에 서 있습니다. 한편, 일부 도급업체는 접착제 가격이 예산 상한선을 초과할 경우 기계식 체결 장치로 전환하고 있습니다.
부문별 분석
2025년에는 의약품용 점착 라벨과 투명한 건축용 실런트의 호조에 힘입어 아크릴계 제품이 매출의 35%를 차지했습니다. 시아노아크릴레이트 계열은 시장 규모가 작은 편이지만, 웨어러블 생체 센서에 요구되는 30초 미만의 고정 시간을 고려할 때 연평균 성장률(CAGR) 6.56%를 나타낼 것으로 전망됩니다. H.B. 풀러사의 ‘SurgiSeal’과 같은 프리미엄 등급 제품은 항균 효과와 피부 친화성을 모두 갖추고 있어 더 높은 이익률을 실현하고 있습니다. 에폭시계 및 폴리우레탄계는 구조용 접착 분야에서 기존 사양을 유지하고 있지만, 저배출 규제를 충족하기 위해 프리폴리머화 이소시아네이트 및 바이오 폴리올로의 전환이 요구되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the singapore adhesives market size was valued at USD 430.55 million in 2025 and is estimated to grow from USD 451.52 million in 2026 to reach USD 581.83 million by 2031, at a CAGR of 5.20% during the forecast period (2026-2031).
This report is Segmented by Resin (Acrylic, Cyanoacrylate, Epoxy, Polyurethane, Silicone, and More), Technology (Hot Melt, Reactive, Solvent-Borne, UV-Cured, and Water-Borne), End-User Industry (Aerospace, Automotive, Building and Construction, Electronics and Electrical, Footwear and Leather, Healthcare, Packaging, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Tons).
Singapore Adhesives Market Trends and Insights
Growing Demand from Packaging Sector
Global parcel traffic is expected to hit 266 billion shipments in 2026, and Singapore's role as a regional fulfillment node channels much of that flow through Changi Airport and the Port of Singapore. Automated right-sized packaging lines now substitute hot-melt adhesives for tape, cutting material waste and parcel cube while enabling recycling-stream compatibility. Henkel's Technomelt E-COM G5 Eco Cool exemplifies bio-based, low-temperature hot melts certified for paper recycling streams, aligning with brand owners' carbon-reduction pledges. Arkema's 2024 purchase of Dow's USD 250 million flexible-packaging laminating business injects fresh capacity for food-grade and medical films, both of which draw on Singapore's export-oriented pharma supply chain. Collectively, packaging's 38.55% revenue share in 2025 already reflects a pivot toward higher-margin sustainable solutions that tamp down shipping emissions and total-cost-of-ownership.
Government Push for Sustainable Building Materials
The Building and Construction Authority's Green Mark scheme and the Singapore Green Building Council's product-certification framework now elevate eco-labeled adhesives in tender documents. Sika's Davco Block Bond ECO and Davco TTB ECO have secured local ecolabels based on recycled content and low embodied carbon. NEA's 2026 formaldehyde ban in paints signposts forthcoming limits on engineered-wood and laminate adhesives, reinforcing the 42.25% water-borne technology share recorded in 2025. Steady 4.1% construction-sector CAGR through 2028, coupled with SGD 24.7 billion in planned rail outlays, sustains demand for tile bonding, structural agents, and sealants that pass Green Mark thresholds.
Volatility in Raw-Material Prices
Spot prices for 2-ethylhexyl acrylate jumped 53% in March 2026, mirroring crude-oil shocks that also lifted propylene 42% in CFR Southeast Asia, squeezing margins for adhesive formulators that import most feedstocks. Wacker Chemie responded with global price hikes on polymer dispersions effective April 2026, citing supply-chain disruptions. Because raw materials represent around half of total production cost, Singapore-based converters either pass along surcharges or risk margin erosion, while some contractors revert to mechanical fasteners when adhesive prices exceed budget caps.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Electronics Manufacturing Hub
- Infrastructure Repair and Upgrades
- Stringent VOC and Chemical Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylics held 35% of revenue in 2025, buoyed by pressure-sensitive labels for pharmaceuticals and clear construction sealants. Cyanoacrylates, though a smaller base, are slated for a 6.56% CAGR on the back of sub-30-second fixture times demanded in wearable biosensors. Premium grades such as H.B. Fuller's SurgiSeal combine antimicrobial efficacy with skin flexibility, fetching higher margins. Epoxies and polyurethanes retain specification in structural bonding but must adapt to low-emission mandates by shifting toward pre-polymerized isocyanates and bio-based polyols.
List of Companies Covered in this Report:
- 3M
- ALTECO Co., Ltd.
- Arkema
- Ashland Global Holdings Inc.
- Avery Dennison Corporation
- DIC Corporation
- Dow Inc.
- Dymax Corporation
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Huntsman International LLC
- ITW Plexus
- LORD Corporation (Parker Hannifin)
- Mapei S.p.A.
- NANPAO Resins Chemical
- Permabond LLC
- Pidilite Industries Ltd.
- Sika AG
- Wacker Chemie AG
- Yamato Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand from packaging sector
- 4.2.2 Government push for sustainable building materials
- 4.2.3 Expansion of electronics manufacturing hub
- 4.2.4 Infrastructure repair and upgrades
- 4.2.5 Rise of biomedical device adhesives clusters
- 4.3 Market Restraints
- 4.3.1 Volatility in raw-material prices
- 4.3.2 Stringent VOC and chemical regulations
- 4.3.3 Competition from mechanical fasteners in construction
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Distribution Channel Analysis
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Resin
- 5.1.1 Acrylic
- 5.1.2 Cyanoacrylate
- 5.1.3 Epoxy
- 5.1.4 Polyurethane
- 5.1.5 Silicone
- 5.1.6 VAE / EVA
- 5.1.7 Other Resins
- 5.2 By Technology
- 5.2.1 Hot Melt
- 5.2.2 Reactive
- 5.2.3 Solvent-borne
- 5.2.4 UV-Cured
- 5.2.5 Water-borne
- 5.3 By End-user Industry
- 5.3.1 Aerospace
- 5.3.2 Automotive
- 5.3.3 Building and Construction
- 5.3.4 Electronics and Electrical
- 5.3.5 Footwear and Leather
- 5.3.6 Healthcare
- 5.3.7 Packaging
- 5.3.8 Woodworking and Joinery
- 5.3.9 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 ALTECO Co., Ltd.
- 6.4.3 Arkema
- 6.4.4 Ashland Global Holdings Inc.
- 6.4.5 Avery Dennison Corporation
- 6.4.6 DIC Corporation
- 6.4.7 Dow Inc.
- 6.4.8 Dymax Corporation
- 6.4.9 H.B. Fuller Company
- 6.4.10 Henkel AG & Co. KGaA
- 6.4.11 Huntsman International LLC
- 6.4.12 ITW Plexus
- 6.4.13 LORD Corporation (Parker Hannifin)
- 6.4.14 Mapei S.p.A.
- 6.4.15 NANPAO Resins Chemical
- 6.4.16 Permabond LLC
- 6.4.17 Pidilite Industries Ltd.
- 6.4.18 Sika AG
- 6.4.19 Wacker Chemie AG
- 6.4.20 Yamato Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


