

|
시장보고서
상품코드
2066678
미국의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United States Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
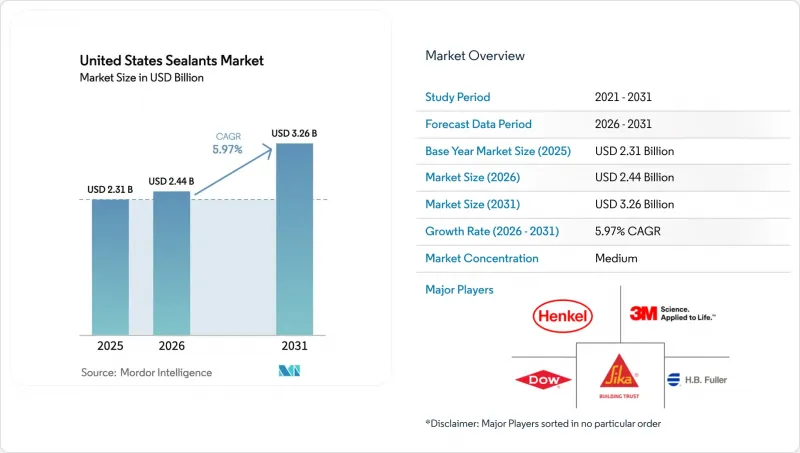
에 의하면, 미국의 실란트 시장 규모는 2025년 23억 1,000만 달러로 평가되었습니다. 2026년 24억 4,000만 달러에서 2031년까지 32억 6,000만 달러에 이를 것으로 예상되며 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 5.97%를 나타낼 전망입니다.
본 보고서는 수지 유형(아크릴, 에폭시, 폴리우레탄, 실리콘, 폴리설파이드 등), 기술(용제계, 수계 등), 최종 사용자 산업(항공우주, 자동차, 건축 및 건설, 의료, 기타 최종 사용자 산업) 및 지역(북동부, 중서부, 남부, 서부)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국의 실란트 시장 동향 및 인사이트
주택 리모델링의 급증으로 유연성이 뛰어난 실란트 솔루션에 대한 수요가 증가하고 있습니다.
주택담보대출의 고정금리 영향에 얽매여 있는 주택 소유자들은 가처분 소득을 시공이 용이한 아크릴 라텍스계나 실리콘계 코킹재를 사용한 주방, 욕실 및 외관 리모델링에 사용하고 있습니다. 전미주택건설업협회(NAHB)는 2026년에 리모델링 지출이 3% 증가하고, 2027년에는 2% 더 증가할 것으로 전망하고 있는 반면, CivicScience의 여론조사에 따르면 주택 소유자의 58%가 12개월 이내에 리모델링 프로젝트를 계획하고 있습니다. 미국 환경보호청(EPA)의 메소드 24를 준수하는 수성 아크릴계 실란트는 경화 속도가 빠르고 즉시 재도장이 가능하기 때문에 실내 마감 공사에서 주로 사용되고 있습니다. 이에 대응하여 각 제조업체들은 곰팡이에 강하고, 색이 잘 바래지 않으며, 비누와 물로 쉽게 세척할 수 있는 저탄성 실란트를 출시하고 있습니다. 이러한 특징 덕분에, 1피트당 가격 표시가 업체나 DIY 구매자의 선택에 영향을 미치는 소매점의 진열 공간을 확보하는 데 도움이 되고 있습니다.
연방 인프라 자금이 고속도로 및 교량의 유지 관리에 있어 실란트 사용을 촉진하고 있습니다.
‘인프라 투자 및 고용법(IIJA)’은 2026 회계연도까지 고속도로 사업에 약 3,500억 달러를 배정하고 있으며, 콘크리트 이음매 보수 및 신축 이음매 개보수 관련 계약 발주를 촉진하고 있습니다. 2026 회계연도 연방 예산안에서는 미집행된 충전 인프라 보조금 40억 달러의 취소가 제안되었으나, 각 주 교통국은 ASTM의 변위 요건을 충족하는 열경화형 고무 아스팔트계, 실리콘계 및 폴리설파이드계 실란트를 계속해서 지정하고 있습니다. ASTM C794에 따른 접착 강도 및 ±25%의 변위 능력 등 전국적인 성능 기준에 기반한 사양에 따라, 제3자 기관의 시험 비용을 부담하고 여러 주에서 승인 관리를 수행할 수 있는 공급업체에 대한 수요가 집중되고 있습니다. 인증 시험소를 갖추지 못한 소규모의 지역 밀착형 컴파운더들은 진입 장벽이 높아지는 상황에 직면해 있습니다.
실리콘 원자재 가격 변동이 가격 전략에 영향을 미침
디메틸디클로로실란 및 폴리디메틸실록산의 원료 가격은 중국의 신장 및 내몽골과 같은 주요 거점의 에너지 비용 및 금속 실리콘 비용의 변동에 따라 변동하고 있습니다. 미국 노동통계국은 2025년 11월까지 알루미늄 압연 제품의 가격이 25% 상승했다고 보고했으며, 이는 광범위한 금속 가격 급등을 나타내는 지표로, 그 영향이 포장비 및 생산 간접비로 파급되고 있습니다. 수직 통합이나 장기 원료 조달 계약을 맺지 않은 배합 제조업체는 매출 총이익률 압박에 직면해 있어, 비용을 유통업체에 전가할 수밖에 없습니다. 이에 대한 경쟁적 대응책으로는 이중 조달, 자사용 모노머에 대한 투자, 그리고 유리 및 금속 파사드용 고부가가치 아세톡시 경화형 실리콘으로의 포트폴리오 전환 등을 들 수 있습니다. 이러한 분야에서는 단위당 가치가 높기 때문에 원자재 가격 변동을 상쇄할 수 있습니다.
부문별 분석
실리콘은 2025년 매출의 38.50%를 차지하며, 자외선 안정성과 -60°C에서 +200°C의 온도 범위가 요구되는 용도에서 미국의 실란트 시장 점유율의 기반을 이루었습니다. 하이브리드 및 SMP 시장은 자동차 및 파사드·유리창 사양 결정자들이 프라이머가 필요 없는 접착력이나 이소시아네이트가 없는 작업 환경을 우선시하는 경향이 있기 때문에 2031년까지 연평균 성장률(CAGR) 7.76%를 나타낼 것으로 예측됩니다. 폴리우레탄은 고속도로 이음매나 산업용 바닥재와 같은 틈새 시장을 유지하고 있는 반면, 수성 아크릴은 도장이 가능하고 물로 세척할 수 있다는 장점 덕분에 인테리어 리모델링 시장을 독점하고 있습니다.
하이브리드 및 SMP 제품은 프탈산계 가소제에 대한 규제 당국의 감시가 강화되고 있는 데서 혜택을 보고 있으며, 이는 배합 재검토를 촉진하고 있습니다. PPG사가 2027년 상반기에 가동을 시작할 예정인, 노스캐롤라이나주 셸비에 위치한 3억 8,000만 달러 규모의 공장은 항공기용 복합재용 특수 폴리설파이드 및 에폭시 제품 프로그램을 뒷받침하고 있으며, 범용 제품 수요가 SMP로 전환되고 있는 상황에서도 지속적인 수요가 확인되고 있습니다. 헨켈이 2억 7,000만 유로를 투자해 ATP Adhesive Systems를 인수함에 따라, 전기자동차 배터리 케이스용 하이브리드 기술 라인업이 강화되었으며, 운송 분야의 미국의 실란트 시장 규모 확대가 촉진되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the united states sealants market size is projected to expand from USD 2.31 billion in 2025 and USD 2.44 billion in 2026 to USD 3.26 billion by 2031, registering a CAGR of 5.97% between 2026 to 2031.
This report is Segmented by Resin Type (Acrylic, Epoxy, Polyurethane, Silicone, Polysulfide, and More), Technology (Solvent-Borne, Water-Borne, and More), End-User Industry (Aerospace, Automotive, Building and Construction, Healthcare, and Other End-User Industries), and Geography (Northeast, Midwest, South, West). The Market Forecasts are Provided in Terms of Value (USD).
United States Sealants Market Trends and Insights
Surge in Residential Renovation Driving Demand for Flexible Sealant Solutions
Homeowners constrained by mortgage lock-in effects are channeling discretionary income into kitchen, bath, and exterior upgrades that rely on easy-to-apply acrylic latex and silicone caulks. NAHB forecasts a 3% lift in remodeling outlays in 2026 and another 2% in 2027, while CivicScience polling shows 58% of owners plan a project within twelve months. Water-borne acrylics that meet Environmental Protection Agency Method 24 dominate interior work because they cure quickly and allow rapid repainting. Manufacturers are responding with mildew-resistant, low-modulus sealants that hold color stability and offer soap-and-water cleanup. These attributes help capture retail shelf space where price-per-linear-foot displays influence contractor and DIY buyer choices.
Federal Infrastructure Funding Accelerating Highway and Bridge Maintenance Sealant Use
The Infrastructure Investment and Jobs Act (IIJA) earmarks roughly USD 350 billion for highway programs through FY 2026, driving contract lettings for concrete-joint repair and expansion-joint upgrades. Even though the FY 2026 federal budget proposes rescinding USD 4 billion in unobligated charging-infrastructure grants, state transportation departments continue to specify hot-applied rubberized-asphalt, silicone, and polysulfide sealants that pass ASTM movement requirements. National performance-based specifications, including adhesion per ASTM C794 and +-25% movement capability, are consolidating demand among suppliers able to fund third-party testing and manage multi-state approvals. Smaller, regional compounders that lack accredited laboratories face increasing barriers to entry.
Volatility in Silicone Raw-Material Costs Impacting Pricing Strategies
Dimethyldichlorosilane and polydimethylsiloxane feedstock prices swing with energy and silicon-metal costs in China's Xinjiang and Inner Mongolia hubs. The Bureau of Labor Statistics noted a 25% rise in aluminum mill-shape prices through November 2025, a proxy for broader metals inflation that cascades into packaging and production overheads. Formulators without vertical integration or long-term feedstock contracts face gross-margin compression and must pass costs to distributors. Competitive responses include dual sourcing, captive monomer investments, and portfolio shifts toward premium acetoxy-cure silicones for glass and metal facades, where higher unit value can absorb raw-material volatility.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of EV Battery-Pack Liquid Gasketing in US Manufacturing Plants
- Growth of Modular Construction Requiring Pre-Applied Sealant Tapes and Foams
- Stricter VOC Regulations Limiting Use of Solvent-Based Sealants
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicones held 38.50% of 2025 revenue, anchoring the United States sealants market share in applications that demand UV stability and temperatures from -60 °C to +200 °C. Hybrids and SMPs are projected to deliver a 7.76% CAGR through 2031 as automotive and facade-glazing specifiers prioritize primer-less adhesion and isocyanate-free workplace profiles. Polyurethanes retain highway-joint and industrial-floor niches, while water-borne acrylics dominate interior remodeling because they are paintable and clean up with water.
Hybrid and SMP offerings benefit from regulatory scrutiny of phthalate plasticizers, driving reformulation momentum. PPG's USD 380 million Shelby, North Carolina, plant scheduled for H1 2027 underpins specialty polysulfide and epoxy programs for composite aircraft, confirming ongoing demand even as commodity volumes migrate toward SMPs. Henkel's EUR 270 million acquisition of ATP Adhesive Systems strengthens its hybrid-technology roster for EV battery enclosures, advancing the United States sealants market size in transportation end uses.
List of Companies Covered in this Report:
- 3M
- Arkema
- BASF SE
- Carlisle Companies Inc.
- Chem Link Inc.
- Dow
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Illinois Tool Works Inc.
- Kraton Corporation
- LORD Corporation (Parker Hannifin)
- MAPEI S.p.A.
- Momentive Performance Materials Inc.
- Pecora Corporation
- PPG Industries, Inc.
- RPM International Inc. (Tremco)
- Sherwin-Williams Company (Geocel)
- Sika AG
- Soudal Holding N.V.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in residential renovation driving demand for flexible sealant solutions
- 4.2.2 Federal infrastructure funding accelerating highway and bridge maintenance sealant use
- 4.2.3 Rising adoption of EV battery pack liquid gasketing in US manufacturing plants
- 4.2.4 Growth of modular construction requiring pre-applied sealant tapes and foams
- 4.2.5 Shift to health-care facility expansion boosting sterile and biocompatible sealant demand
- 4.3 Market Restraints
- 4.3.1 Volatility in silicone raw-material costs impacting pricing strategies
- 4.3.2 Stricter VOC regulations limiting use of solvent-based sealants
- 4.3.3 Emergent biobased adhesive technologies cannibalizing traditional sealant volumes
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Epoxy
- 5.1.3 Polyurethane
- 5.1.4 Silicone
- 5.1.5 Polysulfide
- 5.1.6 Hybrid and SMP
- 5.1.7 Other Resins
- 5.2 By Technology
- 5.2.1 Solvent-borne
- 5.2.2 Water-borne
- 5.2.3 Hot-melt
- 5.2.4 Reactive and Others
- 5.3 By End-user Industry
- 5.3.1 Aerospace
- 5.3.2 Automotive
- 5.3.3 Building and Construction
- 5.3.4 Healthcare
- 5.3.5 Other End-user Industries
- 5.4 By Region
- 5.4.1 Northeast
- 5.4.2 Midwest
- 5.4.3 South
- 5.4.4 West
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Arkema
- 6.4.3 BASF SE
- 6.4.4 Carlisle Companies Inc.
- 6.4.5 Chem Link Inc.
- 6.4.6 Dow
- 6.4.7 H.B. Fuller Company
- 6.4.8 Henkel AG & Co. KGaA
- 6.4.9 Illinois Tool Works Inc.
- 6.4.10 Kraton Corporation
- 6.4.11 LORD Corporation (Parker Hannifin)
- 6.4.12 MAPEI S.p.A.
- 6.4.13 Momentive Performance Materials Inc.
- 6.4.14 Pecora Corporation
- 6.4.15 PPG Industries, Inc.
- 6.4.16 RPM International Inc. (Tremco)
- 6.4.17 Sherwin-Williams Company (Geocel)
- 6.4.18 Sika AG
- 6.4.19 Soudal Holding N.V.
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


