

|
시장보고서
상품코드
2066681
이탈리아의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Italy Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
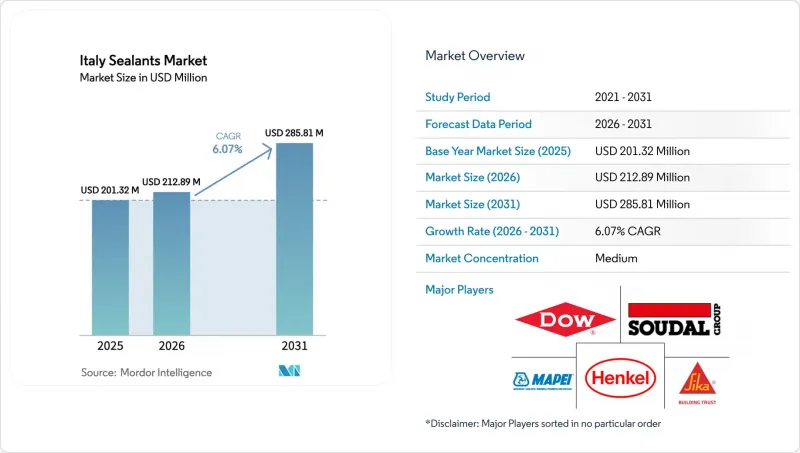
에 의하면, 이탈리아의 실란트 시장 규모는 2025년 2억 132만 달러로 평가되었습니다. 2026년에는 2억 1,289만 달러로 확대되어 2031년까지 2억 8,581만 달러에 이를 것으로 예상되며 2026년부터 2031년에 걸쳐 CAGR 6.07%로 성장할 전망입니다.
본 보고서는 수지 유형(아크릴, 에폭시, 폴리우레탄, 실리콘, 기타 수지) 및 최종 사용자 산업(항공우주, 자동차, 건축 및 건설, 의료, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
이탈리아의 실란트 시장 동향 및 분석
EU의 ‘리노베이션 붐’이 견인하는 개보수 수요
이탈리아의 ‘회복·탄력성 계획’에 따라 계획된 139억 5,000만 유로의 지출은 10만 채 이상의 건물과 3,600만 m²의 리모델링을 대상으로 하고 있으며, 이는 이탈리아의 실란트 시장의 리모델링 성장세를 뒷받침하고 있습니다. 2026년도 예산에서는 주 거주지 개보수에 대한 50%의 세액 공제가 지속됨에 따라, 아크릴계 및 저VOC 폴리우레탄계 시스템에 대한 꾸준한 수요 증가가 보장되고 있습니다. EN 16516 및 CDPH v1.2의 기준치(28일 시점에서 총 VOC 300µg/m3 이하, 포름알데히드 10µ g/m³ 이하)에 따라 적합해야 할 배합 요건이 엄격해졌으며, 아민 경화 시 발생하는 악취도 저감할 수 있는 수성 제품이 유리해지고 있습니다. 롬바르디아주, 라치오주, 캄파니아주 등 3개 주를 합치면 대상 건축 물량의 거의 절반을 차지하며, 지역 허브가 밀집해 있는 유통업체에게 물류상의 이점이 집중되어 있습니다. 수요는 기존의 실리콘계 파사드 이음매 마감재에서 프라이머 없이 다양한 기존 바탕면에 접착할 수 있는 하이브리드 실란트로 전환되고 있으며, 이미 26만 5,000명의 노동자가 부족한 시장에서 숙련된 노동자의 작업 시간을 단축하고 있습니다.
EV 배터리 경량화에 따른 실란트 수요
스텔란티스는 2030년까지 배터리 무게를 50% 줄이는 것을 목표로 하고 있으며, 토리노의 배터리 기술 센터에 4,000만 달러를 투자했습니다. 이로 인해 열전도성 및 유전성 실란트에 대한 현지 수요가 증가하고 있습니다. 현재 전기자동차에는 약 8파운드의 접착제 및 실란트가 사용되고 있지만, 새로운 셀-투-팩(cell-to-pack) 설계로 인해 2030년까지 그 사용량은 12파운드 정도까지 증가할 것으로 예상되며, 이는 이탈리아의 실란트 시장의 장기적인 판매량 증가를 뒷받침할 것입니다. 코라노사의 2액형 폴리우레아 시스템은 30초의 경화 시간을 실현하여, 현재 양산 단계에 접어든 모듈에서 기계식 체결 장치를 불필요하게 만들었습니다. 다우(Dow)사의 ‘VORATRON’ 폴리우레탄 등급은 0.3-3.1 W/mK의 열전도율을 실현하여 패시브 냉각을 가능하게 함으로써, 팩의 무게와 부피를 대폭 줄여줍니다. 이러한 사양에서는 -40°C-85°C의 작동 온도 범위와 20 kV/mm 이상의 절연 내력이 요구되고 있으며, 이로 인해 배합 설계자들은 실리콘이나 특수 폴리우레탄 계열 화학 물질을 채택하는 방향으로 이끌리고 있습니다.
실리콘 모노머 가격 변동
와커 케미(Wacker Chemie)는 백금 촉매 가격이 전년 대비 2배로 급등하고, 중동의 원료 공급 차질로 인해 디메틸디클로로실란공급이 감소함에 따라 2026년에 실리콘 가격을 두 차례 인상했습니다. 이로 인해 중간재의 85%를 수입에 의존하고 있는 이탈리아의 배합 제조업체들은 어려운 상황에 처해 있습니다. 백금은 실리콘 실란트의 제조원가(COGS)에서 최대 20%를 차지하고 있으며, 현물 가격은 2025년 온스당 900달러에서 2026년 3월까지 온스당 1,850달러로 상승했습니다. 다우사가 2026년 중반에 영국 배리에 위치한 실록산 생산 거점을 폐쇄하겠다고 발표함에 따라, 유럽의 생산 능력이 상실되고 비용 변동이 더욱 확대되면서 파사 볼트로와 케라콜 같은 지역 기업들의 이익률이 압박받고 있습니다.
부문별 분석
실리콘은 -60°C에서 200°C에 이르는 사용 온도 범위에서 타의 추종을 불허하는 자외선 내성을 갖추고 있어, 2025년 이탈리아의 실란트 시장에서 40.50%의 점유율을 차지했습니다. 이탈리아의 실란트 시장에서 아크릴계 배합 제품 시장 규모는 2031년까지 연평균 성장률(CAGR) 7.12%로 확대될 것으로 전망됩니다. 이는 아민 경화 시 악취가 없으며 40% 이상의 탄성 회복률을 실현하는 BASF사의 수성 ‘Acronal 5036’이 뒷받침하고 있기 때문입니다. 하이브리드 MS 폴리머와 폴리설파이드의 합산 점유율은 여전히 전체의 10% 미만에 그치고 있지만, 공항 포장이나 수중 구조물 등 특수한 접합 부위에서 일정한 입지를 유지하고 있습니다.
아크릴계 제품의 침투율 증가는 VOC를 50 g/L로 제한하는 ‘슈퍼 보너스’ CAM 기준과 직접적인 관련이 있습니다. 이 임계값은 용제계 폴리우레탄이 프라이머의 성능을 저해하지 않으면서 충족하기 어려운 수준입니다. 폴리우레탄은 2 MPa를 초과하는 인장 강도와 쇼어 A 경도 40-60을 자랑하며, 구조용 유리 공법 분야에서 여전히 주류를 차지하고 있습니다. 이러한 요소들은 산업용 바닥재나 파사드의 앵커 접합부에 있어 매우 중요합니다. 에폭시 수지는 혼합 과정이 복잡한 특성 및 화학 물질에 대한 불투과성을 활용하여, 제약용 바닥재나 클린룸과 같은 틈새 시장에서 입지를 다지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the italy sealants market size is expected to increase from USD 201.32 million in 2025 to USD 212.89 million in 2026 and reach USD 285.81 million by 2031, growing at a CAGR of 6.07% over 2026-2031.
This report is Segmented by Resin Type (Acrylic, Epoxy, Polyurethane, Silicone, and Other Resins) and End-User Industry (Aerospace, Automotive, Building and Construction, Healthcare, and Other End-User Industries). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Italy Sealants Market Trends and Insights
EU Renovation Wave-Fuelled Retrofit Demand
Planned spending of EUR 13.95 billion under Italy's Recovery and Resilience Plan covers more than 100,000 buildings and 36 million m2 of upgrades, sustaining retrofit momentum for the Italy Sealants market. The 2026 budget continues a 50% tax bonus on primary-residence renovations, guaranteeing steady pull-through for acrylic and low-VOC polyurethane systems. EN 16516 and CDPH v1.2 thresholds (less than or equal to 300 µg/m3 total VOC and less than or equal to 10 µg/m3 formaldehyde at 28 days) tighten qualifying formulations, favoring waterborne products that also mitigate amine-cure odor. Lombardy, Lazio, and Campania together host nearly half of the eligible building stock, concentrating logistics advantages for distributors with dense regional hubs. Demand shifts away from conventional silicone facade joints toward hybrid sealants able to bond mixed legacy substrates without primers, reducing skilled labor hours in a market already short 265,000 workers.
EV-Battery Lightweighting Sealant Needs
Stellantis targets a 50% battery-weight cut by 2030 and has invested USD 40 million in a Turin Battery Technology Center that boosts local demand for thermally conductive and dielectric sealants. Current electric vehicles carry roughly 8 lb of adhesives and sealants; new cell-to-pack designs may lift content toward 12 lb by 2030, supporting long-run volume upside for the Italy Sealants market. Two-component polyurea systems from Collano deliver 30-s fixture times, eliminating mechanical fasteners in modules now entering series production. Dow's VORATRON polyurethane grades add 0.3-3.1 W/mK thermal conductivity, allowing passive cooling that slashes pack weight and volume. These specifications demand service from -40°C to 85°C and dielectric strength more than or equal to 20 kV/mm, steering formulators toward silicone and specialty polyurethane chemistries.
Silicone-Monomer Price Volatility
Wacker Chemie raised silicone prices twice in 2026 after platinum catalysts doubled YoY and Middle-East feedstock disruptions reduced dimethyldichlorosilane supply, squeezing Italian formulators who import 85% of intermediates. Platinum represents up to 20% of silicone sealant COGS, and spot prices climbed from USD 900/oz in 2025 to USD 1,850/oz by March 2026. Dow's announced closure of its Barry, UK, siloxanes unit in mid-2026 removes European capacity, amplifying cost swings that depress margins for regional firms such as Fassa Bortolo and Kerakoll.
Other drivers and restraints analyzed in the detailed report include:
- Stricter VOC Limits Accelerating Water-Based Chemistries
- BIPV Facades Requiring Edge-Seal Longevity
- CE-Mark/CPR Compliance Cost Burden for SMEs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone commanded a 40.50% hold on the Italy Sealants market share in 2025, supported by unrivaled UV stability across -60°C to 200°C service windows. The Italy Sealants market size for acrylic formulations is projected to climb at a 7.12% CAGR through 2031, buoyed by BASF's waterborne Acronal 5036 that delivers more than or equal to 40% elastic recovery without amine-cure odor. Hybrid MS polymers and polysulfides together remain below 10% of volume, yet retain footholds in specialty joints such as airport pavements and submerged structures.
Acrylic's rising penetration links directly to Superbonus CAM criteria that cap VOC at 50 g/L, a threshold that solvent-borne polyurethane struggles to meet without primer sacrifices. Polyurethane continues to dominate structural glazing with tensile strengths of more than 2 MPa and Shore A 40-60, crucial to industrial flooring and facade anchor joints. Epoxy holds a niche in pharmaceutical floors and cleanrooms, leveraging chemical impermeability despite mixing complexity.
List of Companies Covered in this Report:
- 3M
- Arkema
- BASF SE
- Dow
- Fassa Bortolo
- General Sealants Inc.
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Index S.p.A.
- Kerakoll S.p.A.
- MAPEI S.p.A.
- NPT Srl
- Pidilite Industries Ltd.
- RPM International Inc.
- Saint-Gobain Weber
- Sika AG
- Soudal Holding N.V.
- Torggler S.r.l.
- Tremco CPG Italia
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 End-User Trends
- 4.3 Market Drivers
- 4.3.1 EU "Renovation Wave"-fuelled retrofit demand
- 4.3.2 EV-battery lightweighting sealant needs
- 4.3.3 Stricter VOC limits accelerating water-based chemistries
- 4.3.4 BIPV facades requiring edge-seal longevity
- 4.3.5 Robotic/3-D printed construction compatible hybrid sealants
- 4.4 Market Restraints
- 4.4.1 Silicone-monomer price volatility
- 4.4.2 CE-mark/CPR compliance cost burden for SMEs
- 4.4.3 Trade-skills shortage shifting demand to pre-gasketed systems
- 4.5 Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Epoxy
- 5.1.3 Polyurethane
- 5.1.4 Silicone
- 5.1.5 Other Resins
- 5.2 By End-user Industry
- 5.2.1 Aerospace
- 5.2.2 Automotive
- 5.2.3 Building and Construction
- 5.2.4 Healthcare
- 5.2.5 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 Arkema
- 6.4.3 BASF SE
- 6.4.4 Dow
- 6.4.5 Fassa Bortolo
- 6.4.6 General Sealants Inc.
- 6.4.7 H.B. Fuller Company
- 6.4.8 Henkel AG & Co. KGaA
- 6.4.9 Index S.p.A.
- 6.4.10 Kerakoll S.p.A.
- 6.4.11 MAPEI S.p.A.
- 6.4.12 NPT Srl
- 6.4.13 Pidilite Industries Ltd.
- 6.4.14 RPM International Inc.
- 6.4.15 Saint-Gobain Weber
- 6.4.16 Sika AG
- 6.4.17 Soudal Holding N.V.
- 6.4.18 Torggler S.r.l.
- 6.4.19 Tremco CPG Italia
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


