

|
시장보고서
상품코드
2066682
영국의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
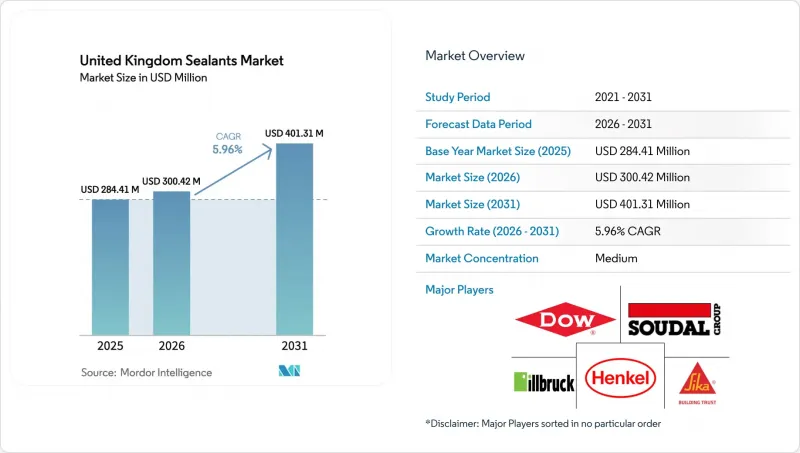
에 의하면, 영국의 실란트 시장 규모는 2025년 2억 8,441만 달러로 평가되었습니다. 2026년 3억 42만 달러에서 2031년까지 4억 131만 달러에 이를 것으로 예상되며 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 5.96%를 나타낼 전망입니다.
본 보고서는 수지 유형(아크릴, 에폭시, 폴리우레탄, 실리콘, 폴리설파이드, 하이브리드 실란 개질 폴리머(SMP), 기타 수지) 및 최종 사용자 산업(항공우주, 자동차, 건축 및 건설, 의료, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
영국의 실란트 시장 동향 및 분석
영국 고층 주택 리모델링 시장에서 내화 실란트 수요 증가
'건축물 안전법'에 따라, 잉글랜드 내 약 1만 2,500동의 고층 주택에서 내화성 실란트가 선택적 업그레이드 대상에서 필수 제품으로 전환되었습니다. 팽창성 아크릴계 및 실리콘계 실란트는 현재 EN 13501-1 규격 인증을 취득하고, 공극 차단 시스템과의 적합성을 입증해야 할 의무가 있으며, 제3자 기관의 시험 결과를 제시할 수 있는 브랜드를 조달하려는 경향이 강해지고 있습니다. 글렌펠 화재 이후의 조사 결과, 연기의 확산이 접합부의 결함에서 비롯된 것으로 밝혀졌으며, 이로 인해 고객사의 심사가 엄격해지면서 검증되지 않은 화학 성분에 대한 승인 절차가 장기화되고 있습니다. 철도 허브나 공항의 인프라 개보수에서도 내화성과 방음성이라는 두 가지 성능이 모두 요구되고 있으며, 이로 인해 공급업체의 선택 폭이 좁아지면서 높은 가격 책정이 부추겨지고 있습니다. EN 인증을 획득한 제품 라인을 보유하지 않은 중소규모의 배합 제조업체들은 지속적인 시험에 자금을 투입할 수 있는 다국적 공급업체에 시장 점유율을 내주고 있지만, 수요는 여전히 런던과 맨체스터에 집중되어 있으며, 이 지역에서는 인건비와 물류비가 이미 프로젝트 예산을 압박하고 있습니다.
VOC 규제의 강화가 하이브리드 실란 말단 폴리머로의 전환을 촉진하고 있습니다.
SI 2012/1715에서는 건축용 실란트의 VOC 함량을 5-10 g/L로 제한하고 있으며, 2024년 이후 강화된 현장 검사를 통해 시공사에게도 규제 준수의 중요성이 부각되고 있습니다. 하이브리드 SMP 등급은 배출량이 극히 적으면서도 이 제한을 충족하고, 주변의 습기에 의해 경화되며, 이소시아네이트 표시 의무를 피할 수 있기 때문에 많은 기본 계약에서 기본 선택지로 자리 잡고 있습니다. 유럽은 전 세계 SMP 생산 능력의 44%를 차지하고 있으며, 영국은 이 지역에서 SMP를 가장 빠르게 도입하고 있는 국가입니다. 이는 공공 부문 조달 담당자가 입찰 서류에 환경제품선언서(EPD) 제출을 의무화하고 있기 때문입니다. Wacker Chemie 및 KCC Corporation과 같은 공급업체들은 영국의 기술 팀을 확충하고, 시공업체를 대상으로 습기에 민감한 취급 방법에 관한 교육을 실시했습니다. 이러한 전환으로 인해 용제형 폴리우레탄에 비해 리터당 비용이 15-25% 상승하지만, 시공업체 입장에서는 향후 도입될 수명 주기 탄소 규제에 대응할 수 있게 되어, 기존 용제형 시스템의 폐지를 가속화할 가능성이 있습니다.
금속 실리콘 및 MDI 원료 가격 변동
금속 실리콘은 중국공급 과잉으로 인해 2026년 3월 기준 전년 대비 14.98% 하락했으나, 유럽의 MDI는 2026년 2월에 7.9% 상승했고, 아닐린은 2024년 4분기에 18% 상승했습니다. 그 때문에 주택 건설업체들이 가격 전가를 전면적으로 수용하는 데 저항하고 있어, 폴리우레탄 제조업체들은 이익률 압박에 직면해 있습니다. 원자재 가격 동향이 엇갈리고 있는 가운데, 고급 용도 시장에서는 실리콘으로 시장 점유율 전환이 진행되고 있는 반면, 폴리우레탄 공급업체들은 직업적 노출 위험을 높이는 TDI 혼합물의 시범 도입을 추진하고 있습니다. 홍해를 통과하는 해상 운송의 차질로 인해 리드타임이 10-14일 연장되면서, 판매업체들은 운전자금을 묶어두는 과다한 재고를 안고 있을 수밖에 없는 상황입니다.
부문별 분석
2025년 수요 중 실리콘 등급이 33.50%를 차지했으며, 그 주된 원인은 의료 분야 및 내화 사양 파사드에서 EN 15651 인증을 획득한 용도 때문입니다. 하이브리드 실란 개질 폴리머(SMP) 시장은 예측 기간(2026-2031년) 동안 연평균 성장률(CAGR) 7.12%를 나타낼 것으로 전망되며, 이는 모든 수지 중 가장 높은 성장률입니다. 이러한 성장세는 더욱 엄격해지는 VOC 규제를 준수하면서도 1액형으로 라벨 표시가 필요 없는 시스템을 시공업체들이 선호하는 경향과 일치합니다. 폴리우레탄은 내화학성과 이종 기재에 대한 접착성 덕분에, 전기자동차용 배터리 팩이나 산업용 바닥재 분야에서 여전히 중요한 위치를 차지하고 있습니다. 아크릴 및 폴리설파이드가 실내 마감 공사나 침수 지역의 토목 공사에서 계속해서 사용되고 있습니다. ISO 11600 및 ASTM C920에 관한 규제의 조화로 인해 성능 기준이 상향 조정되었으며, 이로 인해 실리콘, SMP, 폴리우레탄에 대한 연구개발비용이 증가하는 반면, 틈새 화학물질 분야는 정체되어 있습니다.
이러한 경쟁상의 영향은 이미 드러나고 있습니다. Wacker Chemie는 2025년에 영국 내 기술 지원을 확대했으며, Sika는 철도 차량용 ‘Sikaflex-268 PowerCure’를 도입하여 SMP의 빠른 경화 특성을 활용해 폴리설파이드의 대체재를 목표로 하고 있습니다. 현재 폴리설파이드에 주력하고 있는 중소규모의 배합 제조업체들은 여전히 침지 내구성이 중요시되는 선박 및 조수 관련 용도로만 제품 공급을 제한하고 있습니다. 건축 규제 당국의 EPD(환경 제품 선언) 요구가 높아지는 가운데, 생애주기 평가 비용을 감당하지 못하는 공급업체들은 사양서에 등재될 기회를 잃고 있으며, 이로 인해 수직 통합형 실리콘 및 SMP 제조업체들의 주도적 입지가 더욱 공고해지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the united kingdom sealants market size is projected to expand from USD 284.41 million in 2025 and USD 300.42 million in 2026 to USD 401.31 million by 2031, registering a CAGR of 5.96% between 2026 and 2031.
This report is Segmented by Resin Type (Acrylic, Epoxy, Polyurethane, Silicone, Polysulfide, Hybrid Silane-Modified Polymer (SMP), and Other Resins) and End-User Industry (Aerospace, Automotive, Building and Construction, Healthcare, and Other End-User Industries). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
United Kingdom Sealants Market Trends and Insights
Growing Demand for Fire-Resistant Sealants in UK High-Rise Refurbishments
The Building Safety Act is transforming fire-rated sealants from optional upgrades to compulsory products across roughly 12,500 high-rise dwellings in England. Intumescent acrylics and silicones must now achieve EN 13501-1 classification and prove compatibility with cavity-barrier systems, shifting procurement toward brands that can present third-party test evidence. Post-Grenfell inquiries traced smoke spread to joint failures, raising client scrutiny and lengthening approval cycles for unproven chemistries. Infrastructure upgrades in rail hubs and airports also require dual fire and acoustic ratings, which narrows the supplier pool and supports premium pricing. Smaller formulators lacking EN-certified lines are ceding share to multinational suppliers that can finance continuous testing, while demand remains concentrated in London and Manchester, where labor and logistics costs already elevate project budgets.
Stricter VOC Regulations Pushing Shift to Hybrid Silane-Terminated Polymers
SI 2012/1715 caps VOC content in construction sealants at 5-10 g/L, and intensified site inspections since 2024 have made compliance visible to contractors. Hybrid SMP grades meet the limit with negligible emissions, cure through ambient moisture, and avoid isocyanate labeling, which makes them the default choice in many framework contracts. Europe holds 44% of global SMP capacity, and the United Kingdom is the region's fastest adopter because public-sector buyers mandate Environmental Product Declarations in tender documents. Suppliers such as Wacker Chemie and KCC Corporation have expanded UK technical teams to train applicators on moisture-sensitive handling. The transition raises costs by 15-25% per liter compared with solvent-borne polyurethane but positions contractors for forthcoming lifecycle-carbon rules that could expedite the exit of legacy solvent systems.
Volatility in Silicon-Metal and MDI Raw-Material Prices
Silicon metal declined 14.98% year-on-year to March 2026 on Chinese oversupply, while European MDI rose 7.9% in February 2026, and aniline rose 18% in Q4 2024. Polyurethane producers, therefore, face margin compression because residential contractors resist full pass-through price increases. Divergent raw-material trends are shifting share toward silicone in premium applications, while polyurethane suppliers are experimenting with TDI blends that raise occupational-exposure risks. Freight disruptions through the Red Sea add 10-14 days to lead times, compelling distributors to carry higher inventories that tie up working capital.
Other drivers and restraints analyzed in the detailed report include:
- Post-Brexit Infrastructure Stimulus Accelerating Construction Sealant Consumption
- NHS Estate Maintenance Backlog Driving Healthcare-Facility Refurbishment
- Skilled Applicator Shortage Causing Project Delays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone grades accounted for 33.50% of 2025 demand, anchored by EN 15651-certified applications in healthcare and fire-rated facades. Hybrid Silane-Modified Polymer (SMP) products are forecast to grow at a CAGR of 7.12% annually during the forecast period (2026-2031), the fastest among all resins. That rise aligns with contractor preference for one-component, label-free systems that comply with tightening VOC caps. Polyurethane retains relevance in EV battery packs and industrial flooring because of its chemical resistance and adhesion to dissimilar substrates. Acrylic and polysulfide persist in interior decoration and immersion-zone civil works. Regulatory convergence around ISO 11600 and ASTM C920 is elevating performance thresholds, which is accelerating research and development spend on silicone, SMP, and polyurethane while niche chemistries stagnate.
The competitive effects are already visible. Wacker Chemie expanded UK technical support in 2025, and Sika AG introduced Sikaflex-268 PowerCure for rail carriages, aiming to displace polysulfide with faster SMP curing. Smaller formulators focusing on polysulfide now confine their offers to marine and tidal applications where immersion durability still commands a premium. As building-control officers increasingly request EPDs, suppliers that cannot finance lifecycle assessments are losing specification visibility, reinforcing the leadership of vertically integrated silicone and SMP producers.
List of Companies Covered in this Report:
- 3M
- Adshead Ratcliffe & Co Ltd.
- Arkema
- Bond It Group
- DAP Products
- Dow
- Sika Limited
- Fischer UK
- The Sherwin-Williams Company
- Gorilla Glue Company
- Henkel AG & Co. KGaA
- Hodgson Sealants
- illbruck (Tremco CPG)
- MAPEI S.p.A.
- RPM International Inc.
- Sika AG
- Soudal Group
- Tremco Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for fire-resistant sealants in UK high-rise refurbishments
- 4.2.2 Stricter VOC regulations pushing shift to hybrid silane-terminated polymers
- 4.2.3 Post-Brexit infrastructure stimulus accelerating construction sealant consumption
- 4.2.4 Rising electric-vehicle battery-pack sealing needs
- 4.2.5 NHS estate maintenance backlog driving healthcare-facility refurbishment
- 4.3 Market Restraints
- 4.3.1 Volatility in silicon-metal and MDI raw-material prices
- 4.3.2 Skilled applicator shortage causing project delays
- 4.3.3 Competition from prefabricated gasket solutions
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Epoxy
- 5.1.3 Polyurethane
- 5.1.4 Silicone
- 5.1.5 Polysulfide
- 5.1.6 Hybrid Silane-Modified Polymer (SMP)
- 5.1.7 Other Resins
- 5.2 By End-user Industry
- 5.2.1 Aerospace
- 5.2.2 Automotive
- 5.2.3 Building and Construction
- 5.2.3.1 Residential
- 5.2.3.2 Commercial
- 5.2.3.3 Infrastructure
- 5.2.4 Healthcare
- 5.2.5 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Adshead Ratcliffe & Co Ltd.
- 6.4.3 Arkema
- 6.4.4 Bond It Group
- 6.4.5 DAP Products
- 6.4.6 Dow
- 6.4.7 Sika Limited
- 6.4.8 Fischer UK
- 6.4.9 The Sherwin-Williams Company
- 6.4.10 Gorilla Glue Company
- 6.4.11 Henkel AG & Co. KGaA
- 6.4.12 Hodgson Sealants
- 6.4.13 illbruck (Tremco CPG)
- 6.4.14 MAPEI S.p.A.
- 6.4.15 RPM International Inc.
- 6.4.16 Sika AG
- 6.4.17 Soudal Group
- 6.4.18 Tremco Incorporated
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


