

|
시장보고서
상품코드
2066684
중국의 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 중국의 실란트 시장 규모는 2025년 33억 4,000만 달러로 평가되었습니다. 2026년에는 35억 5,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 6.61%로 성장을 지속하여, 2031년에는 48억 9,000만 달러에 이를 것으로 예측됩니다.
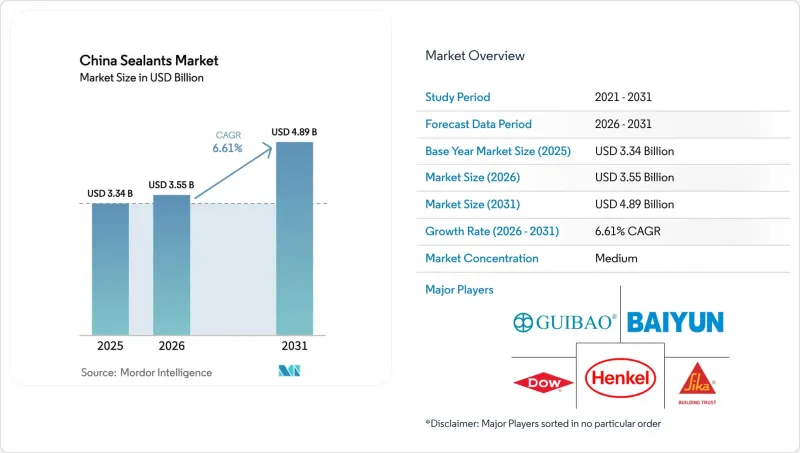
본 보고서는 수지 유형(아크릴, 에폭시, 폴리우레탄, 실리콘, 기타 수지) 및 최종 사용자 산업(항공우주, 자동차 및 운송, 일렉트로믹스 및 반도체, 건축 및 건설, 헬스케어, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
중국의 실란트 시장 동향 및 분석
그린빌딩 기준의 시행으로 고품질이면서 VOC 함량이 낮은 실란트에 대한 수요가 증가하고 있습니다.
2026년 6월에 시행될 의무적인 국가 표준 GB 30981.1-2025에 따라, 건축용 도료 및 부자재에 포함된 VOC, 반휘발성 화합물, 살생물제, 중금속에 대한 규제가 강화됨에 따라 제조업체들은 배합을 재검토할 수밖에 없는 상황에 놓여 있습니다. 이를 준수하지 않을 경우, 더 높은 환경보호세 부담을 지게 되거나 성급 감사를 받게 됩니다. 그룹 규격 T/CBMF 297-2024의 생애주기 평가(LCA) 요건에 따라 공공 부문 프로젝트의 조달 심사가 엄격해짐에 따라, 커튼월 및 조립식 건축물의 접합부에서 알코올 경화형 실리콘 및 수성 아크릴계 실란트의 채택이 촉진되고 있습니다. GB/T 35609-2025와 같은 보완적 프레임워크를 통해 환경 지표가 친환경 제품 라벨에 반영됨에 따라, 주택 리모델링 시장에서 기존의 옥심 경화형 실리콘이 주로 가격 경쟁을 펼치는 시장 양극화가 가속화되고 있습니다. 주요 도시에서는 이미 실시간 모니터링을 통한 VOC 배출량 디지털 보고가 의무화되어 있으며, 저배출 시범 생산 라인에 투자한 기업들은 선점 우위를 누리고 있습니다. 컴플라이언스 비용의 상승에 따라, 중국의 실란트 시장에서는 신속한 배합 변경과 ‘제조 시작부터 출하까지’의 추적성을 실현할 수 있는 수직 통합형 공급업체에 대한 평가가 높아지고 있습니다.
자동차 경량화가 다양한 소재의 접착으로의 전환을 촉진하고 있습니다.
중국의 전기자동차(EV) 부문에서는 엄격한 주행 거리 및 효율 목표를 달성하기 위해, 기계식 체결 부품에서 접착제를 많이 사용한 알루미늄 및 복합 소재 차체로 전환이 진행되고 있습니다. 자동차용 알루미늄 합금 차체 접합 공정 시장은 2024년에 약 860억 위안(120억 달러) 규모였으나, 알루미늄 차체의 보급률이 40%로 상승함에 따라 2030년까지 2,300억 위안(320억 달러)에 달할 것으로 예측됩니다. 구조용 폴리우레탄계 접착제는 상온 경화성과 진동 감쇠성이 뛰어나, 로봇화 된 생산 라인에서 타크트 타임 단축에 기여하고 있습니다. NIO ET7 등 주력 전기자동차 플랫폼에는 차량 1대당 120미터 이상의 충돌 내구성을 높인 구조용 접착제가 사용되고 있으며, 이는 1세대 모델에 비해 3배에 달하는 양입니다. 자동차 제조업체와 독자적인 접착 공식을 공동 개발하고 있는 국내 1차 공급업체는 설계 반복 횟수를 줄이고 지적 재산을 국내에 보유함으로써, 중국의 실란트 시장의 기술적 기반을 강화하고 있습니다.
실리콘 단량체 가격 변동이 이익률을 압박하고 있습니다.
모노머 생산자들이 30% 감산을 공동으로 실시한 결과, 2025년 11월에는 디메틸사이클로실록산(DMC)의 현물 가격이 20% 급등하여 톤당 1만 3,200위안(1,892.88달러)을 기록했습니다. 중국 남서부 지역의 수력 발전 공급 제한과 산업용 실리콘 가격 상승으로 인해, 2026년 1월까지 가격은 더욱 상승하여 톤당 1만 3,775위안(1,975.33달러)에 달했습니다. 장기 계약이나 금융 헤지를 보유하지 않은 중소 사료 제조업체의 경우, 매출총이익률이 최대 450 베이시스 포인트 감소했습니다. 와커(Wacker)와 같은 대형 통합 기업은 자사가 보유한 실록산 생산 능력을 활용하여 비용 급등의 충격을 완화하고, 중국의 실란트 시장에서 경쟁 우위를 확대했습니다.
부문별 분석
실리콘 제품은 커튼월용 유리, 파사드 패널, 태양광 발전 모듈 분야에서 입증된 내구성을 바탕으로 2025년 중국의 실란트 시장에서 41.55%의 점유율을 차지했습니다. 2031년까지 폴리우레탄 시장의 연평균 성장률(CAGR) 7.56%는 신에너지차(NEV)의 직접 글레이징 및 영하에서도 유연성이 요구되는 냉장용 단열 패널에 의해 주도되고 있습니다. 에폭시, 아크릴 및 MS 하이브리드 계열은 여전히 성장 중인 틈새 시장이지만, MS 하이브리드 계열은 이소시아네이트를 포함하지 않아 안전성이 뛰어나고 초기 강도가 빠르게 형성된다는 장점 덕분에 연간 80 베이시스 포인트 시장 점유율을 확대되고 있습니다.
D4 중간체의 가격이 급등하면 실리콘의 비용 측면에서의 불리함이 커지지만, 배합 기술, 중성 경화형 촉매, 접착 촉진제 및 UV 안정성 패키지를 통해 성능의 한계는 계속해서 높아지고 있습니다. Wacker사의 장가항 특수 실리콘 생산기지에서는 당초 독일에서 수입되던 고순도 유체를 공급하고 있으며, 전자기기용 밀봉 등급 제품의 리드타임을 단축하고 있습니다. 광저우 조인타스 등 국내 관련 기업들은 쇼어 A 경도를 20에서 50 범위 내에서 조절할 수 있으며, 아연 도금 강판에 프라이머 없이도 접착이 가능한 MS 하이브리드 제품을 적극 추진하고 있습니다. 이는 1교대당 수차례 기재를 교체하는 모듈식 건설 공장에서 매우 매력적인 제안입니다. 예측 기간 동안 중국의 실란트 시장은 단일 화학 성분이 지배적인 형태에서 벗어나 다양한 수지 포트폴리오로 전환될 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.29According to Mordor Intelligence, the china sealants market size is expected to grow from USD 3.34 billion in 2025 to USD 3.55 billion in 2026 and is forecast to reach USD 4.89 billion by 2031 at 6.61% CAGR over 2026-2031.
This report is Segmented by Resin Type (Acrylic, Epoxy, Polyurethane, Silicone, and Other Resins) and End-User Industry (Aerospace, Automotive and Transportation, Electronics and Semiconductors, Building and Construction, Healthcare, and Other End-User Industries). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
China Sealants Market Trends and Insights
Green-Building Code Enforcement Accelerates Premium, Low-VOC Sealant Demand
Mandatory national standard GB 30981.1-2025, effective June 2026, tightens limits on VOCs, semi-volatile compounds, biocides, and heavy metals in architectural coatings and accessory materials, forcing producers to reformulate or face higher environmental-protection taxes and provincial audits. Life-cycle assessment requirements in group standard T/CBMF 297-2024 heighten procurement scrutiny for public-sector projects, propelling alcohol-cure silicones and water-based acrylics in curtain-wall and prefabricated-building joints. Complementary frameworks such as GB/T 35609-2025 embed environmental metrics into green-product labeling, accelerating market bifurcation where legacy oxime-cure silicones compete mainly on price in residential retrofit channels. Tier-1 cities are already mandating digital VOC-emission reporting via real-time monitoring, giving an early-mover advantage to companies that invested in low-emission pilot lines. As compliance costs rise, the China Sealants market increasingly rewards vertically integrated suppliers capable of rapid formulation pivots and cradle-to-gate traceability.
Automotive Light-Weighting Drives Multi-Substrate Bonding Shift
China's electric-vehicle segment is migrating from mechanical fasteners to adhesive-intensive aluminum and mixed-material bodies to meet stringent range and efficiency targets. The automotive aluminum-alloy body connection-process market was roughly RMB 86 billion (USD 12 billion) in 2024 and is expected to climb to RMB 230 billion (USD 32 billion) by 2030 as aluminum-body penetration rises toward 40%. Structural polyurethane adhesives are favored for ambient-temperature cure and vibration damping, supporting higher takt times on robotized lines. Flagship EV platforms such as the NIO ET7 feature more than 120 meters of crash-toughened structural adhesive per vehicle, a threefold increase from first-generation models. Domestic Tier-1s co-developing proprietary bonding recipes with automakers shorten design iterations and retain intellectual property in-country, strengthening the technology spine of the China Sealants market.
Volatile Silicone Monomer Pricing Squeezes Margins
Spot prices for dimethyl-cyclosiloxane (DMC) jumped 20% in November 2025 to RMB 13,200 (USD 1,892.88) per ton after monomer producers coordinated 30% output cuts. Hydropower curtailments in Southwest China and higher industrial-silicon costs pushed quotes further to RMB 13,775 (USD 1,975.33) per ton by January 2026. Smaller formulators, lacking long-term contracts or financial hedges, saw gross margins compress by up to 450 basis points. Large integrated players such as Wacker leveraged captive siloxane capacity to buffer cost spikes, widening competitive gaps within the China Sealants market.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Warehousing Boom Raises Floor-Joint and Cold-Storage Sealant Use
- Rapid Expansion of China's Commercial Aerospace MRO Ecosystem
- Intensifying Provincial Environmental Audits on Solvent Emissions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone products commanded 41.55% of the China Sealants market share in 2025, supported by proven durability in curtain-wall glazing, facade panels, and photovoltaic modules. Polyurethane's 7.56% forecast CAGR through 2031 is propelled by direct-glazing in new-energy vehicles and by cold-storage insulation panels that demand flexibility at sub-zero temperatures. Epoxy, acrylic, and MS-hybrid chemistries remain growth niches, yet MS-hybrids are adding 80 basis points of share per year thanks to isocyanate-free safety and faster green strength.
Silicone's cost disadvantage widens when D4 intermediates surge, but formulation science, neutral-cure catalysts, adhesion promoters, and UV-stability packages continue to raise performance ceilings. Wacker's Zhangjiagang specialty silicones hub supplies high-purity fluids initially imported from Germany, shortening lead times for electronics encapsulation grades. Domestic challengers, such as Guangzhou Jointas, are promoting MS-hybrids with Shore-A hardness tunable from 20 to 50 and primer-less adhesion to galvanized steel, a compelling proposal in modular-construction factories that switch substrates several times per shift. Over the forecast window, the China sealants market will tilt toward diversified resin portfolios rather than single-chemistry dominance.
List of Companies Covered in this Report:
- 3M
- ACC Silicones (Shenzhen)
- Anabond Limited
- Arkema
- Beijing Oriental Yuhong Waterproof Technology
- Bondchem
- Chengdu Guibao Science and Technology Co., Ltd.
- CHT Germany GmbH
- Dow
- Guangzhou Baiyun Technology Co, Ltd.
- Guangzhou Jointas Chemical Co.
- H.B. Fuller Company
- Hangzhou Zhijiang Advanced Material Co.
- Henkel AG & Co. KGaA
- Huitian Adhesive Co.
- Momentive Performance Materials
- Shin-Etsu Chemical Co.
- Sika AG
- Tonsan Adhesive
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Green-building code enforcement accelerates premium, low-VOC sealant demand
- 4.2.2 Automotive light-weighting drives multi-substrate bonding shift
- 4.2.3 E-commerce warehousing boom raises floor-joint and cold-storage sealant use
- 4.2.4 Rapid expansion of China's commercial aerospace MRO ecosystem
- 4.2.5 Smart-factory adoption spurs demand for one-component UV-curable sealants
- 4.3 Market Restraints
- 4.3.1 Volatile silicone monomer pricing squeezes margins
- 4.3.2 Intensifying provincial environmental audits on solvent emissions
- 4.3.3 Over-capacity in low-grade construction silicones
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Resin Type
- 5.1.1 Acrylic
- 5.1.2 Epoxy
- 5.1.3 Polyurethane
- 5.1.4 Silicone
- 5.1.5 Other Resins
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Automotive and Transportation
- 5.2.3 Aerospace
- 5.2.4 Electronics and Semiconductors
- 5.2.5 Healthcare
- 5.2.6 Other End-user Industries
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 ACC Silicones (Shenzhen)
- 6.4.3 Anabond Limited
- 6.4.4 Arkema
- 6.4.5 Beijing Oriental Yuhong Waterproof Technology
- 6.4.6 Bondchem
- 6.4.7 Chengdu Guibao Science and Technology Co., Ltd.
- 6.4.8 CHT Germany GmbH
- 6.4.9 Dow
- 6.4.10 Guangzhou Baiyun Technology Co, Ltd.
- 6.4.11 Guangzhou Jointas Chemical Co.
- 6.4.12 H.B. Fuller Company
- 6.4.13 Hangzhou Zhijiang Advanced Material Co.
- 6.4.14 Henkel AG & Co. KGaA
- 6.4.15 Huitian Adhesive Co.
- 6.4.16 Momentive Performance Materials
- 6.4.17 Shin-Etsu Chemical Co.
- 6.4.18 Sika AG
- 6.4.19 Tonsan Adhesive
- 6.4.20 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


