

|
시장보고서
상품코드
2072959
미국의 병원 시설 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Hospital Facilities - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
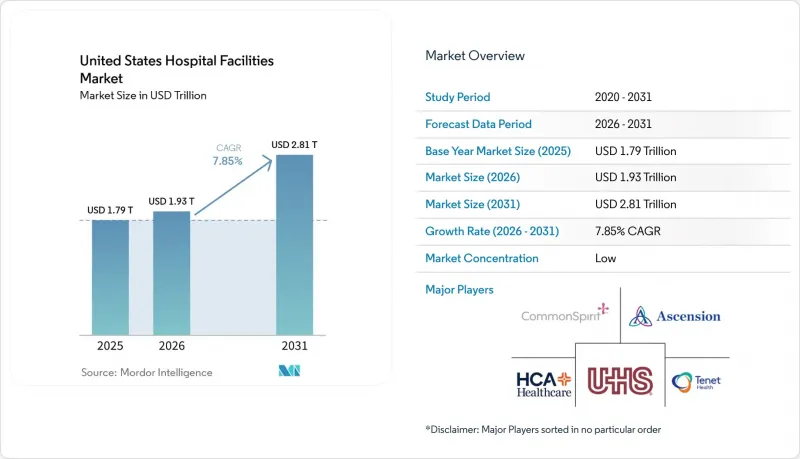
에 의하면, 미국 병원 시설 시장 규모는 2025년에 1조 7,900억 달러로 평가되었고 2026년 1조 9,300억 달러에서 2031년까지 2조 8,100억 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.85%를 나타낼 전망입니다.
본 보고서는 환자 서비스(입원, 외래), 시설 유형(공공·지역, 민간, 주립·연방), 서비스 유형(급성기 의료, 심혈관, 암 치료, 병리·진단·영상진단, 산부인과, 응급·외상, 기타), 병상 수(100병상 미만, 100-199병상, 200-299병상, 300병상 이상)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
미국 병원 시설 시장 동향과 인사이트
외래 진료로의 전환과 당일 수술 비율 증가
미국의 병원 시설 시장은 수술 건수가 입원 시설에서 외래 시설로 꾸준히 이동함에 따라 그 양상이 변화하고 있습니다. 2025년 12월에 발표된 조사에 따르면, 현재 미국에서 시행되는 수술의 65% 이상이 외래 시설에서 이루어지고 있으며, 팬데믹 이후 고관절 및 무릎 관절 치환술의 입원 비율이 감소한 것으로 확인되었습니다. 이는 이러한 전환 추세가 역전되지 않고 정착되고 있음을 보여줍니다. CMS(미국 의료보험·의료보조 서비스 센터)는 2026년에 OPPS(외래환자 지급 제도)의 총 지급액을 2025년 대비 80억 달러 증가한 1,010억 달러로 인상하는 한편, 주로 근골격계 수술 285건을 '입원 전용 목록'에서 삭제하기 시작하면서 이러한 추세를 부추겼습니다. 이는 입원 치료에서 수술로 전환된 사례 중 상당수가 역사적으로 병원 시스템에 있어 수익성이 높은 사례였기 때문에 중요한 의미를 지닙니다. 이러한 조치로 인해 주요 병원 캠퍼스 밖으로 이전하게 될 경우, 운영자는 의뢰 환자 유입과 의료진 간의 협력을 유지하기 위해 외래 진료부 및 외래수술센터(ASC)가 필요합니다. 2025년에는 메디케어 인증 외래수술센터(ASC)가 12,294곳에 달했으며, 이 부문은 전체 외래 수술 건수의 45%를 차지했습니다. 이는 미국의 병원 시설 시장이 단순히 성장하고 있을 뿐만 아니라, 수익을 창출하는 분야도 변화하고 있음을 보여줍니다.
병원 시스템 통합, 의뢰 환자 확보 및 네트워크 밀도
미국의 병원 시설 시장에서는 병원, 클리닉, 외래 진료 시설, 수술센터에 걸쳐 있는 환자 유입 경로를 관리할 수 있는 시스템이 계속해서 우위를 점하고 있습니다. 시장을 선도하는 기업들은 단순한 병상 수보다 지역 내 시설 밀도와 의사와의 협력을 더 중요하게 여기고 있기 때문에 통합의 배경이 되는 논리는 치료의 연속성 관리로 전환되고 있습니다. HCA 헬스케어는 2025년에 100여 개의 외래 진료 사업 부문을 추가하고, 전년 대비 17.8% 증가한 68억 달러의 순이익을 기록함으로써 이러한 접근 방식의 효과를 입증했습니다. 동시에, 2026년 및 2027년의 향후 확장을 위해 추가 자본이 확보되어 있음을 시사하고 있습니다. 동시에 규제 당국의 감독도 강화되고 있습니다. 2026년 6월, 연방거래위원회(FTC)는 어센션(Ascension)에 대해 암서지(AmSurg) 인수를 완료하기 위해 7곳의 외래수술센터(ASC)를 매각할 것을 명령했습니다. 이는 네트워크가 인수를 통해 외래 진료 규모를 확대할 수 있는 속도에 명확한 제한을 두는 것입니다. 또한 법무부는 2026년, 의료비를 상승시키고 있다고 지적된 계약상 제한 조항을 둘러싸고 뉴욕 장로교 병원을 상대로 소송을 제기했습니다. 이는 미국의 병원 시설 시장이 현재 합병뿐만 아니라 보험사와의 계약 체결 과정에서도 독점금지법상의 압박에 직면해 있음을 보여줍니다. 그 결과, 대규모 거래에 의존하지 않고 외래 환자 집적도를 높이며, 의뢰 환자를 유치할 수 있는 의료 시스템이 보다 지속 가능한 입지를 유지할 수 있을 것으로 보입니다.
임상 및 시설 운영 분야의 인력 부족
인력 부족은 미국 병원 시설 시장에서 여전히 가장 뿌리 깊은 구조적 제약 요인으로 남아 있습니다. 미국 의과대학 협회(AAMC)는 2036년까지 1만 3,500명에서 8만 6,000명에 달하는 의사 부족이 발생할 것으로 예측하고 있으며, NIHCM 역시 35개 전문의 분야 중 31개 분야에서 공급 부족이 예상된다고 지적하고 있습니다. 이는 수용 능력 확대가 앞으로도 임상 인력의 부족이라는 장벽에 계속 직면할 것임을 시사합니다. 간호직의 부담도 커지고 있으며, 전미병원협회(AHA)에 따르면 미국상공회의소는 2030년까지 42개 주에서 간호사 부족에 직면할 것으로 예측했습니다. 지난 4년 동안 구인 광고에 게재된 정규 간호사의 급여는 인플레이션율을 26.6% 상회하는 속도로 상승해 왔으며, 이는 미국 병원 시설 시장에서 매출 증가가 반드시 이익률 개선으로 이어지는 것은 아니라는 것을 의미합니다. 면허 비용은 이미 병원 총 비용의 56%를 차지하고 있으며, 재향군인 보건국(VHA)은 2025 회계연도에 심각한 직종별 인력 부족이 전년 대비 50% 증가했다고 보고했는데, 이는 운영상의 부담이 지속되고 있음을 시사합니다. 이로 인해 시설 확장에 실질적인 한계가 생깁니다. 왜냐하면 병상 인가나 건물 개설은 가능할지라도, 인력 배치 기준을 충족하지 못하면 임상 업무량을 감당할 수 없기 때문입니다.
부문별 분석
2025년 기준으로 환자 서비스 부문에서 외래 진료 서비스 시장 점유율은 54.31%를 차지하고 있으며, 이 부문의 미국 병원 시설 시장 규모는 2031년까지 연평균 성장률(CAGR) 8.38%로 확대될 것으로 전망됩니다. 이러한 조합을 통해 외래 진료가 이미 최대의 수익원이 되었으며, 그 격차를 계속해서 더 벌리고 있음을 알 수 있습니다. 이러한 변화는 구조적인 것입니다. 왜냐하면, 팬데믹 이후에도 치료 방식의 전환 추세는 계속되고 있으며, 이전과 같은 입원 중심의 패턴으로 되돌아가지 않았기 때문입니다. 현재 수술의 65% 이상이 외래 환경에서 이루어지고 있으며, 이는 병원 시스템 입장에서 외래 네트워크 및 병원 외래 부서에 투자해야 할 강력한 이유가 되고 있습니다. 따라서 미국의 병원 시설 시장에서는 단순한 수요 감소라기보다는 시스템 내에서의 서비스 전환이 나타나고 있으며, 특히 의료 제공업체가 외래 진료 거점을 소유하고 있는 경우 그 경향이 두드러집니다.
2025년에는 병원이 소유한 외래 시설에서 외래 수술의 45%가 시행되었습니다. 이는 통합형 의료 시스템이 자산을 적절히 관리한다면, 여전히 수술 수익의 상당 부분을 유지할 수 있음을 보여줍니다. 또한, CMS는 2026년도 서비스에 대해 OPPS 지급률을 2.6% 인상했습니다. 이는 독립형 센터와 경쟁 관계에 있는 병원 내·외래 진료 부서에 있어 어느 정도 도움이 될 것입니다. 2025년에도 입원 서비스는 여전히 환자 서비스 수익의 45.69%를 차지하고 있으며, 중환자 치료, 복잡한 수술, 중증 만성 질환의 관리는 당일 진료 체계로 쉽게 전환할 수 없기 때문에 이 기반은 여전히 중요합니다. 미국 병원 시설 시장에서 변화하고 있는 것은 입원 환자 구성입니다. 나머지 환자들의 증세가 점점 더 악화되고 있어, 더 많은 의료 자원이 필요해지고 있기 때문입니다. 이에 따라 병원은 두 가지 우선순위를 동시에 충족시켜야 합니다. 즉, 중증 입원 환자의 수용 능력을 확보하는 동시에, 의뢰 체계를 유지할 수 있을 정도의 속도로 외래 진료 접근성을 확대하는 것입니다.
2025년, 공립 및 지역 병원은 수익의 53.24%를 차지하며, 미국 병원 시설 시장에서 가장 큰 시설 유형으로 자리매김하고 있습니다. 이러한 우위는 도시, 교외, 농촌의 각 지역 사회에서 이들 병원이 의료 접근성 확보에 있어 수행하는 폭넓은 역할을 반영하고 있습니다. 이 병원들은 주로 수익성만을 기준으로 선택할 수 없는 방대한 양의 응급 의료, 무상 의료 및 의학적으로 필요한 의료 서비스를 담당하고 있습니다. 이러한 역할 덕분에, 이익률이 낮고 자본 예산이 부족한 상황에서도 미국 병원 시설 업계에서 확고한 입지를 다지고 있습니다. 민간 병원은 시장 점유율은 작지만, 대부분의 경우 자본 효율이 높은 운영 모델을 채택하고 있으며, 선택적 수술이나 민간 보험이 적용되는 수술의 비율이 높은 경향이 있습니다.
주립 및 연방 병원은 2031년까지 연평균 성장률(CAGR)이 8.52%로, 가장 빠르게 성장하고 있는 시설 유형입니다. 이러한 급속한 확장은 많은 독립 사업자들이 대규모 프로젝트에 대해 신중한 태도를 유지하고 있음에도 불구하고, 공공 부문의 수용 능력에 대한 투자가 활발하게 이어지고 있음을 보여줍니다. 미국의 병원 시설 업계에서는 공공·민간 소유 형태를 불문하고 여전히 동일한 인증 및 면허 기준이 요구되고 있습니다. 즉, 소유주가 바뀌더라도 규정 준수상의 부담이 줄어드는 것은 아닙니다. 공공 조달 주기에서는 지출이 장기간에 걸쳐 분산되는 경우가 많으며, 이는 예측 기간 전체에 걸쳐 보다 안정적인 건설 패턴을 뒷받침하고 있습니다. 그 결과, 미국의 병원 시설 시장에서는 지역 병원이 수익 기반을 유지하는 한편, 공공 지원을 통한 수용 능력 확충 분야에서 더 높은 성장률을 보이고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.07.03According to Mordor Intelligence, the united states hospital facilities market size was valued at USD 1.79 trillion in 2025 and is estimated to grow from USD 1.93 trillion in 2026 to reach USD 2.81 trillion by 2031, at a CAGR of 7.85% during the forecast period (2026-2031).
This report is Segmented by Patient Service (Inpatient, Outpatient), Facility Type (Public & Community, Private, State-Owned & Federal), Service Type (Acute Care, Cardiovascular, Cancer Care, Pathology/Diagnostics/Imaging, Obstetrics and Gynecology, Emergency & Trauma, Others), Bed Size (<100, 100-199, 200-299, 300+ Beds). The Market Forecasts are Provided in Terms of Value (USD).
United States Hospital Facilities Market Trends and Insights
Rising Outpatient Shift and Same-Day Surgery Mix
The United States hospital facilities market is being reshaped by a steady migration of surgical volume from inpatient campuses to outpatient settings. Research published in December 2025 confirmed that more than 65% of surgeries in the United States now occur in outpatient settings, and inpatient shares for hip and knee replacements fell after the pandemic, which shows that the shift has stayed in place rather than reversing. CMS reinforced this direction in 2026 by lifting total OPPS payments to USD 101.0 billion, up by USD 8.0 billion from 2025, while also starting the removal of 285 mainly musculoskeletal procedures from the Inpatient Only List. This matters because many of the procedures moving out of inpatient care were historically among the more profitable cases for hospital systems. When those procedures leave the main hospital campus, operators need outpatient departments and ambulatory surgery centers to keep referral flows and physician alignment intact. Medicare-certified ambulatory surgery centers reached 12,294 in 2025, and the sector captured 45% of total outpatient surgical volume, which shows that the United States hospital facilities market is not just growing, it is also changing where revenue is earned.
Hospital System Consolidation, Referral Capture, and Network Density
The United States hospital facilities market continues to favor systems that can control referral pathways across hospitals, clinics, outpatient sites, and surgery centers. The logic behind consolidation has shifted toward care-continuum control, because market leaders need local density and physician connectivity more than simple bed count. HCA Healthcare showed that approach in 2025 by adding nearly 100 outpatient business units and reporting net income of USD 6.8 billion, up 17.8% year over year, while also signaling that more capital remains available for future expansion in 2026 and 2027. Regulatory scrutiny is rising at the same time, as the FTC required Ascension to divest 7 ambulatory surgery centers in June 2026 to complete the AmSurg acquisition, which sets a clear limit on how fast networks can build outpatient scale through deals. The Department of Justice also sued NewYork-Presbyterian in 2026 over contract restrictions that it said raised healthcare costs, which shows that the United States hospital facilities market now faces antitrust pressure not only on mergers but also on payer contracting behavior. As a result, systems that can expand outpatient density and referral capture without relying on large transactions are likely to hold the more durable position.
Labor Shortages in Clinical and Facility Operations
Labor scarcity remains the most persistent structural restraint on the United States hospital facilities market. The Association of American Medical Colleges projected a physician shortage of 13,500 to 86,000 by 2036, and NIHCM noted that 31 of 35 physician specialties are expected to face supply gaps, which indicates that capacity expansion will continue to run into clinical staffing limits. Nursing pressure is also rising, and the AHA said the United States Chamber of Commerce expects 42 states to face nursing shortages by 2030. Advertised registered nurse salaries grew 26.6% faster than inflation over the last 4 years, which means revenue growth does not automatically translate into healthier margins for the United States hospital facilities market. Labor already represented 56% of total hospital costs, and the Veterans Health Administration reported a 50% year over year increase in severe occupational staffing shortages in FY2025, which points to continuing operational strain. This creates a practical limit for facility growth because beds can be licensed and buildings can be opened, but they cannot support clinical volume unless staffing standards are met.
Other drivers and restraints analyzed in the detailed report include:
- Technology-Enabled Bed and Throughput Optimization
- Aging Population and Chronic Disease Burden
- High Capital Intensity and Slow Payback for Facility Expansion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Outpatient Services held 54.31% of the United States hospital facilities market share within the patient service segmentation in 2025, and the United States hospital facilities market size for this segment is projected to grow at a CAGR of 8.38% through 2031. That combination shows that outpatient care is already the larger revenue pool and is still widening its lead. The shift is structural because procedure migration has remained in place after the pandemic rather than reverting to earlier inpatient patterns. More than 65% of surgeries now take place in outpatient settings, which gives hospital systems a strong reason to invest in ambulatory networks and hospital-based outpatient departments. The United States hospital facilities market is therefore seeing service migration within the system rather than simple demand loss, especially when providers own the outpatient site of care.
Hospital-owned outpatient facilities performed 45% of outpatient surgeries in 2025, which shows that integrated systems can still retain a meaningful part of procedural revenue if they control the right assets. CMS also increased OPPS payment rates by 2.6% for 2026 services, which offers some support to hospital-based outpatient departments as they compete with freestanding centers. Inpatient Services still accounted for 45.69% of patient service revenue in 2025, and that base remains important because intensive care, complex surgery, and high-acuity chronic disease management cannot move easily into same-day settings. What changes in the United States hospital facilities market is the inpatient mix, because the remaining cases are increasingly more severe and more resource intensive. This leaves hospitals balancing two priorities at once, protecting high-acuity inpatient capacity while expanding outpatient access fast enough to hold referral relationships.
Public and Community Hospitals commanded 53.24% of revenue in 2025, which makes them the largest facility type in the United States hospital facilities market. Their lead reflects the broad access role they play across urban, suburban, and rural communities. These hospitals absorb large volumes of emergency care, uncompensated care, and medically necessary services that cannot be selected mainly on profit profile. That role gives them a durable place in the United States hospital facilities industry, even when margins are tight and capital budgets are under pressure. Private Hospitals operate a smaller share of the base, but they often run more capital-efficient models and capture a stronger mix of elective and commercially insured procedures.
State-Owned and Federal Hospitals are the fastest-growing facility type, with a CAGR of 8.52% through 2031. This faster expansion signals that public capacity investment is staying active even as many independent operators remain cautious on large projects. The United States hospital facilities industry still requires the same accreditation and licensing standards across public and private ownership models, which means compliance burdens do not fall simply because the owner changes. Public procurement cycles often stretch spending over longer periods, which supports a steadier buildout pattern across the forecast window. As a result, the United States hospital facilities market keeps its revenue base in community hospitals while a faster growth rate develops in publicly backed capacity additions.
Complete Report Scope:
- By Patient Service
- Inpatient Services
- Outpatient Services
- By Facility Type
- Public and Community Hospitals
- Private Hospitals
- State-Owned and Federal Hospitals
- By Service Type
- Acute Care
- Cardiovascular
- Cancer Care
- Pathology Lab, Diagnostics, and Imaging
- Obstetrics and Gynecology
- Emergency and Trauma Care
- Other Service Types
- By Bed Size
- Less Than 100 Beds
- 100 to 199 Beds
- 200 to 299 Beds
- 300 Beds and Above
List of Companies Covered in this Report:
- Advocate Health
- Ascension Health
- Banner Health
- Baptist Health
- Baylor Scott and White Health
- Bon Secours Mercy Health
- Cedars-Sinai
- Cleveland Clinic
- CommonSpirit Health
- HCA Healthcare, Inc.
- Houston Methodist
- Intermountain Health
- Kaiser Permanente
- Mass General Brigham
- Mayo Clinic
- NewYork-Presbyterian Hospital
- Northwell Health
- Northwestern Medicine
- OhioHealth
- Orlando Health
- Providence St. Joseph Health
- Sutter Health
- Tenet Healthcare
- Trinity Health
- UCSF Health
- Universal Health Services
- University of Pennsylvania Health System
- UPMC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Outpatient Shift and Same-Day Surgery Mix
- 4.2.2 Hospital System Consolidation, Referral Capture, and Network Density
- 4.2.3 Technology-Enabled Bed and Throughput Optimization
- 4.2.4 Aging Population and Chronic Disease Burden
- 4.2.5 Cyber Resilience and Continuity Spending for Connected Care
- 4.2.6 Private-Room Conversion and Infection-Control Retrofits
- 4.3 Market Restraints
- 4.3.1 Hospital-Acquired Infection Risk and Sterile Workflow Constraints
- 4.3.2 Labor Shortages in Clinical and Facility Operations
- 4.3.3 High Capital Intensity and Slow Payback for Facility Expansion
- 4.3.4 Antitrust Scrutiny on Cross-Market Consolidation
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Patient Service
- 5.1.1 Inpatient Services
- 5.1.2 Outpatient Services
- 5.2 By Facility Type
- 5.2.1 Public and Community Hospitals
- 5.2.2 Private Hospitals
- 5.2.3 State-Owned and Federal Hospitals
- 5.3 By Service Type
- 5.3.1 Acute Care
- 5.3.2 Cardiovascular
- 5.3.3 Cancer Care
- 5.3.4 Pathology Lab, Diagnostics, and Imaging
- 5.3.5 Obstetrics and Gynecology
- 5.3.6 Emergency and Trauma Care
- 5.3.7 Other Service Types
- 5.4 By Bed Size
- 5.4.1 Less Than 100 Beds
- 5.4.2 100 to 199 Beds
- 5.4.3 200 to 299 Beds
- 5.4.4 300 Beds and Above
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Advocate Health
- 6.3.2 Ascension Health
- 6.3.3 Banner Health
- 6.3.4 Baptist Health
- 6.3.5 Baylor Scott and White Health
- 6.3.6 Bon Secours Mercy Health
- 6.3.7 Cedars-Sinai
- 6.3.8 Cleveland Clinic
- 6.3.9 CommonSpirit Health
- 6.3.10 HCA Healthcare, Inc.
- 6.3.11 Houston Methodist
- 6.3.12 Intermountain Health
- 6.3.13 Kaiser Permanente
- 6.3.14 Mass General Brigham
- 6.3.15 Mayo Clinic
- 6.3.16 NewYork-Presbyterian Hospital
- 6.3.17 Northwell Health
- 6.3.18 Northwestern Medicine
- 6.3.19 OhioHealth
- 6.3.20 Orlando Health
- 6.3.21 Providence St. Joseph Health
- 6.3.22 Sutter Health
- 6.3.23 Tenet Healthcare Corporation
- 6.3.24 Trinity Health
- 6.3.25 UCSF Health
- 6.3.26 Universal Health Services, Inc.
- 6.3.27 University of Pennsylvania Health System
- 6.3.28 UPMC
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


