

|
시장보고서
상품코드
2073041
명상 관리 앱 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Meditation Management Apps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 명상 관리 앱 시장 규모는 2025년 57억 2,000만 달러에서 2026년에는 66억 5,000만 달러로 확대되어 2031년까지 141억 7,000만 달러에 이를 것으로 예상되고 있어 2026-2031년까지 CAGR 16.32%로 성장할 전망입니다.
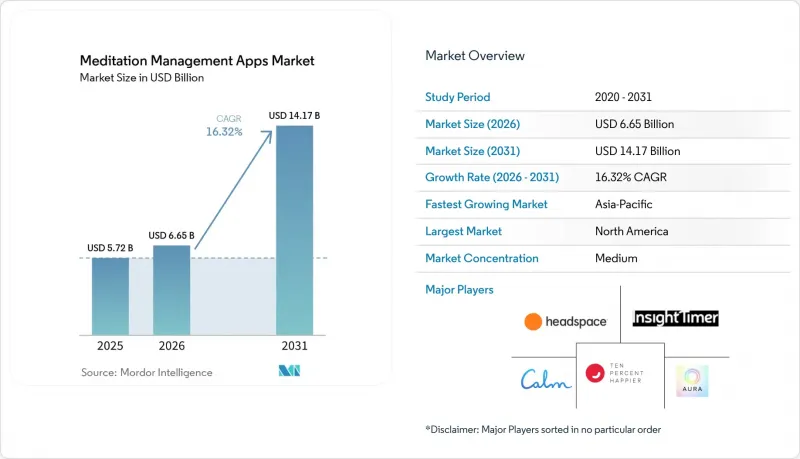
본 보고서는 플랫폼(iOS, Android, 웹 기반), 수익 모델(프리미엄, 구독, 일회성 구매, 광고 수익형, 기업용 라이선싱), 사용자 유형(개인 소비자, 기업, 의료 제공업체, 교육 기관), 컨텐츠 형태(가이드 명상, 비가이드 명상, 수면용 오디오, 호흡법), 지역(5개 지역)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 명상 관리 앱 시장 동향 및 인사이트
직장 내 번아웃 증가와 고용주의 웰니스 관련 지출 확대
고용주 수요는 명상 앱 시장의 주요 성장 요인입니다. 2026년 1월부터 Headspace는 Cigna Healthcare와 제휴하여, 고용주의 복리후생 제도를 통해 사용자에게 직접적인 비용 부담 없이 700만 명 이상에게 자기 주도형 정신 건강 지원 서비스를 제공합니다. 마찬가지로, Calm Health는 Solera Network에 합류하여 1,600만 명 이상의 이용자층을 확보하는 동시에, 건강보험 플랜, 의료 서비스 제공업체, 고용주를 합쳐 총 3,900만 명에 달하는 조직으로의 영향력을 확대했습니다. 이러한 유통 모델을 통해 수익원이 개인 구매에서 복리후생 인프라로 전환됨에 따라, 안정적인 계약 주기를 확보하고 신규 고객 확보에 대한 부담을 줄일 수 있게 되어, 예측 기간 동안 기업 주도의 성장을 뒷받침하고 있습니다.
AI를 활용한 개인 맞춤화 및 적응형 명상 프로그램
AI는 명상 앱 시장에서 핵심적인 참여 유도 도구로 자리매김하고 있습니다. Headspace는 2025년 5월, 공감형 AI 동반자 ‘ Ebb”를 도입하여 코칭, 치료, 자기 관리에 이르기까지 맞춤형 지침을 제공합니다. Insight Timer는 2026년 1월, 사용자에게 맞춤형 학습 과정을 구성하기 위한 AI 기반 추천 엔진을 출시했습니다. 한국의 NP는 명상 앱 ‘ MUA XR”에서 AI를 활용한 감정 추론을 통해 심박 변동이나 수면의 질과 같은 실시간 생체 신호를 통합했습니다. 정적 컨텐츠에서 적응형 시스템으로의 이러한 전환은 사용자 참여도를 높이고, 차별화된 플랫폼에 경쟁 우위를 가져다줍니다.
구독 피로감과 장기적인 유지율 저하
특히 일반 소비자용 플랫폼에서 지속적인 이용과 관련된 과제는 명상 앱 시장의 발전을 계속해서 저해하고 있습니다. 2025년 조사에 따르면, 디지털 정신건강 중재 프로그램의 완료율은 젊은 층 사용자들 사이에서 29.4%로 극히 낮은 수준에 머물러 있으며, 그 주된 원인은 습관 형성이 미흡하고 치료 경로와의 통합이 불충분하기 때문입니다. 이로 인해 사용자의 장기적인 가치가 하락하고, 마케팅 효율성에 대한 부담이 커지고 있습니다. 주요 기업들은 등록자 수가 보다 안정적인 기업, 보험사, 의료 제공업체의 채널을 점점 더 주요 대상으로 삼고 있습니다. 지속적인 참여도를 개선하지 못한다면, 시장은 신규 사용자 확보뿐만 아니라 이탈한 사용자를 보충하는 데 크게 의존하게 될 것으로 보입니다.
부문별 분석
2025년, iOS는 플랫폼 부문에서 46.76%의 점유율을 차지하며 명상 앱 시장에서 가장 큰 수익원으로서의 입지를 유지했습니다. 이러한 우위는 유료 구독 및 웰니스 관련 지출이 정착된 북미와 서유럽의 프리미엄 사용자들에 의해 주도되었습니다. iOS 사용자들은 프리미엄 서비스나 가이드가 포함된 프로그램에 대해 더 적극적으로 결제를 하는 경향이 있으며, 시장이 새로운 계층으로 확대됨에 따라 이 플랫폼은 수익 창출의 핵심적인 역할을 계속해서 수행하고 있습니다.
안드로이드는 2026년부터 2031년까지 연평균 성장률(CAGR) 16.90%를 기록하며 성장할 것으로 예상되며, 명상 앱 시장에서 가장 빠르게 성장하는 플랫폼이 될 전망입니다. 이러한 성장은 안드로이드가 주류를 차지하는 남아시아, 동남아시아, 라틴아메리카, 사하라 이남 아프리카의 스마트폰 보급에 힘입은 것입니다. 현지 언어로 된 라이브러리, 지역 특유의 주제, 문화적으로 친화도가 높은 강사를 제공하는 플랫폼이 더 나은 성과를 거둘 것으로 예측됩니다. 또한, IT 프로토콜과의 호환성 덕분에 기업 간에는 웹 기반 액세스도 주목을 받고 있습니다. 멀티플랫폼 설계는 사용자 경험을 향상시키고 체계적인 프로그램을 지원하기 위해 필수적인 요소로 자리 잡고 있습니다.
2025년, 프리미엄 모델은 명상 앱 시장의 45.30%를 차지하며, 도달 범위와 유통 측면에서 주요 수익 모델이 되었습니다. 이 모델은 진입 장벽을 낮추는 동시에, 프리미엄 요금제로의 전환, 제품 출시, 그리고 기업 인지도 제고의 기회를 창출합니다. 이 모델은 기존 사용자층과 신규 사용자층 모두에서 수요를 확대하는 데 필수적입니다.
구독 서비스는 2031년까지 연평균 성장률(CAGR) 17.25%를 나타낼 것으로 예측되며, 가장 빠르게 성장하는 수익 모델로 부상하고 있습니다. 이러한 성장은 기업 및 건강보험 플랜과의 계약을 통해 주도되고 있으며, 이 계약에서는 임의 갱신 대신 정기적인 결제가 이루어지고 있습니다. 개인정보 보호를 중시하는 사용자들은 평생 이용권보다 유연한 월정액 구독 서비스를 선호하기 때문에 의식이 높은 시장에서는 적응력이 핵심이 됩니다. 일회성 구매나 광고 수익 모델은 가격에 민감한 지역에서는 여전히 유효하지만, 구독과 같은 지속적인 수익 창출 가능성은 부족합니다.
지역별 분석
2025년, 북미는 명상 앱 시장의 42.45%를 차지하며 최대 지역 시장으로서의 위상을 유지했습니다. 이 지역은 성숙한 고용주들이 운영하는 웰니스 제도, 의료 보험 플랜과의 긴밀한 연계, 벤처 자본을 통한 대규모 제품 개발의 혜택을 누리고 있습니다. 2026년 1월까지 Headspace는 Cigna Healthcare와 제휴하여, 고용주와 연계된 복리후생 프로그램을 통해 700만 명 이상의 사용자에게 서비스를 제공했습니다. Calm Health는 Solera Network를 통해 사업 범위를 확대하여 1,600만 명의 이용자에게 서비스를 제공함과 동시에, 대상 가입자 수를 3,900만 명으로 늘렸습니다. FDA 승인을 받은 디지털 정신건강 솔루션에 대한 CMS(미국 의료보험 및 의료서비스 센터)의 보상 채널은 임상적으로 차별화된 플랫폼에 대해 의료 제공업체가 이를 도입할 수 있는 보다 명확한 경로를 제시함으로써 해당 지역 시장을 더욱 강화하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 16.76%를 기록하며 성장할 것으로 예상되며, 명상 앱 시장에서 가장 빠르게 성장하는 지역이 될 전망입니다. 이러한 성장은 디지털 웰니스의 보급, 스마트폰 사용 확대, 일상생활에서 앱 기반 마음챙김에 대한 수용 확대에 힘입어 이루어지고 있습니다. Insight Timer는 2026년 3월 인도에서 서비스를 시작하여, 전 세계 2만 명 이상의 강사가 제공하는 30만 건의 무료 안내 명상 컨텐츠를 선보였습니다. 이는 수요가 높은 시장을 개척하기 위해 풍부한 무료 라이브러리를 활용하고 있음을 보여줍니다. 한국은 생체 신호와 연동된 명상 체험 및 AI를 활용한 맞춤형 명상 체험 분야에서 주요 혁신 허브로서의 입지를 굳건히 유지하며, 제품 개발과 사용자 수 증가를 모두 뒷받침하고 있습니다.
유럽은 확고히 자리 잡은 웰니스 수요와 지역에 뿌리를 둔 플랫폼에 힘입어, 명상 앱 시장에서 두 번째로 큰 규모를 자랑하는 지역 클러스터가 되었습니다. 해당 지역에서는 개인정보 보호, 동의, 과학적 근거에 기반한 실천이 중시되기 때문에 규정을 준수하고 충분한 문서화가 이루어진 플랫폼이 선호됩니다. 유럽과 북미 이외의 지역에서는 프리미엄 모델의 도입, 모바일 통신 환경의 개선, 기업 주도의 도입이 점진적으로 확대되는 것을 배경으로, 남미, 중동 및 아프리카에서 명상 앱 시장이 성장하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.07.07According to Mordor Intelligence, the meditation management apps market size is expected to increase from USD 5.72 billion in 2025 to USD 6.65 billion in 2026 and reach USD 14.17 billion by 2031, growing at a CAGR of 16.32% over 2026-2031.
This report is Segmented by Platform (iOS, Android, Web-Based), Revenue Model (Freemium, Subscription, One-Time Purchase, Ad-Supported, Enterprise Licensing), User Type (Individual Consumers, Enterprises, Healthcare Providers, Education Institutions), Content Format (Guided Meditation, Unguided Meditation, Sleep Audio, Breathwork), and Geography (5 Regions). Market Forecasts are in Terms of Value (USD).
Global Meditation Management Apps Market Trends and Insights
Rising Workplace Burnout and Employer Wellness Spending
Employer demand is a key growth driver for the meditation apps market. Starting January 2026, Headspace partnered with Cigna Healthcare to provide self-guided mental health support to over 7 million individuals through employer benefits at no direct cost to users. Similarly, Calm Health joined the Solera Network, expanding access to over 16 million people and increasing its institutional reach to 39 million across health plans, providers, and employers. This distribution model shifts revenue generation from individual purchases to benefits infrastructure, ensuring stable contract cycles and reduced acquisition pressures, supporting enterprise-driven growth during the forecast period.
AI-Driven Personalization and Adaptive Meditation Journeys
AI is becoming a central engagement tool in the meditation apps market. Headspace introduced its Ebb empathetic AI companion in May 2025, offering personalized guidance across coaching, therapy, and self-care. Insight Timer launched an AI-powered recommendation engine in January 2026 to create tailored lesson paths for users. South Korea's NP utilized AI emotion inference in its MUA XR meditation app, integrating real-time biosignals like heart rate variability and sleep quality. This shift from static content to adaptive systems enhances user engagement and creates a competitive edge for differentiated platforms.
Subscription Fatigue and Weak Long-Term Retention
Retention challenges continue to hinder the meditation apps market, particularly for consumer-first platforms. A 2025 study found that digital mental health interventions have completion rates as low as 29.4% among younger users, primarily due to weak habit formation and poor integration into care pathways. This reduces the long-term value of users and pressures marketing efficiency. Leading companies are increasingly targeting enterprise, payer, and provider channels, where enrollment is more stable. Without improving sustained engagement, the market will rely heavily on replacing churned users alongside acquiring new ones.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Clinical Adjacent Use Cases in Sleep and Anxiety
- Platform Bundling Through Super Apps and Wellness Ecosystems
- Privacy Concerns Around Sensitive Mental Health Data
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, iOS held a 46.76% share of the platform segment, maintaining its position as the top revenue generator in the meditation apps market. This dominance was driven by premium users in North America and Western Europe, where paid subscriptions and wellness spending are well-established. iOS users are more inclined to pay for premium experiences and guided programs, keeping the platform central to monetization as the market expands to new demographics.
Android is projected to grow at a 16.90% CAGR from 2026 to 2031, making it the fastest-growing platform in the meditation apps market. This growth is fueled by smartphone adoption in South and Southeast Asia, Latin America, and Sub-Saharan Africa, where Android dominates. Platforms offering local language libraries, region-specific themes, and culturally relevant instructors are expected to perform better. Web-based access is also gaining traction among enterprises due to compatibility with IT protocols. Multi-platform designs are becoming essential as they enhance user experience and support structured programs.
Freemium accounted for 45.30% of the meditation apps market in 2025, making it the leading revenue model by reach and distribution. It lowers entry barriers while creating opportunities for premium conversions, referrals, and enterprise visibility. This model is crucial for scaling demand across both mature and emerging user bases.
Subscription is forecast to grow at a 17.25% CAGR through 2031, emerging as the fastest-growing revenue model. Growth is driven by enterprise and health plan contracts, where recurring payments replace discretionary renewals. Privacy-conscious users prefer flexible monthly subscriptions over lifetime access, making adaptability key in high-awareness markets. One-time purchases and ad-supported models remain relevant in price-sensitive regions but lack the recurring revenue potential of subscriptions.
Complete Report Scope:
- By Platform
- iOS
- Android
- Web-Based
- By Revenue Model
- Freemium
- Subscription
- One-Time Purchase
- Ad-Supported
- Enterprise Licensing
- By User Type
- Individual Consumers
- Enterprises
- Healthcare Providers
- Education Institutions
- By Content Format
- Guided Meditation
- Unguided Meditation
- Sleep and Relaxation Audio
- Breathwork and Mindfulness Exercises
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
In 2025, North America accounted for 42.45% of the meditation apps market, maintaining its position as the largest regional player. The region benefits from mature employer wellness systems, strong health plan integration, and significant venture-backed product development. By January 2026, Headspace partnered with Cigna Healthcare to provide services to over 7 million users through employer-linked benefits. Calm Health expanded its reach via the Solera Network, adding access to 16 million individuals and increasing its institutional footprint to 39 million covered lives. The CMS reimbursement pathway for FDA-approved digital mental health solutions further strengthens the region by offering clinically differentiated platforms a clearer route to provider adoption.
Asia-Pacific is projected to grow at a 16.76% CAGR through 2031, making it the fastest-growing region in the meditation apps market. Growth is driven by digital wellness adoption, wider smartphone access, and increasing acceptance of app-based mindfulness in daily routines. Insight Timer launched in India in March 2026 with 300,000 free guided meditations from over 20,000 global instructors, showcasing the use of extensive free libraries to tap into high-demand markets. South Korea remains a key innovation hub for biosignal-linked and AI-personalized meditation experiences, supporting both product development and user growth.
Europe ranked as the second-largest regional cluster in the meditation apps market, supported by established wellness demand and localized platforms. The region's focus on privacy, consent, and evidence-backed practices favors compliant and well-documented platforms. Outside Europe and North America, the meditation apps market is expanding in South America, the Middle East, and Africa, driven by freemium access, improved mobile connectivity, and gradual employer-led adoption.
- Aura Health Inc.
- BetterMe Limited
- Breethe
- Buddhify Limited
- Calm.com, Inc.
- FitMind LLC
- Headspace
- Healthy Minds Innovations, Inc.
- Insight Network, Inc.
- Meditopia Meditasyon ve Teknoloji A.?.
- MindApps Oy
- Mindbody, Inc.
- Petit BamBou
- Sanvello Health
- Simple Habit, Inc.
- Smiling Mind
- Ten Percent Happier, Inc.
- The Mindfulness App
- Unplug Meditation, LLC
- Waking Up, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Workplace Burnout and Employer Wellness Spend
- 4.2.2 Consumer Shift Toward Low-Cost, Self-Guided Mental Wellness
- 4.2.3 AI-Driven Personalization and Adaptive Meditation Journeys
- 4.2.4 Wearable and Biosensor Integration for Real-Time Stress Coaching
- 4.2.5 Expansion of Clinical Adjacent Use Cases in Sleep and Anxiety Support
- 4.2.6 Platform Bundling Through Super Apps and Wellness Ecosystems
- 4.3 Market Restraints
- 4.3.1 Subscription Fatigue and Weak Long-Term Retention
- 4.3.2 Privacy Concerns Around Sensitive Mental Health Data
- 4.3.3 Low Clinical Differentiation Among Mass-Market Apps
- 4.3.4 Algorithmic Content Drift and Quality Control Risks at Scale
- 4.4 Value Chain Analysis
- 4.5 Supply Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Platform
- 5.1.1 iOS
- 5.1.2 Android
- 5.1.3 Web-Based
- 5.2 By Revenue Model
- 5.2.1 Freemium
- 5.2.2 Subscription
- 5.2.3 One-Time Purchase
- 5.2.4 Ad-Supported
- 5.2.5 Enterprise Licensing
- 5.3 By User Type
- 5.3.1 Individual Consumers
- 5.3.2 Enterprises
- 5.3.3 Healthcare Providers
- 5.3.4 Education Institutions
- 5.4 By Content Format
- 5.4.1 Guided Meditation
- 5.4.2 Unguided Meditation
- 5.4.3 Sleep and Relaxation Audio
- 5.4.4 Breathwork and Mindfulness Exercises
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Aura Health Inc.
- 6.3.2 BetterMe Limited
- 6.3.3 Breethe
- 6.3.4 Buddhify Limited
- 6.3.5 Calm.com, Inc.
- 6.3.6 FitMind LLC
- 6.3.7 Headspace Inc.
- 6.3.8 Healthy Minds Innovations, Inc.
- 6.3.9 Insight Network, Inc.
- 6.3.10 Meditopia Meditasyon ve Teknoloji A.?.
- 6.3.11 MindApps Oy
- 6.3.12 Mindbody, Inc.
- 6.3.13 Petit BamBou
- 6.3.14 Sanvello Health, Inc.
- 6.3.15 Simple Habit, Inc.
- 6.3.16 Smiling Mind
- 6.3.17 Ten Percent Happier, Inc.
- 6.3.18 The Mindfulness App
- 6.3.19 Unplug Meditation, LLC
- 6.3.20 Waking Up, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


