

|
시장보고서
상품코드
2097221
천식용 스페이서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Asthma Spacers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 천식용 스페이서시장 규모는 2025년에 21억 1,000만 달러로 평가되었고, 2026년 22억 6,000만 달러에서 2031년까지 31억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.11%를 나타낼 전망입니다.
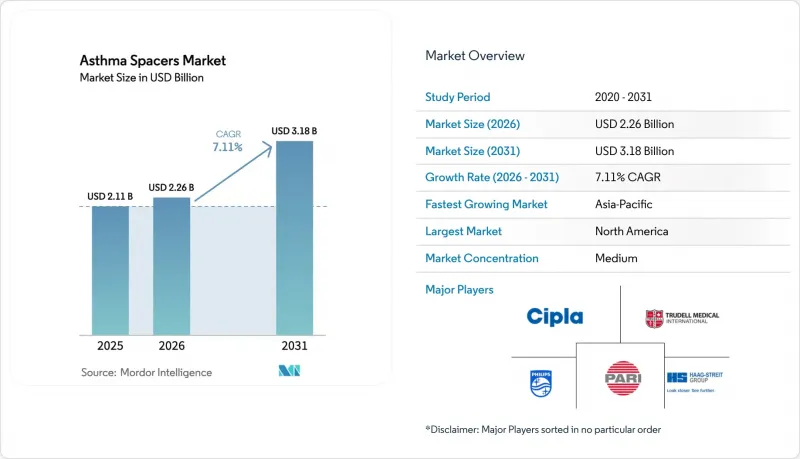
본 보고서는 제품 유형(에어로 챔버, 옵티 챔버 등), 소재(폴리카보네이트, 금속 등), 연령대(소아, 성인, 고령자), 유통 채널(병원 약국, 소매 약국 등), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 천식용 스페이서 시장 동향 및 인사이트
만성 호흡기 질환 유병률 증가
천식 환자 수는 2021년 2억 6,000만 명에서 2050년까지 2억 7,500만 명으로 증가할 것으로 예측되며, 이 질병 부담의 30% 가까이는 변경 가능한 요인에 기인합니다. 이러한 증가에 따라 의료 시스템이 흡입 요법의 효과를 높이기 위한 비용 효율적인 방법을 모색함에 따라, 스페이서에 대한 장기적인 수요가 유지되고 있습니다. 아시아태평양은 특히 큰 과제에 직면해 있으며, 9개국에서 천식이 적절하게 관리되고 있는 환자는 고작 7.6%에 불과해, 약물 복용 순응도를 지원하는 의료기기에는 큰 성장 여지가 있음을 시사합니다. 중국에서는 지난 30년 동안 유병률이 감소했으나, 인구 통계학적 변화로 인해 2046년까지 절대 환자 수는 450만 명에 달할 가능성이 있습니다. 전 세계적으로 보더라도 만성 호흡기 질환은 여전히 사망 원인 3위를 차지하고 있어, 흡입기 기술의 최적화가 필요함을 여실히 보여주고 있습니다.
스페이서를 이용한 흡입에 대한 인식 제고
임상 연구에 따르면, 야간 기관지 경련 발작 시 정전기 방지 챔버를 사용하면 기관지 확장제의 반응이 21-25% 향상된다고 보고되었습니다. 현재 교육 캠페인에서는 특히 소아를 대상으로 올바른 흡입법 지도에 중점을 두고 있으며, 이를 통해 오용이 감소하고 흡입 시간이 길어지고 있습니다. 전문가 지침에서는 가압식 정량 흡입기를 사용하는 모든 소아 및 고용량 코르티코스테로이드를 처방받은 환자에게 스페이서 사용을 권장하고 있습니다. 선진국 시장의 보험 환급 제도에서는 효과가 입증되고 비용 대비 효율이 높은 부속품이 점점 더 우선시되고 있으며, 가이드라인이 표준화된 구매 결정 요인이 되고 있습니다.
브랜드 정전기 방지 챔버의 높은 가격 책정
고급 정전기 방지 스페이서는 기본 모델보다 40-60% 비싸기 때문에 본인 부담 의료비가 주를 이루는 가격에 민감한 시장에서는 구매 장벽이 높습니다. 이러한 가격 차이로 인해 고급 제품은 선진국에 집중되어 있는 반면, 기타 지역에서는 기존 형태의 스페이서가 주류를 이루고 있습니다. 생산량이 증가하고 특허가 만료됨에 따라 제네릭 제품이 가격 차이를 좁혀 이러한 제약을 완화할 가능성이 있습니다.
부문 분석
2025년, 볼마틱(Volmatic)사의 기기는 매출의 33.10%를 차지하며, 의료진이 익숙한 제품이라는 점과 병원에서의 광범위한 채택을 통해 천식용 스페이서 시장의 기반을 다지고 있습니다. 옵티챔버의 연평균 성장률(CAGR) 7.88%는 특히 자가 투여의 정확성이 가장 중요한 외래 및 재택 환경에서 정전기 방지 성능이 중시되고 있음을 보여줍니다. 에어로챔버는 소아 분야에서 확고한 입지를 유지하고 있으며, 인스피리어스는 호흡 작동식 지원이 필요한 사용자를 타겟으로 하고 있습니다. 제품의 다양화로 인해 직접적인 가격 경쟁이 억제되고, 타겟을 좁힌 마케팅 전략이 촉진되고 있습니다.
2세대 스마트 스페이서는 음향 센서와 압력 센서를 통합하여 환자의 투여 기술을 검증하고, 치료 순응도에 관한 데이터를 확충하고 있습니다. 분석 기능을 소모품과 세트로 판매하는 제조업체는 초기 기기 판매를 넘어 지속적인 수익원 확보를 목표로 하고 있습니다. 병원에서는 기존 브랜드에 대한 충성도보다 실제 환경에서의 결과 증거를 중시하며, 기기 선정 과정을 약제 목록에 반영하는 경향이 강해지고 있습니다. 보험 급여 체계가 입증된 유효성을 평가하는 가운데, 임상적 유효성이 확인된 프리미엄 제품은 비용 제약이 있는 조달 환경에서도 높은 이익률을 확보하고 있습니다.
2025년 매출에서 폴리카보네이트가 차지하는 비중은 40.85%로 이는 비용 효율적인 제조, 투여량을 육안으로 확인할 수 있는 투명성, 그리고 허용 가능한 정전기 방지 코팅이 높이 평가된 결과입니다. 금속 스페이서는 시장 규모는 작지만, 병원 및 규제 당국이 환경 부하가 낮은 재사용 가능한 솔루션을 장려하고 있어 연평균 성장률(CAGR)은 8.01%로 성장을 지속하고, 있습니다. 친환경 조달 정책 하에서 수명 주기 가치 분석이 내구성이 높은 기기를 지지함에 따라, 금속 천식 스페이서 시장 규모는 확대될 것으로 예측됩니다.
복합재료 및 특수 플라스틱 분야의 혁신은 화학적 내성 향상과 인체공학적 편안함을 제공하며, 과도기적인 위치를 차지하고 있습니다. 각 공급업체는 재사용 가능한 제품의 감염 위험을 줄이기 위해 항균 처리 실험을 진행하고 있습니다. 유럽에서는 입찰 평가 시 지속가능성 지표가 점점 더 중요시되면서 소재 선정에 긍정적인 영향을 미치고 있습니다. 미국에서는 병원 그룹들이 교체 횟수 감소에 따른 장기적인 비용 절감과 금속 디자인의 높은 초기 도입 비용을 저울질하며 검토하고 있습니다.
지역별 분석
북미는 2025년 전 세계 매출의 40.80%를 차지했습니다. 이는 보험 적용 범위의 넓음, 의료 종사자들의 높은 인지도, 그리고 혁신 주기를 단축하는 FDA의 명확한 규제 절차에 힘입은 결과입니다. 2024년공급망 혼란으로 인해 흡입기의 취약성이 드러나면서, 기존 재고의 효용성을 극대화하는 절약 수단으로서 스페이서의 중요성이 높아졌습니다. 스마트 기기 도입률은 미국이 가장 높으며, 미국에서는 복약 순응도 분석 데이터가 원격 호흡기 관리 플랫폼에 직접 반영되어 보험 환급 전망이 개선되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 8.11%로 가장 빠르게 성장하는 지역입니다. 천식 유병률의 상승, 급속한 도시화, 의료 인프라의 개선이 수요를 견인하고 있습니다. 경제적 부담에 관한 조사에 따르면, 환자 1인당 비용은 108달러에서 1,010달러에 달하며, 제조업체가 대응해야 할 폭넓은 가격대가 부각되고 있습니다. 중국, 인도, 인도네시아 각국 정부는 인식 제고 캠페인을 전개하고 있어, 소아용 스페이서 프로그램에 유리한 기회가 창출되고 있습니다. 다만, 만성 질환이라는 낙인에 대한 문화적 저항은 여전히 존재하고 있어, 지역에 맞춘 교육 컨텐츠와 지역 사회 기반의 연수가 필요합니다.
유럽은 안정적이면서도 역동적으로 규제가 진행되고 있는 환경에 있습니다. EU에서 도입이 예정된 재활용 가능한 포장에 관한 규제는 재사용 가능한 스페이서를 뒷받침하고, 일회용 플라스틱 부품에 압박을 가하고 있습니다. 유럽의약품청(EMA)의 2024년 지침은 부수적인 의약품 성분을 포함하는 의료기기의 승인 절차를 간소화하여 차세대 스페이서 시장 진입을 가속화하고 있습니다. 여러 회원국에서 발생한 살부타몰의 일시적인 공급 부족은 효율적인 약물 전달의 중요성을 재확인시켜 주었으며, 공급 충격 시에도 스페이서 수요를 유지하는 결과로 이어졌습니다.
남미 및 중동 및 아프리카에서는 보험 급여 제도의 미비나 의료진의 낮은 인지도로 인해 보급 속도가 완만한 수준에 그치고 있습니다. 브라질과 사우디아라비아에서 진행된 시범 프로젝트에서는 대상자를 선별한 교육을 통해 흡입 기술이 향상되고 응급실 방문이 감소하는 것이 입증되었으며, 지불 제도가 성숙해짐에 따라 시장 침투가 서서히 진행될 것으로 예측됩니다. 기부금으로 운영되는 보건 프로그램에서는 제한된 의약품 예산을 효율적으로 활용하기 위해 흡입용 코르티코스테로이드와 스페이서를 세트로 제공하는 사례가 늘어나고 있으며, 이를 통해 기기의 효능을 극대화하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KTH 26.08.06According to Mordor Intelligence, the asthma spacers market size was valued at USD 2.11 billion in 2025 and estimated to grow from USD 2.26 billion in 2026 to reach USD 3.18 billion by 2031, at a CAGR of 7.11% during the forecast period (2026-2031).
This report is Segmented by Product Type (Aerochamber, Optichamber, and More), Material (Polycarbonate, Metal, and More), Age Group (Paediatric, Adult, and Geriatric), Distribution Channel (Hospital Pharmacy, Retail Pharmacy, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America). The Market and Forecasts are Provided in Terms of Value (USD).
Global Asthma Spacers Market Trends and Insights
Rising prevalence of chronic respiratory diseases
Asthma cases are projected to rise from 260 million in 2021 to 275 million by 2050, with modifiable factors responsible for nearly 30% of the disease burden The increase sustains long-term demand for spacers as healthcare systems seek cost-effective ways to enhance inhaled therapy outcomes. Asia-Pacific faces distinct pressure, with only 7.6% of patients achieving well-controlled asthma across nine countries, signaling substantial upside for devices that support adherence. Although China's incidence rate fell over three decades, demographic shifts imply absolute case numbers could reach 4.5 million by 2046 . Globally, chronic respiratory diseases remain the third leading cause of death, underscoring the need for optimized inhaler technology.
Growing awareness of spacer-assisted inhalation
Clinical studies report 21-25% better bronchodilator response when anti-static chambers are used during nocturnal bronchospasm episodes. Education campaigns now emphasize correct inhaler technique, particularly for children, leading to fewer errors and longer inhalation time. Professional guidelines recommend spacers for all children using pressurized metered-dose inhalers and for patients prescribed high-dose corticosteroids. Reimbursement frameworks in developed markets increasingly prefer proven, cost-effective accessories, turning guidelines into standardized purchase drivers.
Premium pricing of branded anti-static chambers
Advanced anti-static spacers cost 40-60% more than basic models, limiting affordability in price-sensitive markets where out-of-pocket health expenses dominate. The differential keeps high-end devices concentrated in developed economies, while conventional spacer formats prevail elsewhere. As manufacturing volumes rise and patents expire, generic competitors could narrow the price gap and reduce this constraint.
Other drivers and restraints analyzed in the detailed report include:
- Intensifying R&D in anti-static & smart spacers
- Eco-friendly inhaler initiatives favoring spacers
- Limited reimbursement & user awareness in LMICs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Volumatic devices generated 33.10% of revenue in 2025, anchoring the asthma spacers market through clinician familiarity and broad hospital adoption. Optichamber's 7.88% CAGR underscores preference for anti-static performance, particularly in outpatient and home settings where self-administered accuracy matters most. Aerochamber maintains strong pediatric positioning, while Inspirease targets users needing breath-actuated support. Product diversification limits direct price competition and encourages targeted marketing strategies.
Second-generation smart spacers integrate acoustic or pressure sensors to verify patient technique, expanding therapy adherence data. Manufacturers that bundle analytics with consumables aim to secure recurring revenue streams beyond initial device sales. Hospitals increasingly embed device selection into formularies, weighing real-world outcomes evidence over legacy brand loyalty. As reimbursement frameworks reward proven effectiveness, premium products with clinical validation capture higher margins despite cost-constrained procurement climates.
Polycarbonate accounted for 40.85% of 2025 revenue, reflecting cost-effective manufacturing, transparency for visual dose confirmation, and acceptable anti-static coatings. Metal spacers, though representing a smaller base, post an 8.01% CAGR as hospitals and regulators champion reusable solutions with lower environmental footprint. The asthma spacers market size for metal formats is forecast to widen as lifecycle value analyses favor durable devices within green procurement policies.
Innovations in composite and specialty plastics occupy a transitional space, offering enhanced chemical resistance or ergonomic comfort. Suppliers experiment with antimicrobial treatments to reduce infection risk in reusable units. European tenders increasingly score bids on sustainability metrics, driving material choices. In the United States, hospital groups weigh long-run cost savings from fewer replacements against higher upfront acquisition prices for metal designs.
Complete Report Scope:
- By Product Type
- Aerochamber
- Optichamber
- Volumatic
- Inspirease
- By Material
- Polycarbonate
- Metal
- Others
- By Age Group
- Paediatric
- Adult
- Geriatric
- By Distribution Channel
- Hospital Pharmacy
- Retail Pharmacy
- E-Commerce
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 40.80% of global sales in 2025, buoyed by widespread insurance coverage, strong clinician awareness, and the FDA's clear regulatory pathway that shortens innovation cycles. Supply chain disruptions in 2024 exposed inhaler vulnerabilities, elevating spacers as a conservation tool that maximizes existing inventory efficacy. Adoption of smart devices is highest in the United States, where adherence analytics feed directly into tele-respiratory platforms, enhancing reimbursement prospects.
Asia-Pacific is the fastest-growing territory with an 8.11% CAGR to 2031. Rising asthma prevalence, rapid urbanization, and improved medical infrastructure stimulate demand. Economic burden studies reveal per-patient costs spanning USD 108 to USD 1,010, highlighting a wide affordability range that manufacturers must navigate. Governments in China, India, and Indonesia launch awareness drives, creating fertile ground for pediatric spacer programs. Nonetheless, cultural resistance to chronic disease labeling persists, requiring localized educational content and community-based training.
Europe presents a stable yet dynamically regulated environment. The EU's incoming recyclable packaging mandate favors reusable spacers and pressures single-use plastic components. The European Medicines Agency's 2024 guidance streamlines approval for devices that contain ancillary medicinal substances, accelerating next-generation spacer entries. Temporary salbutamol shortages across several member states reaffirmed the importance of efficient drug delivery, thereby maintaining spacer demand through supply shocks.
South America and the Middle East & Africa register moderate adoption, constrained by reimbursement gaps and lower clinician familiarity. Pilot projects in Brazil and Saudi Arabia demonstrate that targeted training improves inhaler technique and lowers emergency visits, foreshadowing incremental penetration as payer systems mature. Donor-funded health programs increasingly bundle spacers with inhaled corticosteroids, leveraging device efficacy to stretch limited medicine budgets.
- Trudell Medical International
- Cipla
- PARI Pharma
- Koninklijke Philips
- GlaxoSmithKline
- Monaghan Medical
- Teleflex
- Rossmax
- Thayer Medical Corp.
- AstraZeneca
- Merck
- Koo Medical Equipment
- HAAG-Streit
- Laboratoire ProtecSom
- AGP-Med
- Visiomed Group
- Intersurgical Ltd.
- SunMed LLC
- Besmed Health Business
- Apex Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic respiratory diseases
- 4.2.2 Growing awareness of spacer?assisted inhalation
- 4.2.3 Intensifying R&D in anti-static & smart spacers
- 4.2.4 Eco-friendly inhaler initiatives favouring spacers
- 4.2.5 Tele-respiratory care & digital adherence tools
- 4.2.6 Home-based respiratory therapy expansion
- 4.3 Market Restraints
- 4.3.1 Premium pricing of branded anti-static chambers
- 4.3.2 Limited reimbursement & user awareness in LMICs
- 4.3.3 Sustainability regulations on single-use plastics
- 4.3.4 'For-children' perception curbing adult uptake
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porters Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Aerochamber
- 5.1.2 Optichamber
- 5.1.3 Volumatic
- 5.1.4 Inspirease
- 5.2 By Material
- 5.2.1 Polycarbonate
- 5.2.2 Metal
- 5.2.3 Others
- 5.3 By Age Group
- 5.3.1 Paediatric
- 5.3.2 Adult
- 5.3.3 Geriatric
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacy
- 5.4.2 Retail Pharmacy
- 5.4.3 E-Commerce
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Trudell Medical International
- 6.3.2 Cipla Inc.
- 6.3.3 PARI GmbH
- 6.3.4 Koninklijke Philips N.V.
- 6.3.5 GSK plc
- 6.3.6 Monaghan Medical Corporation
- 6.3.7 Teleflex Inc.
- 6.3.8 Rossmax International Ltd.
- 6.3.9 Thayer Medical Corp.
- 6.3.10 AstraZeneca plc
- 6.3.11 Merck & Co., Inc.
- 6.3.12 Koo Medical Equipment
- 6.3.13 HAAG-STREIT GROUP
- 6.3.14 Laboratoire ProtecSom
- 6.3.15 AGP-Med
- 6.3.16 Visiomed Group
- 6.3.17 Intersurgical Ltd.
- 6.3.18 SunMed LLC
- 6.3.19 Besmed Health Business Corp.
- 6.3.20 Apex Medical Corp.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


