|
시장보고서
상품코드
2099525
안경 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Eye Glasses - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
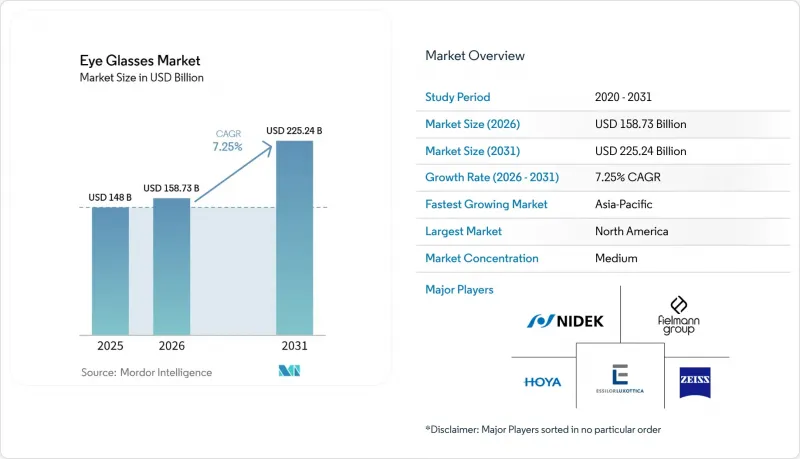
에 의하면, 안경 시장 규모는 2025년 1,480억 달러로 평가되었고, 2026년 1,587억 3,000만 달러에서 2031년까지 2,252억 4,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 7.25%를 나타낼 전망입니다.
본 보고서는 제품 유형별(도수 안경, 노안용 안경 등), 프레임 소재별(플라스틱, 금속, 아세테이트, 기타), 렌즈 유형별(단초점, 이중초점, 누진 다초점 등), 판매 채널별(안경점 등), 최종 사용자별(성인, 어린이, 고령자), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 안경 시장 동향 및 인사이트
근시, 노안 및 디지털 눈의 피로 증가
젊은 층과 고령층에서 시각적 부담이 증가함에 따라 안경 시장의 임상적 기반은 지속적으로 강화되고 있습니다. 2025년 『BMC Pediatrics』지에 게재된 연구에 따르면, 스마트폰을 사용하는 아동의 근시 유병률은 31.4%, TV나 컴퓨터 게임을 이용하는 아동의 경우 35.4%였습니다. 또한, 2025년에 발표된 또 다른 메타분석에서는 스마트 기기 화면 시청 시간이 근시 발병 위험을 26% 증가시키는 것과 관련이 있는 것으로 밝혀져, 디지털 습관과 처방 안경 수요 간의 연관성이 입증되었습니다. 국제 근시 연구소(International Myopia Institute)는 2025년 요약 보고서에서 화면 시청 시간 단축이나 야외 활동만으로는 안축장의 신장을 충분히 억제할 수 없습니다고 지적하며, 장기적인 관리 도구로서 특수 안경 렌즈의 유용성을 뒷받침하고 있습니다. 에실로-룩소티카(EssilorLuxottica)의 근시 관리 제품 포트폴리오는 2025년에 전 세계적으로 22% 성장할 것으로 예상되며, 이는 안경 시장에서 프리미엄 렌즈에 대한 수요가 증가하고 있음을 보여줍니다.
프리미엄화의 진전과 패션 주도형 안경테 교체 주기의 확대
안경 시장은 시력 교정의 범위를 넘어서는 추세이며, 구매 행동에는 스타일 선호도, 브랜드에 대한 친화성, 그리고 여러 쌍을 소유하고자 하는 의향이 점점 더 반영되고 있습니다. 사피로(Saphiro)는 2025년에 지역을 불문하고 처방용 안경테 수요가 견조했다고 보고한 반면, 스포츠, 컨템포러리, 라이프스타일용 안경테는 렌티(Lenti)의 연결 제외 영향을 제외하면 2.6%의 유기적 성장을 기록했습니다. 프리미엄화 추세에 따라, 특히 브랜드 안경테가 더 강력한 라이프스타일 가치를 지닌 북미와 유럽에서 교체 빈도와 평균 판매 가격이 상승하고 있습니다. 성숙 시장에서 처방용 안경테 구매자들은 안경테를 ‘착용하는 액세서리’로 인식하는 경향이 강해지고 있으며, 이는 동일 연도 내 두 번째, 세 번째 구매를 촉진하고 있습니다. 소비자들이 소재, 브랜드, 코팅, 디자인 기능 면에서 더 고급스러운 제품으로 교체 구매함에 따라, 이러한 경향은 판매 대수 증가세가 둔화되더라도 매출 안정화에 기여하고 있습니다.
콘택트렌즈나 굴절 교정 수술로의 대체 현상이 널리 관찰되고 있습니다.
안경 시장은 동일한 성인 환자층을 두고, 콘택트렌즈나 레이저를 이용한 시력 교정 수술과의 직접적인 경쟁에 계속해서 직면하고 있습니다. LASIK, SMILE 및 관련 수술 옵션은 지속적인 안경 사용보다 일회성 시술을 선호하는 생산연령층 소비자들 사이에서 안경테 수요를 억제할 가능성이 있습니다. 이러한 압박은 소득 수준이 높고 선택적 수술에 대한 접근성이 좋은 성숙 시장에서 일상적인 안경 착용에서 벗어나는 추세를 부추기고 있어 더욱 두드러지게 나타나고 있습니다. 그러나 수술이 모든 환자에게 적합한 것은 아니며, 지속적인 시력 지원이 필요한 모든 이용 사례를 다룰 수 있는 것도 아니기 때문에 이러한 억제요인이 안경 시장에 균일하게 영향을 미치는 것은 아닙니다. 근시 관리는 여전히 안경 치료에 크게 의존하고 있으며, 미성년자는 일반적으로 굴절 교정 수술의 적응증이 아니기 때문에 어린이들은 중요한 완충 역할을 하고 있습니다. 이러한 추세로 인해 조기 진단부터 성인기에 이르기까지 안경 시장에 대한 지속적인 처방 수요 파이프라인이 유지되고 있습니다.
부문 분석
도수 안경은 전 세계 굴절 이상 환자의 규모와 지속성을 반영하여, 2025년에는 58.94%의 점유율로 안경 시장을 주도한 것으로 평가되었습니다. 교정 목적의 사용은 의학적으로 필수적이기 때문에 이 부문은 계속해서 수익의 주축이 될 것이며, 처방전 갱신, 안경테의 마모, 그리고 변화하는 시각적 요구에 따라 재구매가 촉진되고 있습니다. 노안용 안경은 북미, 유럽, 동아시아의 고령화에 따른 노안 증가로 인해 계속해서 혜택을 보고 있습니다. 선글라스 및 안전·스포츠용 안경은 라이프스타일과 직업적 용도에서 수요가 확대되고 있으며, 처방 안경은 선글라스, 보호용, 고성능 안경테의 추가 구매를 뒷받침하고 있습니다.
스마트글라스는 2026-2031년 연평균 성장률(CAGR) 10.20%를 나타낼 것으로 예측되며, 안경 시장에서 가장 빠르게 성장하는 제품 카테고리가 될 전망입니다. 특히, 처방전 대응이 가능해짐에 따라 도입의 주요 장벽이 제거됨에 따라, 이 카테고리는 안경을 교정 제품에서 커넥티드 플랫폼으로 변모시키고 있습니다. 2026년 6월 299달러에 출시될 ‘Meta Glasses’는 도수 지원이 가능한 3가지 스타일을 선보이며, 틈새 기술이라는 위치에서 일상적인 활용을 향한 움직임을 보이고 있습니다. 에시롤-룩소티카가 2025년에 700만 대 이상의 AI 안경을 판매한 것은 스마트 아이웨어에 대한 수요가 지역을 불문하고 확대되고 있음을 보여주는 반면, 안전용 및 스포츠용 아이웨어는 직장이나 야외에서의 이용 사례를 통해 여전히 중요한 위치를 차지하고 있습니다.
플라스틱 프레임은 합리적인 가격, 폭넓은 디자인 옵션, 그리고 대형 할인점 및 중저가 소매점의 풍부한 상품 구색에 힘입어 2025년에는 안경 시장의 39.45%를 차지한 것으로 평가되었습니다. 아세테이트는 성숙한 시장에서 패션 지향적인 소비자들에게 계속해서 지지를 받고 있는 반면, 경량 플라스틱 소재는 가격에 민감한 소비자나 가족 단위 구매에서 인기를 유지하고 있습니다. 이 부문은 연령대, 도수, 디자인 선호도에 관계없이 폭넓은 수요가 있다는 강점을 가지고 있습니다. 플라스틱은 제조 효율성과 의료 용도부터 라이프스타일 요구까지 아우르는 폭넓은 제품 라인업 간의 균형이 잘 잡혀 있어 여전히 중요한 소재입니다.
티타늄은 2031년까지 연평균 성장률(CAGR) 9.67%로 확대될 것으로 예상되며, 안경 시장에서 가장 빠르게 성장하는 소재 부문이 될 전망입니다. 프리미엄 카테고리 구매자들이 경량성, 내구성, 내식성, 저알레르기성을 중시함에 따라 수요가 증가하고 있습니다. 또한, 티타늄은 판매 단가 상승을 촉진하여 프리미엄 안경 브랜드가 판매 수량에만 의존하지 않고 프레임당 수익을 향상시키는 데 기여하고 있습니다. 금속 프레임은 정밀한 피팅과 구조적 강성 측면에서 여전히 중요하지만, 구매 결정 시 지속가능성이 더욱 중시됨에 따라 프리미엄 컬렉션에서는 바이오 아세테이트가 주목받고 있습니다.
지역별 분석
북미는 2025년에 안경 시장의 41.30%를 차지한 것으로 평가되었으며, 금액 기준으로 최대 지역 시장이 될 전망입니다. 1인당 지출액이 높고, 확립된 보험 환급 제도, 그리고 프리미엄 렌즈, 코팅, 브랜드 프레임의 보급이 이 지역의 주도적 지위를 뒷받침하고 있습니다. 비전 카운슬(The Vision Council)의 예측에 따르면, 제품 판매량과 시력 검사 건수가 감소하는 상황 속에서도 미국 안경 업계는 2025년에 695억 달러에 달한 것으로 평가되었으며, 이는 가격 경쟁력의 강화와 제품 구성의 다양화를 시사합니다. 워비 파커는 2025년에 47개 매장, 2026년에 추가로 50개 매장을 신규 오픈할 계획이며, 이는 소매와 진료를 통합한 비즈니스 모델에 대한 지속적인 자신감을 반영하고 있습니다. 이러한 요인들로 인해 프리미엄 제품의 보급과 커넥티드 아이웨어의 조기 상용화 측면에서 북미가 수행하는 역할은 더욱 강화되고 있습니다.
유럽은 독립 안경점 네트워크, 뿌리 깊은 프리미엄 안경테 문화, 그리고 진행 중인 소매 업계 재편에 힘입어 안경 시장에서 여전히 2위 지역 블록으로서의 지위를 유지하고 있습니다. 필만(Feelman)사는 2025 회계연도에 사상 최고의 실적을 평가했으며, 2026 회계연도 매출은 25억 5,000만 유로에서 26억 유로 사이가 될 것으로 전망하고 있습니다. 이는 유럽 내 300개 매장에 AI 기반 자동 굴절 검사 시스템을 도입할 계획과 2026년 70개 매장의 신규 출점에 힘입은 결과입니다. 이탈리아는 주요 아이웨어 그룹을 위한 프리미엄 안경테 밸류체인의 상당 부분을 뒷받침하는 벨루노 제조 거점을 통해 계속해서 전략적으로 중요한 위치를 차지하고 있습니다. 또한, 2026년 6월로 예정된 Meta Glasses 출시에는 영국, 프랑스, 이탈리아, 독일, 스페인이 포함될 전망이므로, 유럽은 스마트 아이웨어 출시에서도 중요한 역할을 하고 있습니다. 이러한 요인들로 인해 이 지역은 안경 시장에서 프리미엄 디자인, 제조 품질 및 브랜드 가치 확보에 있어 중심적인 위치를 계속 차지하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 11.56%를 나타낼 것으로 예측되며, 안경 시장에서 가장 빠르게 성장하는 지역이 될 것입니다. 이 지역은 전 세계에서 근시 부담이 가장 규모가 큰 지역이며, 세계보건기구(WHO) 서태평양 지역 사무소는 근시가 ‘유행 수준’에 도달했다고 지적하고 있습니다. 중국과 싱가포르 청소년의 유병률은 50%에 가까우며, 동아시아 일부 지역에서는 청년층의 유병률이 최대 80%에 달할 전망입니다. 이러한 추세는 특히 학령기 및 청년층에서 다른 많은 지역보다 이른 시기에 장기적인 처방 주기에 진입하게 함으로써, 구조적으로 견고한 시력 교정 기반을 형성하고 있습니다. 인도는 체계적인 안경 소매업이 지속적으로 확대되고 있으며, 가처분 소득과 충족되지 않은 시력 교정 수요가 증가하고 있어 계속해서 중요한 성장 거점으로 자리 잡고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.11According to Mordor Intelligence, the eye glasses market size is projected to expand from USD 148 billion in 2025 and USD 158.73 billion in 2026 to USD 225.24 billion by 2031, registering a CAGR of 7.25% between 2026 to 2031.
This report is Segmented by Product Type (Prescription Eyeglasses, Reading Glasses, and More), Frame Material (Plastic, Metal, Acetate, Others), Lens Type (Single Vision, Bifocal, Progressive, and More), Distribution Channel (Optical Stores, and More), End User (Adults, Children, Seniors), and Geography (North America, Europe, Asia-Pacific, MEA, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Eye Glasses Market Trends and Insights
Rising Myopia, Presbyopia, and Digital Eye Strain Burden
The clinical base of the eyeglasses market continues to strengthen as visual strain increases across younger and older age groups. A 2025 study in BMC Pediatrics reported global myopia prevalence of 31.4% among children using smartphones and 35.4% among children using television and computer games. A separate 2025 meta-analysis found that smart device screen time was associated with a 26% increase in the odds of myopia, reinforcing the link between digital habits and prescription demand. The International Myopia Institute noted in its 2025 digest that screen-time reduction alone and outdoor activity alone do not adequately control axial elongation, supporting specialty spectacle lenses as a longer-term management tool. EssilorLuxottica's myopia management portfolio grew 22% worldwide in 2025, indicating stronger premium lens demand within the eyeglasses market.
Growth in Premiumization and Fashion-Led Frame Replacement Cycles
The eyeglasses market is moving beyond vision correction, as purchases increasingly reflect style preferences, brand affinity, and a willingness to own more than one pair. Safilo reported resilient prescription frame demand across geographies in 2025, while sport, contemporary, and lifestyle frames delivered 2.6% organic growth, excluding the Lenti deconsolidation effect. Premiumization increases replacement frequency and average selling price, particularly in North America and Europe, where branded frames carry stronger lifestyle value. Prescription buyers in mature markets increasingly treat frames as wearable accessories, supporting second-pair and third-pair purchases within the same year. This behavior helps stabilize revenue even when unit growth slows, as consumers trade up in materials, brand labels, coatings, and design features.
High Prevalence of Substitution From Contact Lenses and Refractive Surgery
The eyeglasses market continues to face direct competition from contact lenses and laser-based corrective procedures across the same adult patient base. LASIK, SMILE, and related surgical options can limit frame demand among working-age consumers who prefer a one-time intervention over continued spectacle use. This pressure remains more visible in mature markets, where higher income levels and better access to elective procedures support a shift away from routine spectacle wear. However, this restraint does not affect the eyeglasses market uniformly, as surgery does not suit every patient and cannot address all use cases requiring ongoing visual support. Children provide a meaningful buffer because myopia management still relies heavily on spectacle-based treatment, and minors generally do not qualify for refractive surgery. This trend maintains a durable prescription pipeline for the eyeglasses market, from early diagnosis into adulthood.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Omnichannel Optical Retail and Online Try-On
- Smart Eyewear Convergence With AR, Audio, and Health Functions
- Counterfeit and Grey-Market Frames Eroding Premium Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Prescription eyeglasses are expected to lead the eye glasses market with a 58.94% share in 2025, reflecting the scale and persistence of global refractive errors. The segment remains the revenue anchor as corrective use is medically necessary, while repeat purchases are driven by updated prescriptions, frame wear, and evolving visual needs. Reading glasses continue to benefit from rising presbyopia across aging populations in North America, Europe, and East Asia. Sunglasses and safety or sports eyewear add demand across lifestyle and occupational applications, while prescription wear supports follow-on purchases in sun, protective, and performance frames.
Smart glasses are projected to grow at a 10.20% compound annual growth rate (CAGR) from 2026 to 2031, making them the fastest-growing product category in the eye glasses market. The category is shifting eyewear from a corrective product to a connected platform, especially as prescription compatibility removes a key adoption barrier. The June 2026 Meta Glasses launch at USD 299 in three Rx-able styles signals a move toward everyday use rather than niche technology positioning. EssilorLuxottica's sale of more than 7 million AI-glass units in 2025 shows that smart eyewear demand is expanding across regions, while safety and sports eyewear remain relevant through workplace and outdoor use cases.
Plastic frames are expected to account for 39.45% of the eye glasses market in 2025, supported by affordability, broad styling options, and strong availability across mass and mid-tier retail formats. Acetate continues to appeal to fashion-focused consumers in mature markets, while lighter plastic formats remain popular in price-sensitive and family-oriented purchases. The segment benefits from flexibility across age groups, prescription strengths, and design preferences. Plastic remains important as it balances manufacturing efficiency with a wide product assortment across clinical and lifestyle needs.
Titanium is expected to expand at a 9.67% CAGR through 2031, making it the fastest-growing material segment in the eye glasses market. Demand is rising as premium-category buyers prioritize low weight, durability, corrosion resistance, and hypoallergenic properties. Titanium also supports higher realized prices, helping premium optical brands improve revenue per frame rather than relying only on unit turnover. Metal frames remain relevant for precise fitting and structural rigidity, while bio-acetate is gaining traction in premium collections as sustainability becomes more visible in purchase decisions.
Complete Report Scope:
- By Product Type
- Prescription Eyeglasses
- Reading Glasses
- Sunglasses
- Smart Glasses
- Safety and Sports Eyewear
- By Frame Material
- Plastic
- Metal
- Acetate
- Titanium
- Other Frame Materials
- By Lens Type
- Single Vision
- Bifocal
- Progressive
- Photochromic
- Polarized
- Others
- By Distribution Channel
- Optical Stores
- Retail Chains
- E-Commerce
- Hospitals and Eye Care Clinics
- Others
- By End User
- Adults
- Children
- Seniors
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America is expected to hold 41.30% of the eyeglasses market in 2025, making it the largest regional contributor by value. High per-capita spending, established reimbursement structures, and strong adoption of premium lenses, coatings, and branded frames support the region's leadership. The Vision Council projects that the US optical industry will reach USD 69.5 billion in 2025, even as product volumes and eye exams decline, indicating stronger pricing and a richer product mix. Warby Parker plans to add 47 stores in 2025 and 50 more in 2026, reflecting continued confidence in integrated retail and clinical models. These factors strengthen North America's role in premium product adoption and early commercialization of connected eyewear.
Europe remains the second-largest regional bloc in the eyeglasses market, supported by independent optician networks, a strong premium frame culture, and ongoing retail consolidation. Fielmann expects record results for fiscal year 2025 and has guided for EUR 2.55 billion to EUR 2.60 billion in fiscal year 2026 sales, supported by the planned rollout of AI-enabled automated refraction across 300 European stores and 70 new store openings in 2026. Italy continues to hold strategic importance through the Belluno manufacturing base, which supports much of the premium frame supply chain for major eyewear groups. Europe also plays a major role in smart eyewear launches, as the June 2026 Meta Glasses rollout is expected to include the United Kingdom, France, Italy, Germany, and Spain. These factors keep the region central to premium design, manufacturing quality, and branded value capture in the eyeglasses market.
Asia-Pacific is forecast to register an 11.56% compound annual growth rate through 2031, making it the fastest-growing region in the eyeglasses market. The region has the world's highest myopia burden, and the World Health Organization Western Pacific office has described myopia as reaching epidemic levels, with prevalence near 50% among adolescents in China and Singapore and up to 80% among young adults in parts of East Asia. This trend creates a structurally strong correction base, especially among school-age and young adult populations entering long-term prescription cycles earlier than those in many other regions. India remains an important growth pocket, as organized optical retail continues to expand while disposable income and unmet correction needs rise.
- Bausch + Lomb Corporation
- Carl Zeiss
- Charmant Group
- De Rigo Vision S.p.A.
- EssilorLuxottica
- Fielmann Group AG
- HOYA
- HOYA
- JINS Holdings Inc.
- Kering Eyewear S.p.A.
- Lenskart Solutions Private Limited
- Marcolin S.p.A.
- Nidek
- Rodenstock
- Safilo Group S.p.A.
- Silhouette International Schmied AG
- Specsavers Optical Group Limited
- The Cooper Companies
- Warby Parker Inc.
- Zenni Optical, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Myopia, Presbyopia, and Digital Eye Strain Burden
- 4.2.2 Growth in Premiumization and Fashion-Led Frame Replacement Cycles
- 4.2.3 Expansion of Omnichannel Optical Retail and Online Try-On
- 4.2.4 Smart Eyewear Convergence With AR, Audio, and Health Functions
- 4.2.5 Rising Myopia Management Adoption in Children and Young Adults
- 4.2.6 Increased Employer and Insurer-Funded Vision Benefits in Mature Markets
- 4.3 Market Restraints
- 4.3.1 High Prevalence of Substitution From Contact Lenses and Refractive Surgery
- 4.3.2 Counterfeit and Grey-Market Frames Eroding Premium Pricing
- 4.3.3 Dependence on Skilled Optician Distribution and Fitting Infrastructure
- 4.3.4 Consumer Trade-Down During Discretionary Spending Slowdowns
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Prescription Eyeglasses
- 5.1.2 Reading Glasses
- 5.1.3 Sunglasses
- 5.1.4 Smart Glasses
- 5.1.5 Safety and Sports Eyewear
- 5.2 By Frame Material
- 5.2.1 Plastic
- 5.2.2 Metal
- 5.2.3 Acetate
- 5.2.4 Titanium
- 5.2.5 Other Frame Materials
- 5.3 By Lens Type
- 5.3.1 Single Vision
- 5.3.2 Bifocal
- 5.3.3 Progressive
- 5.3.4 Photochromic
- 5.3.5 Polarized
- 5.3.6 Others
- 5.4 By Distribution Channel
- 5.4.1 Optical Stores
- 5.4.2 Retail Chains
- 5.4.3 E-Commerce
- 5.4.4 Hospitals and Eye Care Clinics
- 5.4.5 Others
- 5.5 By End User
- 5.5.1 Adults
- 5.5.2 Children
- 5.5.3 Seniors
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Bausch + Lomb Corporation
- 6.3.2 Carl Zeiss AG
- 6.3.3 Charmant Group
- 6.3.4 De Rigo Vision S.p.A.
- 6.3.5 EssilorLuxottica
- 6.3.6 Fielmann Group AG
- 6.3.7 Hoya Corporation
- 6.3.8 HOYA CORPORATION
- 6.3.9 JINS Holdings Inc.
- 6.3.10 Kering Eyewear S.p.A.
- 6.3.11 Lenskart Solutions Private Limited
- 6.3.12 Marcolin S.p.A.
- 6.3.13 NIDEK CO., LTD.
- 6.3.14 Rodenstock GmbH
- 6.3.15 Safilo Group S.p.A.
- 6.3.16 Silhouette International Schmied AG
- 6.3.17 Specsavers Optical Group Limited
- 6.3.18 The Cooper Companies, Inc.
- 6.3.19 Warby Parker Inc.
- 6.3.20 Zenni Optical, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment