

|
시장보고서
상품코드
2100561
글리세린 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Glycerin - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
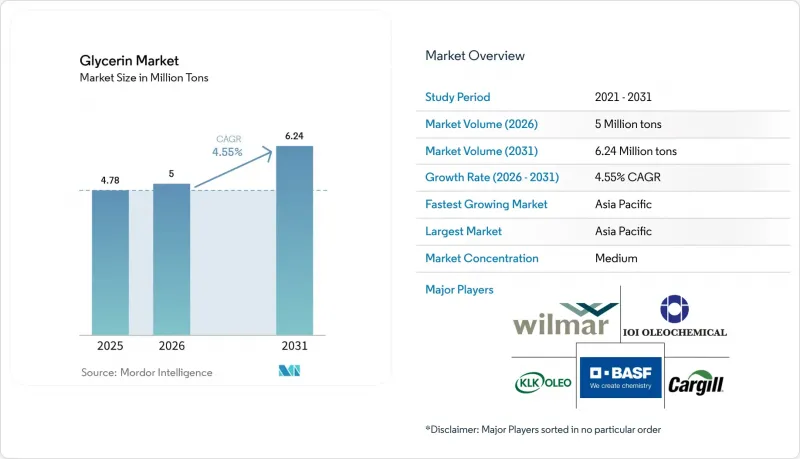
글리세린 시장 규모는 2025년에 478만 톤으로 평가되어 2026년 500만 톤에서 2031년까지 624만 톤에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.55%를 나타낼 전망입니다.
본 보고서는 등급(조글리세린 및 정제 글리세린), 원료(바이오디젤, 지방산, 지방알코올, 기타), 용도(퍼스널케어 및 화장품, 의약품, 식품 및 음료, 폴리에테르 폴리올 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시되어 있습니다.
세계 글리세린 시장 동향 및 인사이트
제약 업계에서 USP 등급 글리세린 수요 급증
FDA가 2023년에 모든 첨가제 배치에 대해 디에틸렌글리콜 및 에틸렌글리콜 검사를 의무화함에 따라, GMP 조건 하에서 제조된 순도 99.5% 이상의 글리세린에 대한 수요가 급격히 전환되었습니다. 2025년 루이 드레퓌스 컴퍼니가 인도네시아에서 진행할 생산 능력 확충과 독일 Verbio의 사상 최대 생산량은 글리세린 시장에서 규제 준수 공급을 확보하기 위한 전 세계적인 경쟁을 여실히 보여주고 있습니다. 경구 및 외용 제제가 여전히 주요 판매 경로이며, 인도의 PLI(생산 연계 인센티브) 제도에 따라 하이데라바드 및 아메다바드 근교의 정제 업체들은 국내 API(원료의약품)에 대한 완전한 추적성을 확보할 수 있는 부형제를 조달할 수 있도록, 업스트림 공정으로의 통합을 추진하고 있습니다.
퍼스널케어 및 화장품 업계에서의 활용 확대
합성 보습제에 대한 소비자의 까다로운 시선과 지속가능성 기준의 강화로 인해, 보습제, 세안제, 에센스에서 식물성 글리세린의 사용이 확대되고 있으며, 2024년부터 2025년까지 출시되는 주요 브랜드 제품에는 포장에 '천연 유래'라고 명시되어 있습니다. BASF와 Acies Bio와 같은 제휴 관계에서는 글리세린과 함께 사용되는 경우가 많은 업스트림 공정의 계면활성제 제조에 재생 가능 메탄올 경로를 활용하고 있으며, 이를 통해 글리세린 시장의 ‘클린 뷰티’ 주장에서 글리세린의 역할이 확고해지고 있습니다.
바이오디젤 원료와 연동되는 원유 글리세린 가격 변동
조글리세린 가격은 바이오디젤 생산량 및 원료 비용과 높은 상관관계를 보이며, 글리세롤 시장에서 가격 변동을 최종 고객에게 전가할 수 없는 정제업체 및 배합업체에게 이익률 압박 요인으로 작용하고 있습니다. 브라질에서는 2023년 수출액이 출하량이 증가했음에도 불구하고 52.9% 감소했으며, 바이오디젤 혼합 의무 비율 인상에 따른 공급 과잉이 판매량과 이익률을 분리시키고 있는 실태가 부각되었습니다. 아르헨티나에서는 정책 전환에 따라 유휴 설비율이 70%를 초과하고 있어 공급이 불안정하고 현물 가격이 급등락하고 있으며, 제약 업계의 구매자들은 재고를 많이 보유할 수밖에 없어 운전 자금 수요가 확대되고 있습니다.
부문 분석
2025년에는 정제 제품이 글리세린 시장 점유율의 69.1%를 차지하며, 의약품, 퍼스널케어, 식품 분야의 구매자들이 USP 등급의 추적성을 요구하고 있어, 글리세린 시장 규모에서 차지하는 그 비율은 연평균 성장률(CAGR) 5.02%로 확대될 것으로 예측됩니다. FDA의 불순물 규제로 인해 전 세계적으로 다단계 증류 및 이온 교환 프로젝트가 가속화되었으며, 2024년부터 2025년까지 원료 글리세린과 정제 글리세린의 가격 차이는 400-700달러/t로 확대되었습니다.
Verbio나 Louis Dreyfus와 같은 통합형 기업들은 바이오디젤 복합 시설이 의약품용 프리미엄을 사내에서 수익화할 수 있음을 입증하고 있는 반면, Argent Energy의 중급 테크니컬 등급(99.0-99.5%)은 USP 인증이 필요 없는 산업용 사용자들을 위한 수요 공백을 메우고 있습니다. 정제 공정을 도입하는 바이오디젤 플랜트가 늘어남에 따라 원유 글리세린의 수출량은 감소하고 있지만, 전 세계 정제 글리세린 공급은 여전히 부족하여 북미 및 유럽의 프리미엄 가격을 지탱하고 있습니다.
지역별 분석
아시아태평양은 세계 수요의 49.03%를 차지하고 있으며, 2031년까지 연평균 5.09%의 성장률을 보일 것으로 예측되어 글리세롤 시장에서 가장 큰 기여를 할 것으로 전망됩니다. 중국은 바이오디젤의 대부분을 EU로 수출하고 있지만, 이에 수반되는 원료 글리세린은 국내 유지화학 용도로 확보하고 있습니다. 한편, 인도가 2030년까지 바이오디젤 혼합률 5%를 목표로 하는 움직임은 사용 후 식용유 회수 인프라가 정비된다면 공급을 대폭 늘릴 가능성이 있습니다. 일본과 한국은 국내 생산량이 제한적이기 때문에 USP 등급 제품을 수입하고 있으며, 이로 인해 말레이시아와 인도네시아의 정제 업체들은 시장 접근성을 확보하기 위해 WHO-GMP 인증 취득을 서두르고 있습니다.
북미에서는 글리세린 시장에서 구조적인 공급 부족이 지속되고 있으며, 원유 가격의 급격한 변동에도 불구하고 브라질 및 동남아시아로부터의 수입이 계속되고 있습니다. 캐나다의 재생 가능 디젤 공동 처리는 국내 공급을 더욱 핍박하고 있으며, 이는 미국 멕시코만 연안 및 중서부 지역의 바이오디젤 집적지 인근에서 진행되는 현지 정제 프로젝트의 중요성을 부각시키고 있습니다. 멕시코의 글리세린 시장 역시 수요를 충족하기 위해 지역 내 수입에 의존하고 있습니다.
유럽의 기존 지배력은 디젤 수요 감소와 HVO로의 정책 전환에 따라 약화되고 있지만, RED II에서 글리세린의 부가가치화에 대한 이중 계상으로 인해 바이오 ECH 및 프로파일렌글리콜로의 하류 전환이 촉진되어 글리세롤 시장 전체의 발전을 뒷받침하고 있습니다. 엄격한 산림 벌채 규제로 인해 인도네시아와 말레이시아의 원료 공급은 압박을 받고 있지만, 네덜란드와 독일의 폐유 공급망은 ISCC 인증 하에 공급을 유지하고 있습니다. 남미에서는 대량의 원유 글리세린이 공급되고 있으나, B15 도입 후 브라질의 마진 급락과 아르헨티나의 정책 변동이 불확실성을 야기하고 있습니다. 중동 시장은 아직 발전 단계에 있지만, Sipchem과 LyondellBasell의 석유화학 사업 다각화 움직임 등을 통해 탄력을 받고 있으며, 향후 해당 지역의 글리세린 수급 균형에 영향을 미칠 가능성이 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.11According to Mordor Intelligence, the glycerin market size was valued at 4.78 Million tons in 2025 and is estimated to grow from 5 Million tons in 2026 to reach 6.24 Million tons by 2031, at a CAGR of 4.55% during the forecast period (2026-2031).
This report is Segmented by Grade (Crude Glycerin and Refined Glycerin), Source (Biodiesel, Fatty Acids, Fatty Alcohols, and Other Sources), Application (Personal Care and Cosmetics, Pharmaceuticals, Food and Beverage, Polyether Polyols, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (tons).
Global Glycerin Market Trends and Insights
Surging Demand for USP-grade Glycerin in Pharmaceutical Industry
FDA's 2023 requirement to test every excipient batch for diethylene and ethylene glycols triggered a sharp pivot toward 99.5%-plus glycerin produced under GMP conditions. Indonesian capacity additions by Louis Dreyfus Company in 2025 and record output from Verbio in Germany illustrate the global scramble for compliant supply in the glycerin market. Oral and topical formulations remain the core outlets, and India's PLI scheme is prompting refiners near Hyderabad and Ahmedabad to backward-integrate so that domestic APIs can secure fully traceable excipients.
Increasing Use in the Personal Care and Cosmetics Industries
Consumer scrutiny of synthetic humectants and tighter sustainability norms are lifting vegetable-glycerin penetration in moisturizers, cleansers, and serums, with major brand launches in 2024-2025 citing natural origin on pack. Partnerships such as BASF-Acies Bio leverage renewable-methanol routes for upstream surfactants that often co-formulate with glycerin, entrenching its role in "clean beauty" claims within the glycerin market.
Volatile Crude-Glycerin Prices Linked to Biodiesel Feedstocks
Crude-glycerin pricing exhibits high correlation with biodiesel production volumes and feedstock costs, creating margin compression for refiners and formulators who cannot pass through price swings to end customers in the glycerol market. Brazil's 2023 export revenue fell 52.9% even as shipments climbed, proving how oversupply from rising biodiesel blend mandates decouples volume from margin. In Argentina, idle capacity topping 70% amid shifting policy keeps supply erratic and spot prices whipsawing, forcing pharmaceutical buyers to hold more inventory and widening working-capital needs.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Vegetable-Sourced Glycerin in Food Industry
- Emergence of Solid-State Glycerin Electrolytes for Next-Gen Batteries
- Availability of Substitutes (Propylene Glycol, Sorbitol)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Refined material captured 69.1% of the glycerin market share in 2025, and its portion of the glycerin market size is set to increase at a 5.02% CAGR because drug, personal-care, and food buyers require USP-grade traceability. The FDA impurity rule accelerated multi-stage distillation and ion-exchange projects worldwide, widening the crude-to-refined margin spread to USD 400-700/t in 2024-2025.
Integrated players such as Verbio and Louis Dreyfus demonstrate that biodiesel complexes can monetize the pharmaceutical premium in-house, while mid-tier technical grades (99.0-99.5%) from Argent Energy fill the gap for industrial users who do not need USP certification. As more biodiesel plants add purification, crude-export flows thin out, but global refined supply remains tight, underpinning premium pricing in North America and Europe.
Complete Report Scope:
- By Grade
- Crude Glycerin
- Refined Glycerin
- By Source
- Biodiesel
- Fatty Acids
- Fatty Alcohols
- Other Sources
- By Application
- Personal Care and Cosmetics
- Pharmaceuticals
- Food and Beverage
- Polyether Polyols
- Alkyd Resins and Surface Coatings
- Tobacco Humectants
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific owns 49.03% of global demand and is forecast to expand at 5.09% annually through 2031, making it the largest regional contributor in the glycerol market. China exports most of its biodiesel to the EU yet retains associated crude glycerin for domestic oleochemical uses, while India's push to a 5% biodiesel blend by 2030 could unleash significant incremental supply once used-cooking-oil collection infrastructure scales. Japan and South Korea import USP-grade volumes because local production is limited, directing Malaysian and Indonesian refiners to seek WHO-GMP certification to secure market access.
North America remains structurally short in the glycerin market, so imports from Brazil and Southeast Asia persist despite volatile crude-price swings. Renewable diesel co-processing in Canada is tightening domestic supply further, underlining the value of local purification projects near the US Gulf Coast and Midwest biodiesel clusters. The Mexico glycerine market also relies on regional import flows to meet demand.
Europe's historic dominance is ebbing as diesel demand falls and policy pivots toward HVO, yet RED II's double-counting of glycerin valorization encourages downstream conversion to bio-ECH and propylene glycol, supporting development across the glycerol market. Stringent deforestation rules squeeze feedstock from Indonesia and Malaysia, but waste-oil streams in the Netherlands and Germany maintain flow under ISCC certification. South America delivers large crude volumes, though Brazil's margin collapse after B15 implementation and Argentina's policy swings inject uncertainty. The Middle East is nascent but gaining traction via petrochemical diversification moves such as Sipchem-LyondellBasell, which could later influence regional glycerin balances.
- ADM
- Aemetis Inc.
- BASF
- Cargill Inc.
- Dow Chemical Co.
- Emery Oleochemicals
- Godrej Industries
- IOI Corporation Berhad
- Kao Corporation
- KLK OLEO
- Louis Dreyfus Company
- Munzer Bioindustrie GmbH
- Musim Mas Group
- Oleon NV
- Procter & Gamble
- Renewable Biofuels
- Stepan Company
- Thai Glycerine Co.
- Vance Group Ltd.
- Vantage Specialty Chemicals
- Wilmar International Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for USP-grade glycerin in pharmaceuticals
- 4.2.2 Increasing use in personal care & cosmetics
- 4.2.3 Rising adoption of vegetable sourced glycerin in food industry
- 4.2.4 Emergence of solid-state glycerin electrolytes for next-gen batteries
- 4.2.5 Circular-economy projects converting crude glycerin to bio-ECH
- 4.3 Market Restraints
- 4.3.1 Volatile crude-glycerin prices linked to biodiesel feedstocks
- 4.3.2 Availability of substitutes (propylene glycol, sorbitol)
- 4.3.3 Sustainability scrutiny on palm-oil supply chains
- 4.4 Value Chain Analysis
- 4.5 Feedstock Analysis
- 4.6 Pricing Analysis (Historical & Forecast)
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Grade
- 5.1.1 Crude Glycerin
- 5.1.2 Refined Glycerin
- 5.2 By Source
- 5.2.1 Biodiesel
- 5.2.2 Fatty Acids
- 5.2.3 Fatty Alcohols
- 5.2.4 Other Sources
- 5.3 By Application
- 5.3.1 Personal Care and Cosmetics
- 5.3.2 Pharmaceuticals
- 5.3.3 Food and Beverage
- 5.3.4 Polyether Polyols
- 5.3.5 Alkyd Resins and Surface Coatings
- 5.3.6 Tobacco Humectants
- 5.3.7 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 Italy
- 5.4.3.4 France
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 South Africa
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global overview, Market overview, Core segments, Financials, Strategic info, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 ADM
- 6.4.2 Aemetis Inc.
- 6.4.3 BASF
- 6.4.4 Cargill Inc.
- 6.4.5 Dow Chemical Co.
- 6.4.6 Emery Oleochemicals
- 6.4.7 Godrej Industries
- 6.4.8 IOI Corporation Berhad
- 6.4.9 Kao Corporation
- 6.4.10 KLK OLEO
- 6.4.11 Louis Dreyfus Company
- 6.4.12 Munzer Bioindustrie GmbH
- 6.4.13 Musim Mas Group
- 6.4.14 Oleon NV
- 6.4.15 Procter & Gamble
- 6.4.16 Renewable Biofuels
- 6.4.17 Stepan Company
- 6.4.18 Thai Glycerine Co.
- 6.4.19 Vance Group Ltd.
- 6.4.20 Vantage Specialty Chemicals
- 6.4.21 Wilmar International Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment
- 7.2 Rapid uptake of glycerin in e-cigarette liquids


