

|
시장보고서
상품코드
2113237
자동차 내비게이션 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Navigation System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
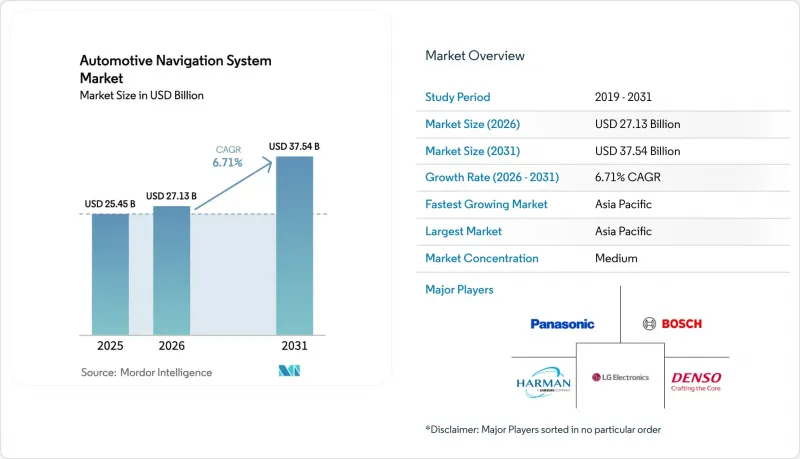
에 의하면, 자동차 내비게이션 시스템 시장은 2025년 254억 5,000만 달러에서 2026년에는 271억 3,000만 달러로 확대되어 2031년까지 375억 4,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년)에 CAGR 6.71%를 기록할 전망입니다.
본 보고서는 기기 유형(대시보드 내장형 내비게이션 시스템, 휴대용 내비게이션 기기 등), 기술(2D 지도 등), 차종(승용차, 상용차),구성 부품(하드웨어 등), 연결성(임베디드 시스템 등), 판매 채널(OEM 탑재 시스템 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 자동차 내비게이션 시스템 시장 동향 및 인사이트
커넥티드카 및 자율주행 차량에 대한 수요 증가
2025년에는 유럽 및 북미에서 출하되는 차량의 대부분에 내장형 커넥티비티 모듈이 탑재됨에 따라, 내비게이션을 중심으로 한 운전 지원 기능의 도입 기반이 더욱 확대될 것입니다. 센티미터 단위의 차선 형태를 갖춘 고해상도 지도는 현재 어댑티브 크루즈 컨트롤,차선 유지 보조, 자동 주차의 기반이 되고 있으며, 내비게이션은 단순한 경로 안내에서 위치 파악의 핵심으로 그 역할을 전환하고 있습니다. 테슬라의 소프트웨어는 센서보다 먼저 도로 토폴로지를 읽어들이는 방식으로 도시 지역의 에너지 효율을 8-12% 향상시키고 있습니다. 자동차 제조업체들은 매핑,위치 파악, 경로 계획을 하나의 스택으로 통합할 수 있는 공급업체를 우선시하고 있으며, 이로 인해 자동차 내비게이션 시스템 시장 전체에서 수직 통합이 가속화되고 있습니다. 도로 상황에 반응하는 것이 아니라 이를 예측하는 예측 기능은 차별화 요소로 자리 잡고 있으며, 레벨 2+ 및 향후 레벨 3 자율주행 프로그램을 뒷받침하고 있습니다.
공장 출고 시 기본 장착형 인포테인먼트/내비게이션 유닛의 보급률
일본, 유럽, 북미에서 공장 출고 시 기본으로 장착되는 내비게이션 시스템의 보급률은 차량 1대당 추가 하드웨어 비용을 50달러 미만으로 억제하는 인포테인먼트 번들 전략에 힘입어 2025년에 급증했습니다. EU의 일반 안전 규정(General Safety Regulation)에서는 지도 데이터를 기반으로 한 속도 제한 인식이 의무화되어 있어, 이에 따라 내장형 장치의 역할이 더욱 공고해지고 있습니다. Harman Ignite와 같은 플랫폼은 음성 어시스턴트 및 전자상거래를 통합하여 사용자를 OEM 생태계에 묶어두고, 앱을 통한 지속적인 수익을 창출하고 있습니다. 가격 프리미엄이 축소되고 ADAS와의 연동이 강화됨에 따라, 자동차 내비게이션 시스템 시장에서 내장형 시스템이 스마트폰으로부터 점유율을 되찾아가고 있습니다.
무료 스마트폰 내비게이션 대안
Google Maps와 Apple Maps는 무료 경로 안내, 빈번한 업데이트, 캘린더 연동 기능을 제공하고 있으며, 2025년에는 미국 운전자들이 차량용 내비게이션 시스템보다 스마트폰을 더 선호하게 될 것입니다. 휴대용 내비게이션 기기 분야에서 이러한 서비스의 지배력은 무너졌으며, 2020년부터 2025년에 걸쳐 가민(Garmin)의 매출은 42% 감소했습니다. 자동차 제조업체들은 이에 대응해 CarPlay나 Android Auto를 통합하고 있지만, 그렇게 함으로써 인터페이스 제어권과 데이터 수익화 기회를 포기하게 됩니다. 스마트폰의 편의성과 기능 면에서 동등하다고 여겨지는 점은 특히 가격에 민감한 부문에서 자동차 내비게이션 시스템 시장에 계속해서 역풍으로 작용하고 있습니다.
부문 분석
스마트폰 기반 솔루션은 익숙한 인터페이스와 추가 비용이 들지 않는다는 장점 덕분에 2025년 자동차 내비게이션 시스템 시장 점유율 48.11%를 유지했습니다. 반면, 대시보드 내장형 시스템의 경우, 자동차 제조업체들이 차량에 최적화된 위치 정보 측정이 필요한 ADAS(첨단 운전자 지원 시스템)와 내비게이션을 통합함에 따라 2031년까지 연평균 성장률(CAGR) 12.84%를 나타낼 것으로 예측됩니다. 대시보드 내장형 차량 내비게이션 시스템 시장 규모는 공장 출고 시 기본 사양의 보급 확대를 반영하여, 2031년까지 189억 달러에 달할 것으로 예측됩니다. 휴대용형은 틈새 업무 용도로 축소되었지만, 기기의 휴대성이 중시되는 상황에서는 여전히 이용되고 있습니다.
신뢰성과 센서와의 긴밀한 통합을 통해 임베디드형 플랫폼은 독자적인 가치 제안을 실현하고 있습니다. 알파인의 ‘Halo11’은 스마트폰이 연결되어 있지 않은 경우에도 안내를 지속적으로 제공하여 전문 운전자의 요구를 충족시키고 있습니다. 파이오니어가 알렉사(Alexa) 음성 제어 기능을 통합한 것은 소비자용 IoT 생태계와 차량 기능의 융합을 입증하고 있습니다. 무선 업데이트(OTA)를 통해 스마트폰과의 지도 정보 최신도 차이가 줄어들어, 자동차 내비게이션 시스템 시장 내 점유율의 점진적인 회복을 뒷받침하고 있습니다.
기존의 2D 지도는 데이터 요구 사항이 낮고 하드웨어와의 호환성이 넓기 때문에 2025년 차량용 내비게이션 시스템 시장에서 51.63%의 시장 점유율을 차지했습니다. 증강현실(AR) 내비게이션은 연평균 성장률(CAGR) 24.72%로 확대되며, 프리미엄 부문에서 새로운 수익원을 개척할 전망입니다. 헤드업 디스플레이(HUD)의 보급에 따라, AR 지원 솔루션의 자동차 내비게이션 시스템 시장 규모는 2031년까지 50억 달러를 넘어설 것으로 예측됩니다.
콘티넨탈의 AR-HUD는 운전자의 시야 중 폭 130cm(51인치),높이 60cm(23인치) 영역에 실제 도로 영상에 풀컬러 그래픽을 투영하고, 7.5m(24피트 9인치)의 광학 거리를 시뮬레이션함으로써 운전자의 주의 산만을 줄여줍니다. WayRay사의 홀로그래픽 프로젝터는 햇빛 아래에서도 식별 가능한 풀컬러 이미지를 투사하며, 현재 메르세데스-벤츠의 EQS 모델에 탑재되어 있습니다. 파나소닉은 표시 위치를 정확하게 유지하기 위해 시선 추적 기능을 추가했으며, 이는 해당 기능의 급속한 발전을 여실히 보여주고 있습니다. 3D 지도와 음성 안내도 여전히 중요하지만, AR의 몰입감 있는 오버레이 표시는 차세대 경쟁의 최전선으로 자리 잡고 있습니다.
지역별 분석
아시아태평양은 2025년 자동차 내비게이션 시스템 시장에서 33.48%의 점유율을 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 6.93%를 기록하며 다른 모든 지역을 앞지를 것으로 전망됩니다. 인도에서 NavIC 지원 수신기에 대한 보조금은 국내 공급업체의 성장을 가속하고 있습니다. 이러한 동향은 현지 혁신을 뒷받침하고 있지만, 외국 공급업체가 자동차 내비게이션 시스템 시장에서 점유율을 확보하려면 데이터 주권에 관한 규정을 준수해야 합니다.
북미는 2025년에 두 번째로 높은 점유율을 기록했습니다. 제너럴 모터스(GM)는 CarPlay를 단계적으로 폐지하고 자사의 ‘Ultifi’ 스택으로의 전환을 계획하고 있으며, 이는 전략적 전환을 시사합니다. 포드의 ‘BlueCruise’는 내장 지도를 활용해 핸즈프리 구역을 지정하고 있으며, 이는 ADAS(첨단 운전자 지원 시스템) 브랜딩에서 내비게이션이 차지하는 역할을 부각시키고 있습니다. 캐나다에서는 겨울철 사고를 줄이기 위한 기상 오버레이 기능을 시범 도입하고 있으며, 이는 지역적 상황이 제품의 우선순위에 어떤 영향을 미치는지를 보여줍니다.
E-call 의무화와 프리미엄 차량의 높은 보급률이 유럽 시장의 기반을 형성하고 있습니다. 콘티넨탈은 2025년 내비게이션 및 인포테인먼트 사업에서 38억 유로의 매출을 기록하며, 1차 공급업체로부터의 견조한 수요를 반영하고 있습니다. 영국에서 2030년에 예정된 내연기관(ICE) 차량 판매 금지는 전기차 전용 내비게이션 시스템의 보급을 가속화할 것으로 예상되며, JLR의 ‘Pivi Pro’는 주행 거리 예측 기능을 중시하고 있습니다. 프랑스의 미슐랭은 시직(Sygic)의 지분 30%를 인수하며, 부문 간 융합이 진행되고 있음을 보여주고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.24According to Mordor Intelligence, the automotive navigation system market is expected to grow from USD 25.45 billion in 2025 to USD 27.13 billion in 2026 and is forecast to reach USD 37.54 billion by 2031, growing at a 6.71% CAGR over the forecast period (2026-2031).
This report is Segmented by Device Type (In-Dash Navigation Systems, Portable Navigation Devices, and More), Technology (2D Maps, and More), Vehicle Type (Passenger Cars, Commercial Vehicles), Component (Hardware, and More), Connectivity (Embedded Systems, and More), Distribution Channel (OEM-Installed Systems, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Navigation System Market Trends and Insights
Rising Demand for Connected and Autonomous-Ready Vehicles
The majority of vehicles in Europe and North America shipped with embedded connectivity modules in 2025, creating a larger installed base for navigation-centric driver-assistance functions. High-definition maps with centimeter-level lane geometry now underpin adaptive cruise, lane keeping, and automated parking, shifting navigation from simple routing to a localization backbone. Tesla's software loads the road topology before sensors, improving urban energy efficiency by 8-12%. Automakers favor suppliers that can integrate mapping, localization, and path-planning into a single stack, thereby accelerating vertical integration across the automotive navigation system market. Predictive capabilities that anticipate road conditions rather than reacting to them are becoming a differentiator, supporting Level 2+ and future Level 3 autonomy programs.
Penetration of Factory-Fitted Infotainment/Navigation Units
Factory-fit navigation penetration in Japan, Europe, and North America surged in 2025, driven by bundled infotainment strategies that lower incremental hardware cost to under USD 50 per vehicle. The EU's General Safety Regulation mandates speed limit recognition based on map data, further solidifying the role of embedded units. Platforms such as Harman Ignite integrate voice assistants and e-commerce, locking users into OEM ecosystems and generating recurring revenue from apps. Lower price premiums and tighter ADAS coupling mean that embedded systems are increasingly recapturing share from smartphones within the automotive navigation system market.
Free Smartphone-Navigation Substitutes
Google Maps and Apple Maps offer free routing, frequent updates, and calendar integration, leading the United States drivers to prefer phones over embedded systems in 2025. Their dominance in the portable navigation device segment collapsed, pushing Garmin's revenue down 42% between 2020 and 2025. Automakers respond by integrating CarPlay and Android Auto, yet doing so surrenders control of the interface and data monetization. The convenience and perceived parity of smartphones continue to be a headwind for the automotive navigation system market, particularly in price-sensitive segments.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for e-Call and Advanced Safety Compliance
- EV-Specific Range-Aware Routing Algorithms
- High Hardware and Software Development Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smartphone-based solutions retained 48.11% of the automotive navigation system market share in 2025, benefitting from familiar interfaces and zero incremental cost. In-dash systems, however, are forecast to grow at a 12.84% CAGR through 2031 as automakers integrate navigation with ADAS that demands vehicle-calibrated positioning. The automotive navigation system market size for in-dash units is projected to reach USD 18.9 billion by 2031, reflecting the rising penetration of factory-fit units. Portables have shrunk to niche commercial use but persist where device mobility matters.
Reliability and deeper sensor integration give embedded platforms a unique value proposition. Alpine's Halo11 continues to provide guidance even when smartphones are disconnected, satisfying professional drivers. Pioneer's integration of Alexa voice control demonstrates convergence between consumer IoT ecosystems and vehicle functions. Over-the-air updates narrow the map freshness gap with phones, supporting the gradual reclaiming of share inside the automotive navigation system market.
Traditional 2D maps held a 51.63% market share in the automotive navigation system market in 2025, driven by their low data requirements and broad hardware compatibility. Augmented-reality navigation will expand at a 24.72% CAGR, unlocking new revenue pockets in premium segments. The automotive navigation system market size for AR-enabled solutions is expected to surpass USD 5 billion by 2031 as head-up displays proliferate.
Continental's AR-HUD projects full-color graphics onto the real road view in a 130 cm (51 in) wide by 60 cm (23 in) high segment of the driver's field of vision, simulating an optical distance of 7.5 m (24 ft 9 in). distance, reducing driver distraction. WayRay's holographic projector delivers full-color images visible in sunlight and is currently implemented in Mercedes-Benz EQS models. Panasonic adds eye-tracking to maintain alignment, highlighting the rapid evolution of this feature. While 3D maps and voice guidance remain important, AR's immersive overlay positions it as the next competitive frontier.
Complete Report Scope:
- By Device Type
- In-Dash Navigation Systems
- Portable Navigation Devices (PNDs)
- Smartphone-Based Navigation
- By Technology
- 2D Maps
- 3D Maps
- Voice-Guided Navigation
- Augmented Reality Navigation
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Component
- Hardware
- Software
- Services
- By Connectivity
- Embedded Systems
- Connected Systems
- By Distribution Channel
- OEM-Installed Systems
- Aftermarket Systems
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle-East and Africa
- North America
Geography Analysis
The Asia-Pacific region held a 33.48% share of the automotive navigation system market in 2025 and is projected to outpace all other areas with a 6.93% CAGR through 2031. India's subsidies for NavIC-compatible receivers stimulate domestic supplier growth. These dynamics boost local innovation, although foreign vendors must navigate data-sovereignty rules to capture share inside the automotive navigation system market.
North America commanded the second-highest share in 2025. General Motors plans to phase out CarPlay in favor of its Ultifi stack, signaling a strategic pivot. Ford's BlueCruise relies on embedded maps to designate hands-free zones, illustrating the role of navigation in ADAS branding. Canada pilots weather-overlay features that reduce winter accidents, demonstrating how regional conditions influence product priorities.
E-call mandates and a high density of premium vehicles underpin the European market. Continental generated EUR 3.8 billion from navigation and infotainment in 2025, reflecting robust demand from Tier 1. The U.K.'s impending 2030 ICE ban is expected to accelerate the uptake of EV-specific navigation systems, with JLR's Pivi Pro emphasizing range prediction. France's Michelin acquired a 30% stake in Sygic, illustrating cross-segment convergence.
- TomTom International BV
- HERE Technologies
- Garmin Ltd.
- Continental AG
- Denso Corporation
- Robert Bosch GmbH
- Alpine Electronics
- Pioneer Corporation
- Mitsubishi Electric Corp.
- Aisin AW Co.
- Harman International
- JVCKENWOOD Corp.
- Panasonic Holdings Corporation
- Sony Group Corp.
- Visteon Corp.
- Faurecia Clarion
- LG Electronics Inc.
- Apple Inc. (CarPlay)
- Google LLC (Android Auto / Maps)
- WayRay AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Connected and Autonomous-Ready Vehicles
- 4.2.2 Penetration of Factory-Fitted Infotainment/Navigation Units
- 4.2.3 Regulatory Push for e-Call and Advanced Safety Compliance
- 4.2.4 EV-Specific Range-Aware Routing Algorithms
- 4.2.5 Subscription-Based OTA Map-Update Revenue Streams
- 4.2.6 Low-Cost Dual-Frequency GNSS + IMU Accuracy Gains
- 4.3 Market Restraints
- 4.3.1 Free Smartphone-Navigation Substitutes
- 4.3.2 High Hardware and Software Development Costs
- 4.3.3 GNSS Spoofing and Cyber-Attack Liability
- 4.3.4 Data-Sovereignty Laws Restricting Cloud Mapping
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD))
- 5.1 By Device Type
- 5.1.1 In-Dash Navigation Systems
- 5.1.2 Portable Navigation Devices (PNDs)
- 5.1.3 Smartphone-Based Navigation
- 5.2 By Technology
- 5.2.1 2D Maps
- 5.2.2 3D Maps
- 5.2.3 Voice-Guided Navigation
- 5.2.4 Augmented Reality Navigation
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Commercial Vehicles
- 5.4 By Component
- 5.4.1 Hardware
- 5.4.2 Software
- 5.4.3 Services
- 5.5 By Connectivity
- 5.5.1 Embedded Systems
- 5.5.2 Connected Systems
- 5.6 By Distribution Channel
- 5.6.1 OEM-Installed Systems
- 5.6.2 Aftermarket Systems
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 India
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 South Africa
- 5.7.5.4 Turkey
- 5.7.5.5 Rest of Middle-East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TomTom International BV
- 6.4.2 HERE Technologies
- 6.4.3 Garmin Ltd.
- 6.4.4 Continental AG
- 6.4.5 Denso Corporation
- 6.4.6 Robert Bosch GmbH
- 6.4.7 Alpine Electronics
- 6.4.8 Pioneer Corporation
- 6.4.9 Mitsubishi Electric Corp.
- 6.4.10 Aisin AW Co.
- 6.4.11 Harman International
- 6.4.12 JVCKENWOOD Corp.
- 6.4.13 Panasonic Holdings Corporation
- 6.4.14 Sony Group Corp.
- 6.4.15 Visteon Corp.
- 6.4.16 Faurecia Clarion
- 6.4.17 LG Electronics Inc.
- 6.4.18 Apple Inc. (CarPlay)
- 6.4.19 Google LLC (Android Auto / Maps)
- 6.4.20 WayRay AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


