

|
시장보고서
상품코드
2113456
유럽의 주사형 약물전달 시장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Injectable Drug Delivery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 유럽의 주사형 약물전달 시장 규모는 2025년에 2,138억 달러로 평가되며, 2026년 2,320억 달러에서 2031년까지 3,491억 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 8.52%가 될 전망입니다.
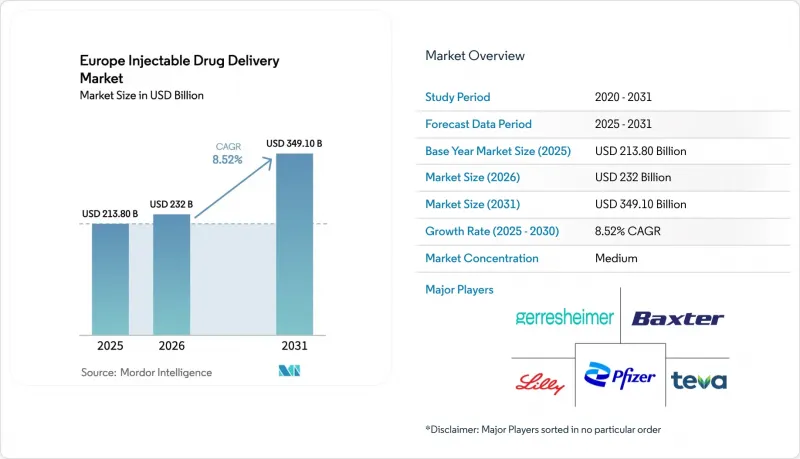
본 보고서는 기기 유형(기존형, 자가 주사형, 이식형 등), 치료 분야(심혈관, 당뇨병, 종양학 등), 최종사용자(병원, 전문 클리닉, 재택 의료 등), 원자재(붕규산 유리, 플라스틱, 지속가능한 폴리머), 및 지역(독일 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽 주사형 약물전달 시장의 동향 및 인사이트
만성 질환 유병률 증가
심혈관질환, 당뇨병, 암은 합쳐서 유럽 사망 원인의 60%를 차지하며, 소화관에서 분해되지 않는 주사용 생물학적 제제에 대한 지속적인 수요를 창출하고 있습니다. 2025년, 유럽 성인의 제2형 당뇨병 유병률은 9.2%에 달할 것으로 예상되며, 예방 인프라가 미비한 동유럽에서는 그 발생률이 가장 빠르게 상승하고 있습니다. 2025년에는 암 신규 환자 수가 270만 명에 달했습니다. 피하 투여형 트라스투주맙 및 펨브롤리주맙 덕분에 진료 시간이 75% 단축되어 외래 진료의 병목 현상이 완화되고 있습니다. 자가면역 질환의 부담도 증가하고 있습니다. 류마티스학 분야에서 생물학적 제제의 보급률은 프리필드 주사기에 담긴 종양괴사인자(TNF) 억제제 및 인터루킨 억제제에 힘입어 2025년까지 40%를 넘어섰습니다. 유럽연합 집행위원회의 2024년 의약품 전략에 따라 국경을 초월한 보험 급여가 통일되어, 고가의 주사제에 대한 환자의 접근성이 확대되고 있습니다.
자가 주사용 기기에 대한 선호도
2024년 유럽의 생물학적 제제 사용자 3,200명을 대상으로 실시한 설문조사에 따르면, 68%가 병원 방문보다 자가 주사를 선호하며, 그 이유로 일정의 유연성과 감염 위험이 낮다는 점을 꼽았습니다. 독일과 네덜란드의 법정 건강보험 기관은 재택 정맥 주사 치료에 대해 병원 요금보다 최대 40% 낮은 요금으로 보험 급여를 지급하고 있으며, 이로 인해 자동 주사기나 휴대용 펌프의 도입이 경제적으로 촉진되고 있습니다. 입소메드(Ipsomed)사의 자동 주사기 ‘YpsoMate 2.5’에는 투여량 및 시간 정보를 전송하는 블루투스 센서가 내장되어 있어, 복약 순응도 저조를 페널티로 삼는 가치 기반 계약을 지원하고 있습니다. UCB사의 로자놀릭시주맙은 전신성 중증 근력 약화증 환자가 스스로 조절할 수 있는 피하 투여를 가능하게 하여, 정기적인 병원 내 수액 투여를 불필요하게 만듭니다. ISO 11608 표준 준수를 통해 의약품과 의료기기의 상호 운용성이 촉진되어, 바이오시밀러로의 전환에 소요되는 비용이 더욱 절감됩니다.
비침습적 투여 경로로의 전환
충분한 생체 이용률이 달성된 분야에서는 경구, 경피, 흡입 제제가 주사제의 시장 점유율을 잠식하고 있습니다. 노보노르디스크의 경구용 세마글루티드는 생체이용률이 낮음에도 불구하고 2025년 말까지 독일 GLP-1 처방량의 15%를 차지하게 되었습니다. 이는 환자들 사이에서 주사바늘에 대한 강한 거부감이 있음을 반영합니다. 3M사의 경피 미세바늘 패치는 2025년에 인슐린 3상 임상시험에 진입했습니다. 이 제품은 피하 주사와 비교해 85%의 생물학적 동등성을 보여주면서도 날카로운 폐기물을 제거합니다. 흡입형 인슐린(아프레자)은 2024년에 EU에서 승인을 재개했으며, 주사를 꺼리는 1형 당뇨병 환자의 12%를 타겟으로 하고 있습니다. 점막 투과형 오피오이드 필름은 현재 완화 치료에서 선호되어 사용되고 있으며, 주사용 오피오이드의 수요를 더욱 억제하고 있습니다. 이러한 억제 경향은 주사에 대한 불안이나 손재주 문제가 흔한 소아 및 고령자층에서 가장 두드러집니다.
부문 분석
자가주사용 기기는 2025년 매출의 42.55%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 11.85%로 확대될 전망으로, 유럽 주사형 약물전달 시장에서 다른 모든 제형을 능가하는 성장률을 보이고 있습니다. 프리필드 주사기의 수요는 스테바나트 그룹의 ‘EZ-fill’ 폴리머 주사기 배럴에 의해 뒷받침되고 있습니다. 이 제품은 단백질 응집을 억제하여 150 mg/mL를 초과하는 고농도의 바이오의약품 투여를 가능하게 합니다. YpsoMate 2.5와 같은 자동 주사기에는 투여량 확인을 위한 블루투스 센서가 내장되어 있어, 복약 순응도에 기반한 보험 급여 모델 도입의 길을 열어주고 있습니다. 웨어러블 주사기는 정맥 주사의 통념을 뒤집고 있습니다. BD사의 ‘Libertas’는 30분 만에 5mL를 피하에 투여할 수 있어, 면역글로불린 투여 시 수 시간에 걸리는 정맥내 점적 주사를 대체하고 있습니다. 무바늘 제트 주사기는 환자의 불편감으로 인해 여전히 틈새 시장 제품이지만, PharmaJet사의 ‘Tropis’ 시스템은 피내 백신에 대해 유럽의약품청(EMA)의 승인을 획득하여 점차 수용되고 있음을 보여주고 있습니다.
스마트 커넥티드 주사기는 유럽의 주사형 약물전달 시장에서 가장 빠르게 성장하고 있는 하위 부문입니다. Biocorp사의 ‘Mallya’는 기존 인슐린 펜을 개조하여 실시간 데이터 수집을 가능하게 하는 제품으로, 비용 효율성을 중시하는 동유럽 보험사들이 요구하는 합리적인 가격의 개조 솔루션입니다. 기존의 유리 주사기, 바이알, 앰플은 다회 투여용 바이알을 통해 단위당 항생제 비용을 절감하는 병원의 수요를 여전히 충족시키고 있습니다. 메드트로닉(Medtronic)사의 ‘SynchroMed II’와 같은 이식형 펌프는 난치성 통증 관리 분야에서 틈새 시장 역할을 유지하고 있습니다. 박스터(Baxter)사의 ‘Homepump Eclipse’와 같은 피하 가정용 주입 펌프는 영국에서 실시된 시범 시험에서 낭포성섬유증으로 인한 재입원률을 40% 감소시켰습니다. 현재 인슐린 임상시험의 마지막 단계에 있는 마이크로니들 패치는 주사바늘을 두려워하는 사람들에게 유망한 대안이 될 것입니다.
종양학 분야에서의 적용은 2026년부터 2031년까지 연평균 성장률(CAGR) 9.75%로 확대될 전망이며, 이는 유럽 주사제 전달 업계에서 추적 대상인 모든 적응증 중 가장 빠른 성장률입니다. 2024년에 승인된 피하 투여형 펨브롤리주맙은 단 5분 만에 600mg을 투여할 수 있어, 주사실 이용률을 낮추고 연간 수천 시간의 치료 시간을 단축합니다. 독일에서는 HER2 양성 유방암의 신규 치료 시작 건수 중 트라스투주맙 바이오시밀러가 62%의 점유율을 차지하고 있어, 보험사들이 비용 절감 효과가 있는 주사제에 대한 수요가 높음을 알 수 있습니다. 당뇨병 분야는 2025년 매출의 38.53%를 차지했으나, 경구용 세마글루티드의 부상으로 인해 주사제 분야의 추가적인 성장은 억제되고 있습니다. 류마티스 관절염 및 크론병 등 자가면역 질환 분야는 견조한 성장세를 보이고 있으며, 투여 일정을 간소화하는 분기별 웨어러블 주사기 제제가 이를 뒷받침하고 있습니다.
암젠의 에볼로쿠맙 프리필드 펜을 필두로 한 심혈관계 주사제는, 가이드라인 개정에 따라 고위험 LDL 프로파일에 대한 PCSK9 억제제의 사용 범위가 확대됨에 따라 견조한 추세를 보이고 있습니다. C형 간염 치료용 주사제는 직접 작용형 항바이러스제가 경구 제형으로 전환됨에 따라 시장 점유율이 축소되고 있습니다. 통증 관리용 주사제는 오피오이드 규제가 강화되는 한편, 백신 시장은 COVID-19 이후 상황에서 수요가 정상화되고 있습니다. 불임 치료용 호르몬제와 성장 인자의 수요는 안정적으로 유지되고 있으며, 북유럽 시장에서는 피하 투여용 메토트렉세이트가 자동 주사기로 전환되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.25According to Mordor Intelligence, the Europe injectable drug delivery market size was valued at USD 213.80 billion in 2025 and is estimated to grow from USD 232 billion in 2026 to reach USD 349.10 billion by 2031, at a CAGR of 8.52% during the forecast period (2026-2031).
This report is Segmented by Device Type (Conventional, Self-Injectable, Implantable, and More), Therapeutic Application (Cardiovascular, Diabetes, Oncology, and More), End User (Hospitals, Specialty Clinics, Home Healthcare, and More), Raw Material (Borosilicate Glass, Plastics, Sustainable Polymers), and Geography (Germany, and More). Market Forecasts are Provided in Terms of Value (USD).
Europe Injectable Drug Delivery Market Trends and Insights
Rising Prevalence of Chronic Diseases
Cardiovascular disease, diabetes, and cancer together account for 60% of European mortality, creating persistent demand for injectable biologics that cannot survive gastrointestinal degradation. Type 2 diabetes prevalence reached 9.2% among European adults in 2025, with incidence rising fastest in Eastern Europe, where preventive infrastructure lags. Oncology incidence climbed to 2.7 million new cases in 2025; subcutaneous trastuzumab and pembrolizumab now cut chair time by 75%, easing ambulatory-unit bottlenecks. Autoimmune disease burden is also climbing: biologic penetration in rheumatology surpassed 40% by 2025, buoyed by tumor-necrosis-factor and interleukin blockers in prefilled syringes. The European Commission's 2024 Pharmaceutical Strategy harmonizes cross-border reimbursement, widening patient access to high-cost injectables.
Preference for Self-Injectable Devices
A 2024 survey of 3,200 European biologic users reported that 68% preferred self-injection over clinic visits, citing schedule flexibility and lower infection risk. Statutory insurers in Germany and the Netherlands reimburse home infusions at rates up to 40% below hospital tariffs, financially incentivizing adoption of auto-injectors and portable pumps. Ypsomed's YpsoMate 2.5 autoinjector integrates Bluetooth sensors that transmit dose and time stamps, supporting value-based contracts that penalize non-adherence. UCB's rozanolixizumab enables patient-controlled subcutaneous delivery for generalized myasthenia gravis, eliminating routine hospital infusions. Compliance with ISO 11608 standards facilitates drug-device interoperability, further lowering switching costs for biosimilar substitution.
Shift to Non-Invasive Delivery Routes
Oral, transdermal, and inhaled formulations are eating into injectable volumes in segments where adequate bioavailability has been achieved. Novo Nordisk's oral semaglutide captured 15% of German GLP-1 prescriptions by late 2025, despite lower bioavailability, reflecting strong needle aversion among patients. Transdermal microneedle patches from 3M entered Phase III insulin trials in 2025 and deliver 85% bioequivalence relative to subcutaneous injection, while eliminating sharps waste. Inhaled insulin (Afrezza) regained EU authorization in 2024 and targets the 12% of type 1 diabetics unwilling to inject. Transmucosal opioid films are now preferred in palliative care, further curbing demand for injectable opioids. The restraint is most pronounced in pediatric and geriatric cohorts, where injection anxiety and manual-dexterity issues are common.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Biologics & Biosimilars
- Integration of Smart Injectors with eHealth
- EMA Combination-Product Hurdles & Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Self-injectable devices generated 42.55% of 2025 revenue and are on track to expand at an 11.85% CAGR through 2031, outpacing all other formats within the Europe Injectable Drug Delivery market. Prefilled syringe demand is anchored by Stevanato Group's EZ-fill polymer barrels that curb protein aggregation, supporting high-concentration biologics above 150 mg/mL. Auto-injectors such as YpsoMate 2.5 embed Bluetooth sensors for dose confirmation, opening the door to adherence-linked reimbursement models. Wearable injectors are disrupting infusion paradigms; BD's Libertas can deliver 5 mL subcutaneously in 30 minutes, displacing multihour intravenous infusions for immunoglobulins. Needle-free jet injectors remain niche due to patient discomfort, yet PharmaJet's Tropis system gained EMA clearance for intradermal vaccines, a sign of gradual acceptance.
Smart connected injectors are the fastest-moving subsegment of the Europe Injectable Drug Delivery market. Biocorp's Mallya adapts legacy insulin pens for real-time data capture, an affordable retrofit sought by cost-conscious payers in Eastern Europe. Conventional glass syringes, vials, and ampoules still meet hospital demands where multi-dose vials lower per-unit antibiotic costs. Implantable pumps, such as Medtronic's SynchroMed II, maintain niche roles in refractory pain management. Subcutaneous home-infusion pumps like Baxter's Homepump Eclipse reduce cystic-fibrosis readmissions by 40% in UK pilots. Microneedle patches, currently in late-stage insulin trials, hold future promise for needle-phobic populations.
Oncology applications are poised to advance at a 9.75% CAGR between 2026-2031, the fastest of any indication tracked within the Europe Injectable Drug Delivery industry. Subcutaneous pembrolizumab, approved in 2024, administers 600 mg in only five minutes, cutting infusion-suite utilization and freeing thousands of chair-hours annually. Trastuzumab biosimilars now command 62% share of HER2-positive breast-cancer starts in Germany, illustrating payer appetite for cost-saving injectables. Diabetes held 38.53% of 2025 revenue; however, oral semaglutide's rise limits incremental injection growth. Autoimmune disorders such as rheumatoid arthritis and Crohn's disease are robust, supported by quarterly wearable-injector formulations that simplify dosing schedules.
Cardiovascular injectables, led by Amgen's evolocumab prefilled pen, hold steady as guideline updates broaden PCSK9 inhibitor usage for high-risk LDL profiles. Hepatitis injectables are waning as direct-acting antivirals migrate to oral formats. Pain-management injections face tighter opioid controls, while vaccine volumes normalize post-COVID-19. Fertility hormones and growth factors sustain stable demand as subcutaneous methotrexate transitions to autoinjectors in Nordic markets.
Complete Report Scope:
- By Device Type
- Conventional Drug Delivery Devices
- Self-injectable Drug Delivery Devices
- Prefilled Syringes
- Injection Pens
- Auto-injectors
- Needle-free Injectors
- Wearable Injectors
- Smart Connected Injectors
- Implantable Drug Delivery Devices
- Infusion Pumps (Sub-Q)
- Microneedle Systems
- By Therapeutic Application
- Cardiovascular Disease
- Diabetes
- Oncology
- Autoimmune Disorders
- Hepatitis
- Pain Management
- Infectious Diseases & Vaccines
- Others
- By End User
- Hospitals
- Specialty Clinics
- Home Healthcare Settings
- Ambulatory Surgery Centers
- Online Pharmacies
- By Raw Material
- Borosilicate Glass
- Plastics (COP/COC, PP, PC)
- Sustainable/Biodegradable Polymers
- Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Antares Pharma (Halozyme)
- Baxter
- Beckton Dickinson
- Catalent Pharma Solutions
- Eli Lilly and Company
- Gerresheimer
- Haselmeier GmbH
- Medtronic
- Nipro
- Novo Nordisk
- Owen Mumford
- Pfizer
- Recipharm
- SCHOTT
- SHL Medical AG
- Stevanato Group
- Terumo Corp.
- Teva Pharmaceutical Industries
- Vetter Pharma International
- West Pharmaceutical Services
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic diseases
- 4.2.2 Preference for self-injectable devices
- 4.2.3 Growth of biologics & biosimilars
- 4.2.4 Regulatory push for safety syringes
- 4.2.5 EU eco-design rules spurring polymer syringes
- 4.2.6 Integration of smart injectors with eHealth
- 4.3 Market Restraints
- 4.3.1 Shift to non-invasive delivery routes
- 4.3.2 EMA combination-product hurdles & cost
- 4.3.3 EU pharma-in-water producer liability
- 4.3.4 Shortages of borosilicate glass/resins
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Device Type
- 5.1.1 Conventional Drug Delivery Devices
- 5.1.2 Self-injectable Drug Delivery Devices
- 5.1.2.1 Prefilled Syringes
- 5.1.2.2 Injection Pens
- 5.1.2.3 Auto-injectors
- 5.1.2.4 Needle-free Injectors
- 5.1.2.5 Wearable Injectors
- 5.1.2.6 Smart Connected Injectors
- 5.1.3 Implantable Drug Delivery Devices
- 5.1.4 Infusion Pumps (Sub-Q)
- 5.1.5 Microneedle Systems
- 5.2 By Therapeutic Application
- 5.2.1 Cardiovascular Disease
- 5.2.2 Diabetes
- 5.2.3 Oncology
- 5.2.4 Autoimmune Disorders
- 5.2.5 Hepatitis
- 5.2.6 Pain Management
- 5.2.7 Infectious Diseases & Vaccines
- 5.2.8 Others
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Specialty Clinics
- 5.3.3 Home Healthcare Settings
- 5.3.4 Ambulatory Surgery Centers
- 5.3.5 Online Pharmacies
- 5.4 By Raw Material
- 5.4.1 Borosilicate Glass
- 5.4.2 Plastics (COP/COC, PP, PC)
- 5.4.3 Sustainable/Biodegradable Polymers
- 5.5 Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Antares Pharma (Halozyme)
- 6.3.2 Baxter
- 6.3.3 Becton, Dickinson and Company
- 6.3.4 Catalent Pharma Solutions
- 6.3.5 Eli Lilly and Company
- 6.3.6 Gerresheimer AG
- 6.3.7 Haselmeier GmbH
- 6.3.8 Medtronic plc
- 6.3.9 Nipro Corporation
- 6.3.10 Novo Nordisk A/S
- 6.3.11 Owen Mumford Ltd
- 6.3.12 Pfizer Inc.
- 6.3.13 Recipharm AB
- 6.3.14 SCHOTT AG
- 6.3.15 SHL Medical AG
- 6.3.16 Stevanato Group
- 6.3.17 Terumo Corp.
- 6.3.18 Teva Pharmaceutical Industries Ltd
- 6.3.19 Vetter Pharma International
- 6.3.20 West Pharmaceutical Services Inc.
- 6.3.21 Ypsomed Holding AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


