

|
시장보고서
상품코드
2113748
병사 현대화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Soldier Modernization - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 병사 현대화 시장 규모는 2025년 178억 1,000만 달러로 평가되었습니다. 2026년에는 184억 7,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 3.72%로 성장을 지속하여, 2031년까지 221억 7,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 유형(무기·탄약, 개인 방호 장비 등), 기술(치사성, 비치사성 등), 최종 사용자(육군 보병 및 특수작전부대), 구성 요소(하드웨어 및 소프트웨어), 플랫폼(보병, 차량 탑승 병사, 웨어러블 로봇),지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(미 달러)으로 제시되어 있습니다.
세계의 병사 현대화 시장 동향 및 인사이트
차세대 AI 지원형 조준 시스템
Smart Shooter사의 SMASH 시리즈와 같은 정밀 사격 제어 광학 장비는 전투 스트레스 상황에서도 95%의 명중률을 실현하고 있으며, 기존의 20-30% 명중률과 비교하여 전투 능력이 비약적으로 향상되었음을 보여줍니다. 미 육군의 ATLAS 프로토타입에 탑재된 머신러닝 알고리즘은 밀리초 단위로 탄도 계산을 수행하여 장거리 이동 목표물에 대한 공격을 가능하게 합니다. 이스라엘에서의 뛰어난 실증 실적과 미국에서 진행 중인 현장 시험을 통해 조달에 대한 신뢰도가 높아지고 있습니다. AI 기능은 기존 무기에 추가로 도입되므로 재훈련 부담을 최소화하는 동시에, 전장의 충격과 극한 온도를 견딜 수 있는 견고한 엣지 컴퓨팅 프로세서에 대한 수요를 촉진하고 있습니다. 도입 확대는 방위 산업 매출의 완만한 성장을 상쇄하는 프리미엄 가격 책정을 뒷받침하고 있으며, 이로 인해 병사 장비 현대화 시장의 연평균 성장률(CAGR)에 1.2%를 더하고 있습니다.
병사가 착용하는 소프트웨어 정의 무선(SDR) 도입
L3Harris사의 RF-7850S SPR 무전기는 현장에서 로드 가능한 소프트웨어를 통해 여러 레거시 파형 및 차세대 파형을 운용하여 부대 수준의 무전기 재고를 40% 줄입니다. Thales사의 AN/PRC-154 보병용 무전기는 개별 노드가 다운되더라도 음성 및 데이터 링크를 유지하는 자가 형성 메시 기능을 갖추고 있어, 전자전 공격 시 네트워크의 회복력을 높입니다. 소프트웨어 중심 아키텍처는 NATO의 상호운용성 교리에 부합하며, 향후 업그레이드 비용을 대폭 절감함으로써 24개월 이내에 현역 부대에 대한 광범위한 배치를 촉진합니다.
리튬 공급망의 변동
중국은 전 세계 리튬 정제량의 80%를 차지하고 있으며, 수출 규제 강화로 인해 현물 가격이 상승함에 따라 보병용 배터리 팩의 가격 경쟁력이 위협받고 있습니다. 미국 국방부(DoD)는 단일 국가에 대한 의존 위험을 분산하기 위해 국내 가공 업체에 1,180만 달러를 투자했으나, 상용 전기차 수요가 여전히 공급 전망치를 상회하고 있어 군에 대한 할당량이 제한되고 있습니다. 배터리 고장으로 인해 육군은 조기 교체에 연간 7,500만 달러 이상의 비용을 부담하고 있습니다. 대체 화학 조성은 유망하지만, 양산화까지 5년 이상 소요되므로 단기 성장률은 0.3포인트 하락했습니다.
부문 분석
개인 보호 시스템은 2025년 병사 현대화 시장의 35.02%를 차지하며, 모든 전투원에게 기초적인 생존성 계층으로서의 역할을 확고히 했습니다. 고급 초고분자량 폴리에틸렌(UHMWPE) 및 세라믹·그래핀 플레이트는 NIJ III+의 보호 성능을 유지하면서 경량화를 실현하여, 준비 태세 주기에 접어든 각국 육군으로부터 안정적인 교체 수요를 창출하고 있습니다. 한편, 외골격은 연평균 성장률(CAGR) 7.28%로 가장 빠르게 성장하고 있으며, 이는 단순한 방호가 아닌 성능 향상으로 중점이 이동하고 있음을 반영합니다. 록히드 마틴의 ‘ONYX’ 등의 프로그램에서는 38kg의 짐을 지고 행군하는 동안 대사 비용이 27% 감소한 것이 입증되어, 그 작전상의 가치가 뒷받침되었습니다. 외골격 솔루션을 활용한 병사 현대화 시장 규모는 가격 하락과 유지보수·물류 체계의 성숙에 따라 꾸준히 확대될 것입니다.
보다 광범위한 방호 장비 부문에서는 현재 임무 수행 후 건강 검진을 위해 충격 사건을 기록하는 폭발 센서가 통합되어 있습니다. 스마트 텍스타일에는 고고도 전개 시 체온을 유지하기 위한 발열 필라멘트가 내장되어 있습니다. 무기 및 탄약 하위 클러스터는 AI 조준 모듈과 긴밀히 연동되어 소대의 C4ISR 네트워크에 직접 연결되어 있습니다. 통신 및 표적 포착 키트는 탄도 운반체와 공장 출하 시 세트로 제공되는 경우가 늘어나고 있어, 번들 솔루션을 제공하는 벤더에게 유리한 생태계의 정착을 이끌어내고 있습니다. 외골격 제조업체는 방탄조끼 공급업체와 제휴하여 장착 위치를 통일함으로써, 병사의 전체 장비 세트에 걸쳐 모듈 간의 호환성을 확보하고 있습니다.
C4ISR 및 데이터 융합 시스템은 2025년 매출의 46.20%를 차지하며, 상황 인식이 모든 전투 능력과 생존성 향상을 뒷받침하고 있음을 여실히 보여주었습니다. 모듈식 센서 허브는 드론 영상, 대포병 레이더, AI가 생성한 표적 후보 정보를 통합합니다. 오픈소스 프레임워크는 용도 업그레이드를 가속화하여 10년에 걸친 위협의 진화 속에서도 플랫폼의 유용성을 유지합니다. 동시에 AR 및 HUD는 연평균 성장률(CAGR) 6.02%를 기록했습니다. 이는 미 육군이 2억 5,500만 달러 상당의 통합 시각 확장 시스템 3,000대 이상을 배치할 계획이 뒷받침한 결과입니다. AR 광학 기기에 기인한 병사 장비 현대화 시장 규모는 여전히 작지만, 광학 기기의 무게, 배터리 수명 및 시야 가림 현상의 개선에 따라 빠르게 확대되고 있습니다.
인공지능(AI) 모듈은 모든 기술 노드를 강화하고 있습니다. 예측 유지보수 솔루션은 임무 중단에 앞서 냉각 팬의 고장을 감지하고, 인지 무선 알고리즘은 전투 중 주파수 충돌을 자동으로 해결합니다. 비살상 시스템은 평화유지 활동에서 무력 행사 단계적 확대라는 선택지를 제공하는 지향성 에너지 방식의 눈부심 장치를 통해 시장 점유율을 확대되고 있습니다. 기동성 및 파워 어시스트 기술은 웨어러블 로보틱스의 발전과 맞물려, 수동식 부하 프레임이 동력식 보행 보조 기어로 진화하여 24시간 순찰 시 무릎에 가해지는 부담을 절반으로 줄이고 있습니다.
지역별 분석
북미는 2025년 지출의 44.92%를 차지했습니다. 이는 4만 개의 고글에 대해 2억 6,300만 달러 규모의 추가 계약을 수주한 고성능 야간 투시 고글 및 쌍안경 등의 미국 프로그램에 기인한 것입니다. 캐나다는 DICE 네트워크 구축을 추진하고 있으며, 공동 통합을 중시하면서 국내 전자기기 공급업체를 육성하고 있습니다. 멕시코는 대외 군사 판매를 통해 협력하고 있으며, 안정적인 기초 수요를 창출하고 있습니다.
아시아태평양은 주권 확보를 위한 노력과 분쟁 섬을 둘러싼 정세의 영향으로 연평균 성장률(CAGR) 6.52%로 성장을 지속하고 있습니다. 일본은 사상 최고 수준의 국방 예산을 미국 시스템과 연동되는 병사용 C4ISR 키트에 투입하고 있는 반면, 한국은 침입을 저지하기 위한 파워 아머의 시제품을 개발하고 있습니다. 인도는 ‘메이크 인 인디아(Make in India)’ 정책을 통해 비용과 능력의 균형을 도모하고 있으며, 이 정책에서는 외국 OEM 제조업체와 국영 무기 공장의 협력이 의무화되어 있습니다.
유럽에서는 NATO의 전력 정비 공약에 따라 조달을 가속화하고 있으며, 그 대표적인 사례가 독일의 36억 달러 규모 IdZ-ES 계약입니다. 영국은 국내 공급망을 혼란에 빠뜨리지 않으면서 ‘챌린저 3’에 차세대 모듈형 장갑을 장착하고, 58명의 일자리를 유지하면서 영국 인력을 활용하고 있습니다. 중동 및 아프리카에서는 사막 기후에서 검증된 신뢰성을 갖춘 기성(오프 더 셸프) 광학 장비나 무선 통신 세트가 선호되지만, 걸프 국가들에서는 장갑차 승무원을 위한 AR 헤드셋의 시범 도입이 점점 더 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the soldier modernization market size is expected to grow from USD 17.81 billion in 2025 to USD 18.47 billion in 2026 and is forecast to reach USD 22.17 billion by 2031 at 3.72% CAGR over 2026-2031.
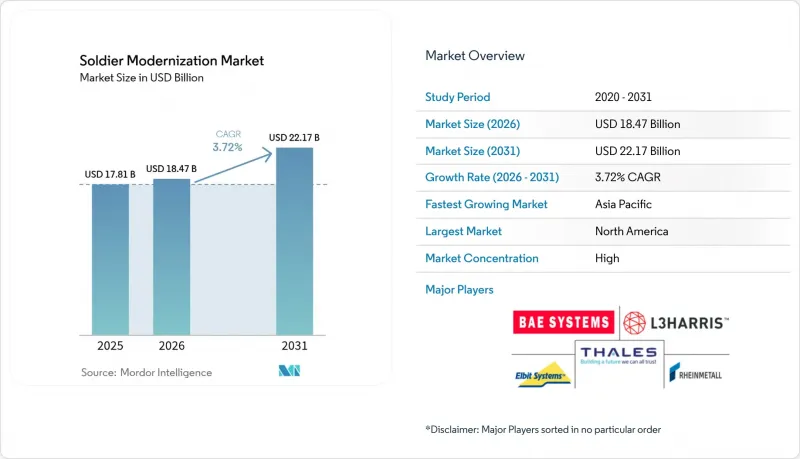
This report is Segmented by Type (Weapons and Ammunition, Personal Protection, and More), Technology (Lethal, Non-Lethal, and More), End User (Army Infantry and Special Operations Forces), Component (Hardware and Software), Platform (Dismounted Soldier, Mounted Soldier, and Wearable Robotics), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Soldier Modernization Market Trends and Insights
Next-gen AI-assisted targeting systems
Precision fire-control optics such as Smart Shooter's SMASH series deliver 95% hit probability under combat stress, compared with historical 20-30% accuracy rates, illustrating transformative lethality gains. Machine-learning algorithms embedded in the US Army ATLAS prototypes generate ballistic solutions within milliseconds, allowing moving-target engagement at extended ranges. High validation in Israel and ongoing US field testing accelerate procurement confidence. AI layers bolt onto existing weapons, minimizing retraining burdens while spurring demand for edge-compute processors ruggedized for battlefield shock and temperature extremes. Rising adoption supports premium pricing that offsets modest top-line defense growth, thus adding 1.2 percentage points to the soldier modernization market CAGR.
Soldier-worn software-defined radios adoption
L3Harris's RF-7850S SPR radio operates multiple legacy and future waveforms via field-loadable software, reducing unit-level radio inventories by 40%. Thales's AN/PRC-154 rifleman radio adds a self-forming mesh that maintains voice and data links even when individual nodes drop, raising network resilience during electronic-warfare attacks. Software-centric architectures align with NATO interoperability doctrine and slash future upgrade costs, pushing widespread fielding into active units within 24 months.
Lithium supply-chain volatility
China refines 80% of global lithium, and tightening export controls raise spot prices, jeopardizing battery pack affordability for dismounted soldiers. The US Department of Defense (DoD) funneled USD 11.8 million to domestic processors to dilute single-nation risk, yet commercial electric-vehicle demand still outstrips projected supply, constraining military allocation. Battery failure costs the Army over USD 75 million annually in premature replacements. Alternative chemistries are promising but remain five-plus years from scale, damping near-term growth by 0.3 percentage points.
Other drivers and restraints analyzed in the detailed report include:
- Lightweight ballistic-composite breakthroughs
- NATO STANAG-driven interoperability upgrades
- RF spectrum congestion on tactical bands
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Personal protection systems accounted for 35.02% of the 2025 soldier modernization market, cementing their role as the foundational survivability layer for every combatant. Advanced UHMWPE and ceramic-graphene plates cut weight while keeping NIJ III+ protection, which feeds consistent replacement demand from armies rotating into readiness cycles. Meanwhile, exoskeletons grew fastest at 7.28% CAGR, reflecting a pivot toward performance enhancement rather than mere protection. Programs such as Lockheed Martin ONYX documented a 27% metabolic-cost drop during 38 kg load marches, validating operational value. The soldier modernization market size for exoskeleton solutions will expand steadily as prices fall and maintenance logistics mature.
The broader protective gear category now integrates blast sensors that log concussive events for post-mission health checks. Smart textiles embed heating filaments that sustain body temperature in high-altitude deployments. Weapon and ammunition sub-clusters intertwine with AI-aiming modules, linking directly to squad C4ISR networks. Communication and target-acquisition kits increasingly arrive factory-paired with ballistic carriers, creating ecosystem stickiness that favors vendors offering bundled solutions. Exoskeleton makers partner with body-armor suppliers to align mounting points, ensuring modular compatibility across soldier equipment suites.
C4ISR and data-fusion systems held 46.20% of 2025 revenue, underscoring that situational awareness underwrites every lethality and survivability gain. Modular sensor hubs aggregate drone feeds, counter-battery radars, and AI-generated target nominations. Open-source frameworks accelerate application upgrades, preserving platform relevance across a decade of threat evolution. Concurrently, AR and HUDs clocked a 6.02% CAGR, boosted by the US Army's plan to field 3,000+ integrated visual augmentation system units valued at USD 255 million. The soldier modernization market size attributed to AR optics remains small but rises quickly as optics weight, battery life, and occlusion improve.
Artificial-intelligence modules enrich every technology node. Predictive-maintenance suites flag cooling-fan failures before mission aborts, while cognitive radio algorithms auto-de-conflict frequencies mid-battle. Non-lethal systems gain share via directed-energy dazzlers that offer escalation-of-force options for peacekeeping. Mobility and power-assist technologies dovetail with the wearable-robotics push, as passive load frames morph into powered gait-augmentation gear that halves knee strain on 24-hour patrols.
Complete Report Scope:
- Weapons and Ammunition
- Personal Protection
- Communication Systems
- Surveillance and Target Acquisition
- Exoskeletons
- Power and Energy Management
- Training and Simulation
- By Technology
- Lethal
- Non-Lethal
- C4ISR and Data Fusion
- Mobility and Power-Assist
- Augmented-Reality (AR)/Heads-Up Display (HUD)
- By End User
- Army Infantry
- Special Operations Forces
- By Component
- Hardware
- Software
- By Platform
- Dismounted Soldier
- Mounted Soldier
- Wearable Robotics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 44.92% of 2025 spending due to the US programs like the enhanced night vision goggle-binocular, which received a USD 263 million follow-on award for 40,000 goggles. Canada pursues the DICE network, emphasizing joint integration while nurturing local electronics suppliers. Mexico cooperates through foreign military sales, adding a stable baseline demand.
Asia-Pacific, propelled by sovereignty initiatives and contested-island scenarios, posts a 6.52% CAGR. Japan's record defense budgets channel funds into soldier C4ISR kits that synchronize with the US systems, whereas South Korea prototypes power armor to deter incursions. India balances cost and capability via Make in India, which mandates pairing foreign OEMs with public-sector ordnance factories.
Europe accelerates procurement under NATO readiness pledges, exemplified by Germany's USD 3.6 billion IdZ-ES contract. The UK fits next-generation modular armor on Challenger 3 without disrupting local supply chains, keeping 58 jobs while harvesting British talent. Middle East and Africa favor off-the-shelf optics and radio bundles with proven reliability in desert climates, though Gulf states increasingly pilot AR headsets for armored crews.
- BAE Systems plc
- Thales Group
- L3Harris Technologies, Inc.
- Elbit Systems Ltd.
- Rheinmetall AG
- Leonardo S.p.A.
- Safran SA
- Northrop Grumman Corporation
- General Dynamics Corporation
- Saab AB
- Teledyne Technologies Incorporated
- Ballistic Armor Co.
- RTX Corporation
- ASELSAN A.S.
- Avon Technologies plc
- Lockheed Martin Corporation
- SRI International
- MKU Limited
- Silvus Technologies, Inc. (Motorola Solutions, Inc.)
- Bharat Electronics Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Next-gen AI-assisted targeting systems
- 4.2.2 Soldier-worn software-defined radios (SDR) adoption
- 4.2.3 Lightweight ballistic-composite breakthroughs
- 4.2.4 NATO STANAG-driven interoperability upgrades
- 4.2.5 Battery-agnostic portable power packs
- 4.2.6 Post-Ukraine rapid re-equipment programs
- 4.3 Market Restraints
- 4.3.1 Lithium supply-chain volatility
- 4.3.2 RF spectrum congestion on tactical bands
- 4.3.3 Exoskeleton cost-benefit skepticism
- 4.3.4 Export-control limitations on advanced optics
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 Weapons and Ammunition
- 5.1.1 Personal Protection
- 5.1.2 Communication Systems
- 5.1.3 Surveillance and Target Acquisition
- 5.1.4 Exoskeletons
- 5.1.5 Power and Energy Management
- 5.1.6 Training and Simulation
- 5.2 By Technology
- 5.2.1 Lethal
- 5.2.2 Non-Lethal
- 5.2.3 C4ISR and Data Fusion
- 5.2.4 Mobility and Power-Assist
- 5.2.5 Augmented-Reality (AR)/Heads-Up Display (HUD)
- 5.3 By End User
- 5.3.1 Army Infantry
- 5.3.2 Special Operations Forces
- 5.4 By Component
- 5.4.1 Hardware
- 5.4.2 Software
- 5.5 By Platform
- 5.5.1 Dismounted Soldier
- 5.5.2 Mounted Soldier
- 5.5.3 Wearable Robotics
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 France
- 5.6.2.3 Germany
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BAE Systems plc
- 6.4.2 Thales Group
- 6.4.3 L3Harris Technologies, Inc.
- 6.4.4 Elbit Systems Ltd.
- 6.4.5 Rheinmetall AG
- 6.4.6 Leonardo S.p.A.
- 6.4.7 Safran SA
- 6.4.8 Northrop Grumman Corporation
- 6.4.9 General Dynamics Corporation
- 6.4.10 Saab AB
- 6.4.11 Teledyne Technologies Incorporated
- 6.4.12 Ballistic Armor Co.
- 6.4.13 RTX Corporation
- 6.4.14 ASELSAN A.S.
- 6.4.15 Avon Technologies plc
- 6.4.16 Lockheed Martin Corporation
- 6.4.17 SRI International
- 6.4.18 MKU Limited
- 6.4.19 Silvus Technologies, Inc. (Motorola Solutions, Inc.)
- 6.4.20 Bharat Electronics Limited


