|
시장보고서
상품코드
2113997
드릴 비트 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Drill Bit - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
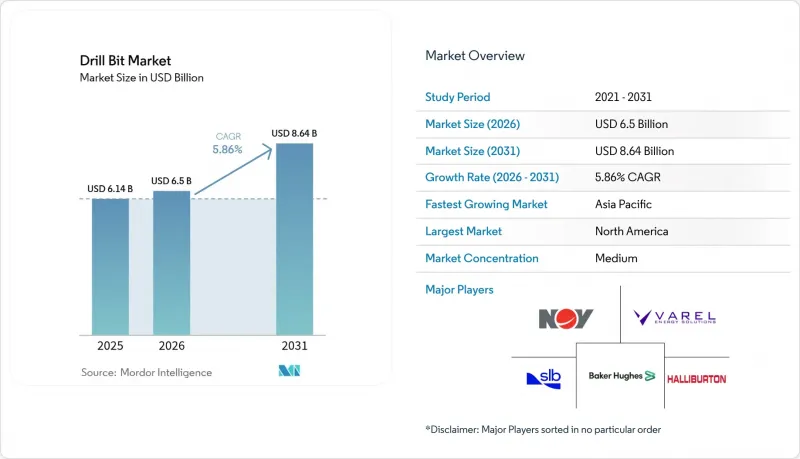
에 따르면 2026년 드릴 비트 시장 규모는 65억 달러로 추정되고 있으며, 2025년 61억 4,000만 달러에서 확대하며, 2031년에는 86억 4,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지 연평균 성장률(CAGR) 5.86%로 성장할 것으로 전망됩니다.
이 보고서는 유형별(롤러 콘 비트, 고정 커터 비트, 하이브리드 비트, 특수 비트), 설치 장소별(육상 및 해상), 용도별(석유 및 가스,광업, 지열, 우물 및 토목 건설), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 드릴 비트 시장의 동향 및 인사이트
북미 셰일가스의 부활
셰일가스 생산 확대가 세계 드릴 비트 시장을 촉진하고 있으며, 미국의 천연가스 생산량은 2025년 7조 2,000억 입방피트에서 2050년까지 8조 8,000억 입방피트로 증가할 전망입니다. 견고한 LNG 수출 계획에 힘입어 시추 장비 수요는 높은 수준을 유지하고 있으며, 퍼미안 분지에는 미국 육상 시추 장비의 60%가 집중되어 있습니다. 한 번의 시추로 20,000피트를 넘는 긴 수평 터널을 뚫음에 따라 첨단 PDC 설계에 대한 수요가 증가하고 있습니다. 아르헨티나의 바카 무에르타층은 2030년까지 하루 100만 배럴의 생산을 목표로 하고 있으며, 특수 드릴 비트 조달에 10억 달러 이상을 배정함으로써 비즈니스 기회의 폭을 넓히고 있습니다. AI를 활용한 시추 플랫폼을 통한 생산성 향상은 셰일 분야의 글로벌 드릴 비트 시장 전망을 더욱 강화하고 있습니다.
심해 탐사 및 생산(E&P) 분야의 설비 투자(CAPEX) 증가
심해 분야에 대한 자본 투입으로 인해 하루 40만 달러 이상의 일당을 요구하는 시추 장비의 가동률이 향상되고 있으며, 이에 따라 전 세계 드릴 비트 시장이 확대되고 있습니다. 페트로브라스는 SLB사에 100개 이상의 유정을 대상으로 하는 8억 달러 규모의 통합 계약을 수주했으며, 이는 브라질 프리솔트 지역의 드릴 비트 수요가 매우 높음을 입증하고 있습니다. 셰브론의 ‘앵커’ 프로젝트와 우드사이드의 ‘트리온’ 프로그램에서는 20,000psi의 해저 시스템이 채택되어 커터의 내구성에 대해 매우 높은 요구 사항이 부과되고 있습니다. 앙골라의 카미뇨 FPSO를 포함한 서아프리카의 심해 프로젝트에서는 고성능 드릴 비트가 필요한 저배출형 시추 시스템이 도입되고 있습니다. 이처럼 기술적으로 복잡한 유정 계획이 지속적으로 진행됨에 따라 각 제조사들은 초고압 환경을 견딜 수 있는 열 안정성이 뛰어난 PDC 커터 개발에 주력하고 있습니다.
원유 가격 변동이 시추 장비 수를 억제
브렌트 원유 가격이 배럴당 65-74달러 범위에서 등락하고 있는 것은 탐사 예산을 억제하여 전 세계 드릴비트 시장에 영향을 미치고 있습니다. 베이커 휴즈의 시추 장비 데이터에 따르면 가격이 하락 트리거 수준 아래로 떨어질 때마다 신규 유정 계획이 일시 중단되고 있는 것으로 나타났습니다. 사우디 아람코가 2024년에 20기 이상의 잭업 시추 장비 가동을 중단한 것은 국영 석유 회사가 저유가 환경에서 생산 능력을 어떻게 조정하고 있는지를 여실히 보여줍니다. 독립 생산업체들은 여전히 가격 변동에 특히 민감하여, 수익성이 낮은 광구에 대한 비트 발주를 억제하고 있습니다. 자본 규율로 인해 가격과 시추 장비 가동 수 간의 직접적인 연동성은 약화되고 있지만, 원자재 가격 변동은 여전히 고사양 공구의 조달 주기를 정체시키고 있습니다.
부문별 분석
2025년, 고정 커터 기술은 전 세계 드릴 비트 시장에서 44.30%의 점유율을 차지했습니다. 수요는 이미 전 세계 시추 피트 수의 75-80%를 차지하는 PDC 커터에 집중되어 있으며, 이는 이 등급의 전 세계 드릴 비트 시장 규모를 지원하는 기반이 되고 있습니다. 롤러 콘의 내구성과 다이아몬드의 굴착 속도를 겸비한 하이브리드 비트는 2031년까지 연평균 성장률(CAGR) 8.25%로 성장할 것으로 예상되며, 이는 운영업체들의 싱글 런 솔루션에 대한 수요를 반영한 것입니다.
촉매가 필요 없는 다이아몬드 결합 기술에 대한 실험실에서의 지속적인 발전으로 열적 한계가 확대되어, 과거에는 롤러 콘으로만 제한되었던 지층에서도 PDC 제품을 실용화할 수 있게 되었습니다. NOV와 같은 제조업체들은 PDC 혁신 분야에서 반세기의 역사를 쌓아왔으며, 현재는 AI를 활용한 응력 매핑이 설계 수명주기에 통합되어 있습니다. 그 결과, 전 세계 드릴 비트 시장은 커터 수명 향상으로 인해 비생산 시간이 단축되는 선순환을 누리고 있으며, 이는 효율성과 안전성을 중시하는 운영사의 우선 순위와 부합합니다.
지역별 분석
북미는 첨단 셰일용 설계와 멕시코만에서의 지속적인 개발로 인해 2025년 세계 드릴 비트 시장에서 36.40%의 점유율을 유지했습니다. AI를 활용한 시추로 평균 천공 속도가 30% 향상되어 고가 비트에 대한 투자 회수가 가속화되었습니다. 캐나다의 오일샌드 개발과 멕시코의 트리온(Trion) 초심해 프로젝트가 수요를 더욱 끌어올리며, 해당 지역의 규모 우위를 강화하고 있습니다.
아시아태평양은 세계 드릴 비트 시장에서 가장 빠르게 성장하는 시장으로, 2031년까지 연평균 성장률(CAGR) 7.65%를 기록하고 있습니다. 중국은 육상 시추 장비 대수에서 1위를 차지하고 있으며, 인도는 시추 장비 대수를 2024년 111대에서 2028년까지 142대로 늘릴 계획입니다. 이러한 움직임으로 인해 드릴 비트 조달 수요가 확대되고 있습니다. 2025년에 3,000억 달러를 넘어설 것으로 예상되는 해양 설비 투자(특히 중국 해역에서의 투자)로 인해 중요 금속 및 합성 다이아몬드의 지역 공급망에 긴장이 발생하고 있습니다.
중동 및 아프리카에서는 수요 동향이 제각각이지만, 매우 중요한 역할을 하고 있습니다. ADNOC Drilling사는 두 자릿수의 매출 성장을 기록하고 있지만, 사우디아라비아에서 시추 장비 가동 중단으로 인해 가동률 지표는 둔화되고 있습니다. 서아프리카의 심해 프로젝트가 초고압 비트 수요를 견인하는 한편, 유럽의 지열 개발 사업은 북해에서의 수요 감소 일부를 상쇄하는 역할을 하고 있습니다. 남미의 바카 무에르타 프로젝트는 지난 10년 동안 최대 규모의 비전통 자원 개발 프로젝트 중 하나로, 해당 반구에서 세계 드릴 비트 시장의 입지를 확대하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.08.25According to Mordor Intelligence, drill bit market size in 2026 is estimated at USD 6.5 billion, growing from 2025 value of USD 6.14 billion with 2031 projections showing USD 8.64 billion, growing at 5.86% CAGR over 2026-2031.
This report is Segmented by Type (Roller-Cone Bits, Fixed-Cutter Bits, Hybrid Bits, and Specialty Bits), Location of Deployment (Onshore and Offshore), Application (Oil and Gas, Mining, Geothermal, and Water-Well and Civil Construction), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Drill Bit Market Trends and Insights
Shale Gas Revival in North America
Shale output momentum lifts the Global Drill Bit market as U.S. natural-gas production is set to rise from 7.2 trillion cubic feet in 2025 toward 8.8 trillion cubic feet by 2050. Robust LNG export plans keep rig demand high, with the Permian Basin hosting 60% of U.S. onshore rigs. Longer laterals that exceed 20,000 feet in single runs foster demand for advanced PDC designs. Argentina's Vaca Muerta formation broadens the opportunity pool, targeting 1 million barrels per day by 2030 and allocating more than USD 1 billion for specialised bit procurement. Productivity gains stemming from AI-enabled drilling platforms further strengthen the Global Drill Bit market outlook within shale domains.
Deep-Water E&P CAPEX Upswing
Capital commitments for deepwater are improving the utilisation of rigs that command day rates above USD 400,000, thereby expanding the Global Drill Bit market. Petrobras awarded SLB a USD 800 million integrated contract covering more than 100 wells, underlining strong bit demand in Brazil's pre-salt cluster. Chevron's Anchor project and Woodside's Trion programme rely on 20,000 psi subsea systems that place premium requirements on cutter resilience. West Africa's deep-water projects, including Angola's Kaminho FPSO, are adopting low-emission drilling systems that require high-performance bits. This sustained pipeline of technically complex wells is pushing manufacturers to innovate thermal-stable PDC cutters that can endure ultra-high-pressure conditions.
Oil-Price Volatility Curbing Rig Counts
A Brent range of USD 65-74 per barrel tempers exploration budgets and sways the Global Drill Bit market. Baker Hughes rig data show pauses in new-well programs whenever prices breach downside triggers. Saudi Aramco's 2024 suspension of more than 20 jackups illustrates how national oil companies adjust their capacity in low-price environments. Independent producers remain especially price sensitive, curbing bit orders for marginal acreage. Even as capital discipline lessens the direct linkage between price and rig activity, commodity swings still stall procurement cycles for high-specification tools.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Switch to PDC Bits for Higher ROP
- Geothermal Well Drilling Incentives
- Stricter Environment & Flaring Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed-cutter technology held 44.30% of the Global Drill Bit market in 2025. Demand gravitates to PDC cutters that already drill 75-80% of worldwide footage, anchoring the Global Drill Bit market size for this class. Hybrid bits, which combine the durability of roller cones with the speed of diamonds, are projected to grow at an 8.25% CAGR through 2031, reflecting operator demand for single-run solutions.
Continued laboratory gains in catalyst-free diamond bonding have stretched thermal limits, making PDC products viable in formations once restricted to roller cones. Manufacturers such as NOV mark half a century of PDC innovation, pointing to design lifecycles that now incorporate AI-driven stress mapping. As a result, the Global Drill Bit market enjoys a virtuous cycle whereby improved cutter life reduces non-productive time, echoing operator priorities for efficiency and safety.
Complete Report Scope:
- By Type
- Roller-Cone Bits
- Fixed-Cutter Bits
- Hybrid Bits
- Specialty Bits (Core, Reaming)
- By Location of Deployment
- Onshore
- Offshore
- By Application
- Oil and Gas
- Mining
- Geothermal
- Water-Well and Civil Construction
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Norway
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Egypt
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 36.40% of the Global Drill Bit market in 2025, owing to advanced shale designs and ongoing developments in the Gulf of Mexico. AI-guided drilling increased average penetration rates by 30%, resulting in rapid paybacks on premium bits. Canadian oil-sands activity and Mexico's Trion ultra-deepwater campaign add incremental demand, reinforcing the region's scale advantage.
The Asia-Pacific region represents the fastest-growing market for the Global Drill Bit market, posting an 7.65% CAGR through 2031. China leads land-rig counts, while India plans to lift its fleet from 111 units in 2024 to 142 by 2028, moves that swell bit procurement pipelines. Offshore CAPEX that exceeds USD 300 billion in 2025, particularly in Chinese waters, tightens regional supply chains for critical metals and synthetic diamonds.
The Middle East and Africa deliver mixed but pivotal demand. ADNOC Drilling records double-digit revenue growth, yet Saudi rig suspensions temper utilisation metrics. West African deep-water projects drive demand for ultra-high-pressure bits, while Europe's geothermal initiatives help offset some of the decline in the North Sea. South America's Vaca Muerta programme offers one of the decade's largest unconventional prospects, enlarging the Global Drill Bit market footprint across the hemisphere.
- Schlumberger Ltd (Smith Bits)
- Halliburton Co. (Security DBS)
- Baker Hughes Co.
- National Oilwell Varco Inc.
- Varel Energy Solutions
- Sandvik AB
- Ulterra Drilling Technologies
- Rockpecker Ltd
- Xi'an Landrill Oil Tools
- Epiroc AB
- Atlas Copco AB
- Drill Master International
- Torquato Drilling Accessories
- PDB Tools Inc.
- Kingdream Public Ltd Co.
- Sichuan Chuanshi Diamond Bits
- NewTech Drilling Products
- Cougar Drilling Solutions
- Baker SPD (specialty)
- Taurex Drill Bits
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shale gas revival in North America
- 4.2.2 Deep-water E&P CAPEX upswing
- 4.2.3 Rapid switch to PDC bits for higher ROP
- 4.2.4 Geothermal well drilling incentives
- 4.2.5 Nascent natural-hydrogen exploration demand
- 4.2.6 Digital-twin-optimised bit design adoption
- 4.3 Market Restraints
- 4.3.1 Oil-price volatility curbing rig counts
- 4.3.2 Stricter environment & flaring rules
- 4.3.3 Synthetic-diamond supply-chain risk
- 4.3.4 Re-manufactured bit cannibalisation
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Roller-Cone Bits
- 5.1.2 Fixed-Cutter Bits
- 5.1.3 Hybrid Bits
- 5.1.4 Specialty Bits (Core, Reaming)
- 5.2 By Location of Deployment
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Application
- 5.3.1 Oil and Gas
- 5.3.2 Mining
- 5.3.3 Geothermal
- 5.3.4 Water-Well and Civil Construction
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Norway
- 5.4.2.6 Russia
- 5.4.2.7 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Egypt
- 5.4.5.6 Nigeria
- 5.4.5.7 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Schlumberger Ltd (Smith Bits)
- 6.4.2 Halliburton Co. (Security DBS)
- 6.4.3 Baker Hughes Co.
- 6.4.4 National Oilwell Varco Inc.
- 6.4.5 Varel Energy Solutions
- 6.4.6 Sandvik AB
- 6.4.7 Ulterra Drilling Technologies
- 6.4.8 Rockpecker Ltd
- 6.4.9 Xi'an Landrill Oil Tools
- 6.4.10 Epiroc AB
- 6.4.11 Atlas Copco AB
- 6.4.12 Drill Master International
- 6.4.13 Torquato Drilling Accessories
- 6.4.14 PDB Tools Inc.
- 6.4.15 Kingdream Public Ltd Co.
- 6.4.16 Sichuan Chuanshi Diamond Bits
- 6.4.17 NewTech Drilling Products
- 6.4.18 Cougar Drilling Solutions
- 6.4.19 Baker SPD (specialty)
- 6.4.20 Taurex Drill Bits
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment