|
시장보고서
상품코드
2114044
코골이 치료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Anti-Snoring Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
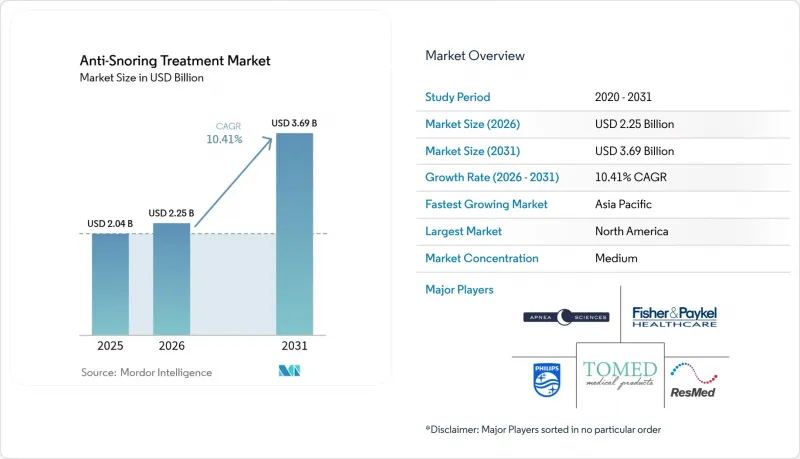
에 의하면, 코골이 치료 시장 규모는 2025년에 20억 4,000만 달러로 평가되었습니다. 2026년 22억 5,000만 달러에서 2031년까지 36억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 10.41%를 나타낼 전망입니다.
본 보고서는 기기 유형(하악 전돌 장치(MAD) 등), 외과적 시술(구개수-구개인두 성형술(UPPP),솜노플라스티 등), 최종 사용자(재택 간호 환경 등), 유통 채널(오프라인 및 온라인), 기술(커넥티드 기기 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 코골이 치료 시장 동향 및 인사이트
비만 및 고령층의 급속한 증가
비만 유병률의 급증은 노화에 따른 생리적 변화와 맞물려 폐쇄성 수면 무호흡증(OSA)의 발생률을 높이고 있습니다. BMI가 30 kg/m2를 초과할 때마다 무호흡 및 저호흡의 중증도가 가속화되는 한편, 고령자의 경우 인두근의 긴장이 저하되어 기도가 폐쇄될 위험이 높아집니다. 미국의 모델 분석에 따르면, 2025-2030년 성인의 OSA 유병률은 26.7% 증가할 것으로 예측되며, 이에 따라 이차적인 심혈관 질환으로 인한 비용을 최소화하는 조기 개입법에 대한 수요가 높아지고 있습니다.
가정 수면 검사를 통한 경증 OSA 진단율 상승
FDA 승인을 받은 58종의 재택 검사 기기로 인해 진단 장벽이 낮아지고 있으며, 승인 건수의 84.5%를 유형 3 모니터가 차지하고 있습니다. 시설 내 수면 다원검사보다 20-30% 저렴한 가정용 검사를 통해, CPAP 사용을 피하는 경우가 많은 경증 OSA 사례가 밝혀지면서, 임상의들은 구강 내 장치나 체위 관리용 웨어러블 기기에 대한 대응을 요구받고 있습니다.
맞춤형 3D 프린팅 구강 내 장치의 높은 가격
맞춤형 장치는 인상 채취 및 사후 관리 비용을 제외하더라도 1,500달러를 초과하는 경우가 많으며, 총 본인 부담금이 4,000달러를 넘기 때문에 중산층 시장에서의 보급을 저해하고 있습니다. 재료비, 프린터 비용 및 후처리 비용이 여전히 규모의 경제를 저해하고 있습니다.
부문 분석
하악 전돌 장치는 2025년 코골이 치료 시장에서 39.02%의 점유율을 유지한 반면, 스마트 웨어러블 및 자세 교정 기구는 13.92%의 연평균 성장률(CAGR)을 기록하며 디지털화로의 전환을 반영하고 있습니다. 지속적 기도 양압(CPAP) 장치는 여전히 중증 수면 무호흡증(OSA)의 표준 치료법이지만, 착용감이 좋지 않아 대체 제품을 찾는 수요가 여전히 상당수 존재합니다. 호기 PAP 밸브와 비강 확장기는 최소한의 기류로 충분한 보조 기구에 대한 수요를 충족시키고 있으며, 혀 고정 기구는 해부학적으로 특화된 틈새 시장을 공략하고 있습니다.
혁신의 흐름은 커넥티드형 제품으로 기울고 있습니다. 스마트 MAD(구강 내 장치)에는 야간 혀 돌출 억제 효과를 검증하고 클라우드 분석 데이터를 전송하는 센서가 탑재되어 있어, 치료 순응도 루프를 강화하고 있습니다. 연결형 구강 내 기기를 활용한 코골이 치료 시장 규모는 OTC(일반의약품) 정책의 호재를 배경으로, 2025년 4억 1,000만 달러에서 연평균 성장률(CAGR) 12.63%로 확대되었습니다. 한편, 코골이 치료 업계에서는 범용 턱 밴드의 포기율이 여전히 높기 때문에 고객 유지를 위한 핵심 요소로서 디자인 및 소재 개선이 주목받고 있습니다.
2025년 시점에서 구개수·구개·인두 성형술은 외과 수술 시장 점유율의 30.12%를 차지했으나, 설하 신경 자극 요법의 향후 연평균 성장률(CAGR)이 13.53%로 예측됨에 따라, 기기를 이용한 신경 조절 요법에 대한 선호도가 높아지고 있음을 시사합니다. 솜노플라스틱 및 고주파 구개 성형술은 합병증 위험이 낮은 조직 절제술을 제공하는 반면, 필라 시술은 저침습적 구개 강화라는 틈새 시장을 채우고 있습니다.
신경 자극 요법의 높은 가격대(3만-4만 달러)는 시술 건수를 제한하는 반면, CPAP 불내성이 확인된 특정 시장에서는 보험 환급이 보장되고 있습니다. 신경 자극 요법을 통한 코골이 치료 시장 규모는 2031년까지 5억 7,500만 달러에 달할 것으로 예측되며, 보험사의 정책과의 조화가 중요시되고 있습니다. 보급의 핵심은 수년에 걸친 유효성에 대한 추가적인 입증과 외래에서 이루어지는 간소화된 이식 수술입니다.
지역별 분석
북미는 종합적인 보험 급여, 기업의 웰니스 이니셔티브, 그리고 AI가 탑재된 웨어러블 기기의 조기 도입에 힘입어 2025년 시장 점유율 41.44%로 1위를 차지했습니다. 보험사들은 현재 입증된 치료 순응도에 따라 보험료 할인을 적용하는 가치 기반 지불 번들을 시범적으로 도입하고 있으며, 이로 인해 기기 교체 주기가 촉진되고 있습니다. 그러나 CPAP 중단률이 높기 때문에 임상의들은 다중 모드 치료 프로토콜을 채택하는 경향을 보이고 있어 수요의 다양성이 유지되고 있습니다.
아시아태평양은 인구 급증에 가처분 소득 증가 및 민간 보험 확대가 맞물려 11.52%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 중국만 해도 1억 7,600만 명의 OSA 환자가 존재함에도 불구하고, CPAP 보급률은 고작 10.25%에 그치고 있어, 저비용 구강 내 장치나 앱 기반 진단법에 잠재적인 시장 규모가 있음을 여실히 보여주고 있습니다. 공중보건 캠페인을 통해 뿌리 깊은 문화적 오해를 해소하기 위해 노력하고 있습니다. 인도의 ‘Stop the Snore’ 이니셔티브는 이비인후과학회와 제휴하여 선별 검사의 보급을 추진하고 있습니다.
유럽은 여전히 보다 안정적이고 프로토콜 중심의 환경을 유지하고 있습니다. 조화된 CE 마킹으로 인해 커넥티드 기기의 확산이 가속화되고 있는 반면, 건강보험에 의한 환급 제도가 도입 곡선을 안정화시키고 있습니다. 중동 및 아프리카 및 남미는 낮은 수준에서 성장을 지속하고 있습니다. 걸프 지역 국가들에서는 전문 수면 센터에 대한 투자가 진행되고 있는 반면, 브라질에서는 원격의료법 개정에 따라 원격 MAD(구강 내 장치) 처방 및 제공이 촉진되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the anti-snoring treatment market size was valued at USD 2.04 billion in 2025 and estimated to grow from USD 2.25 billion in 2026 to reach USD 3.69 billion by 2031, at a CAGR of 10.41% during the forecast period (2026-2031).
This report is Segmented by Device Type (Mandibular Advancement Devices (MAD), and More), Surgical Intervention (Uvulopalatopharyngoplasty (UPPP), Somnoplasty, and More), End-User (Home-Care Settings, and More), Distribution Channel (Offline and Online), Technology (Connected Devices, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Anti-Snoring Treatment Market Trends and Insights
Rapid Growth of Obesity & Geriatric Cohorts
Escalating obesity prevalence intersects with aging physiology to magnify obstructive sleep apnea (OSA) incidence. Each BMI unit above 30 kg/m2 accelerates apnea-hypopnea severity, while declining pharyngeal muscle tone in older adults raises airway collapsibility. U.S. modeling indicates a 26.7% increase in adult OSA prevalence between 2025 and 2030, amplifying demand for early intervention modalities that minimize downstream cardiovascular costs.
Rising Diagnosis Rates of Mild OSA via Home-Sleep Testing
Fifty-eight FDA-cleared home testing devices have lowered diagnostic barriers, with Type-3 monitors making up 84.5% of approvals. At 20-30% lower cost than lab polysomnography, home tests surface mild OSA cases that often eschew CPAP, steering clinicians toward oral appliances and positional wearables.
High Price of Custom 3-D Printed Oral Appliances
Custom devices frequently exceed USD 1,500 before impression and follow-up fees, driving total out-of-pocket cost past USD 4,000 and curbing adoption in middle-income markets. Material, printer, and post-curing expenses still prevent scale economies.
Other drivers and restraints analyzed in the detailed report include:
- Acceleration of E-Commerce DTC Sales for OTC Devices
- FDA-Cleared OTC MADs Shortening Rx-to-Therapy Cycle
- Low Long-Term Adherence to CPAP & Chin-Straps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mandibular advancement devices retained 39.02% 2025 anti-snoring treatment market share, while smart wearables and positional trainers chart a 13.92% CAGR, reflecting the digital pivot. Continuous Positive Airway Pressure units remain the reference for severe OSA, yet their comfort gap sustains a sizable pool for alternatives. Expiratory PAP valves and nasal dilators answer demand for minimalist airflow aids, and tongue-stabilizing tools serve anatomically specific niches.
Innovation momentum skews toward connected formats. Smart MADs layer sensors that validate nightly protrusion efficacy and transmit cloud analytics, reinforcing compliance loops. The anti-snoring treatment market size for connected oral devices is forecast to expand at 12.63% CAGR from USD 410 million in 2025, underpinned by OTC policy tailwinds. Conversely, the anti-snoring treatment industry still sees high abandonment of generic chin-straps, spotlighting design and materials upgrades as a retention lever.
Uvulopalatopharyngoplasty held 30.12% surgical share in 2025, but hypoglossal nerve stimulation's 13.53% future CAGR signals growing preference for device-guided neuromodulation. Somnoplasty and radio-frequency palatoplasty offer tissue-reduction routes with lower morbidity, while the pillar procedure fills the minimally invasive palate-stiffening niche.
Neuro-stimulation's premium price bracket (USD 30,000-40,000) restricts volume yet secures reimbursement in select markets where CPAP intolerance is documented. The anti-snoring treatment market size for nerve stimulation is forecast to reach USD 575 million by 2031, emphasizing payer-policy alignment. Viral adoption hinges on further evidence of multi-year efficacy and streamlined outpatient implantation.
Complete Report Scope:
- By Device Type
- Mandibular Advancement Devices (MAD)
- Tongue Stabilizing Devices (TSD)
- Continuous Positive Airway Pressure (CPAP) Devices
- Expiratory PAP (EPAP) & Nasal Dilators
- Smart Wearables & Positional Trainers
- Other Devices
- By Surgical Intervention
- Uvulopalatopharyngoplasty (UPPP)
- Somnoplasty
- Pillar Procedure
- Tonsillectomy & Adenoidectomy
- Radio-frequency Palatoplasty
- Hypoglossal Nerve Stimulation
- Laser-Assisted Uvuloplasty
- Others
- By End-user
- Home-care Settings
- Hospitals & Sleep Labs
- Dental & ENT Clinics
- By Distribution Channel
- Offline (Hospital/Retail Pharmacies)
- Online (E-commerce, DTC, Marketplaces)
- By Technology
- Connected / App-enabled Devices
- Non-connected Conventional Devices
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 41.44% 2025 share thanks to comprehensive reimbursement, enterprise wellness initiatives, and early uptake of AI-enhanced wearables. Insurers now pilot value-based payment bundles that tie premium discounts to demonstrated adherence, reinforcing device replacement cycles. Yet CPAP drop-off rates push clinicians toward multimodal protocols, sustaining demand diversity.
Asia-Pacific posts the fastest 11.52% CAGR as demographic bulges meet rising disposable income and expanding private insurance. China alone counts 176 million OSA sufferers but only 10.25% CPAP penetration, spotlighting latent volume for lower-cost oral appliances and app-based diagnostics. Public-health campaigns now tackle entrenched cultural misperceptions; India's "Stop the Snore" initiative partners with ENT societies to normalize screening.
Europe remains a steadier, protocol-driven environment. Harmonized CE marking accelerates connected-device rollouts, while sickness-fund reimbursement stabilizes adoption curves. Middle East & Africa and South America advance from low bases; gulf states invest in specialty sleep centers, whereas Brazil's telemedicine law revisions aid remote MAD dispensing.
- Resmed
- Koninklijke Philips
- Fisher & Paykel Healthcare
- SomnoMed
- Apnea Sciences
- Whole You (Mitsui Chemicals)
- Tomed GmbH
- The Pure Sleep Company
- Signifier Medical Technologies
- ZQuiet (Sleeping Well LLC)
- Smart Nora
- Bleep LLC
- Good Sleep Co
- Rotech Healthcare
- Innovative Health
- Lear Corp (AccuMED)
- Meditas
- GlaxoSmithKline
- SnoreMeds (Pty) Ltd
- Tongue Lab
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth of Obesity & Geriatric Cohorts
- 4.2.2 Rising Diagnosis Rates of Mild OSA Via Home-Sleep Testing
- 4.2.3 Acceleration of E-Commerce DTC Sales For OTC Devices (Subscription Bundles)
- 4.2.4 FDA-Cleared OTC Mads Shortening Rx-To-Therapy Cycle
- 4.2.5 Smart, App-Linked Positional & Acoustic Wearables (AI Coaching)
- 4.2.6 Corporate Sleep-Health Programmes Lowering Insurance Premiums
- 4.3 Market Restraints
- 4.3.1 High Price Of Custom 3-D Printed Oral Appliances
- 4.3.2 Low Long-Term Adherence To CPAP & Chin-Straps
- 4.3.3 Fragmented Regulatory Pathways For Wellness Devices
- 4.3.4 Social Stigma In Emerging Markets Limiting Care-Seeking
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Device Type
- 5.1.1 Mandibular Advancement Devices (MAD)
- 5.1.2 Tongue Stabilizing Devices (TSD)
- 5.1.3 Continuous Positive Airway Pressure (CPAP) Devices
- 5.1.4 Expiratory PAP (EPAP) & Nasal Dilators
- 5.1.5 Smart Wearables & Positional Trainers
- 5.1.6 Other Devices
- 5.2 By Surgical Intervention
- 5.2.1 Uvulopalatopharyngoplasty (UPPP)
- 5.2.2 Somnoplasty
- 5.2.3 Pillar Procedure
- 5.2.4 Tonsillectomy & Adenoidectomy
- 5.2.5 Radio-frequency Palatoplasty
- 5.2.6 Hypoglossal Nerve Stimulation
- 5.2.7 Laser-Assisted Uvuloplasty
- 5.2.8 Others
- 5.3 By End-user
- 5.3.1 Home-care Settings
- 5.3.2 Hospitals & Sleep Labs
- 5.3.3 Dental & ENT Clinics
- 5.4 By Distribution Channel
- 5.4.1 Offline (Hospital/Retail Pharmacies)
- 5.4.2 Online (E-commerce, DTC, Marketplaces)
- 5.5 By Technology
- 5.5.1 Connected / App-enabled Devices
- 5.5.2 Non-connected Conventional Devices
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 ResMed
- 6.3.2 Koninklijke Philips N.V.
- 6.3.3 Fisher & Paykel Healthcare
- 6.3.4 SomnoMed
- 6.3.5 Apnea Sciences
- 6.3.6 Whole You (Mitsui Chemicals)
- 6.3.7 Tomed GmbH
- 6.3.8 The Pure Sleep Company
- 6.3.9 Signifier Medical Technologies
- 6.3.10 ZQuiet (Sleeping Well LLC)
- 6.3.11 Smart Nora
- 6.3.12 Bleep LLC
- 6.3.13 Good Sleep Co
- 6.3.14 Rotech Healthcare
- 6.3.15 Innovative Health Technologies
- 6.3.16 Lear Corp (AccuMED)
- 6.3.17 Meditas
- 6.3.18 GSK plc
- 6.3.19 SnoreMeds (Pty) Ltd
- 6.3.20 Tongue Lab
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment