

|
시장보고서
상품코드
2114119
개 관절염 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Canine Arthritis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 개 관절염 시장 규모는 2025년 34억 3,000만 달러로 평가되었고, 2026년에는 36억 3,000만 달러로 추정되고, 2026-2031년 CAGR 5.96%로 성장을 지속할 전망이며, 2031년에는 48억 5,000만 달러에 이를 것으로 예측됩니다.
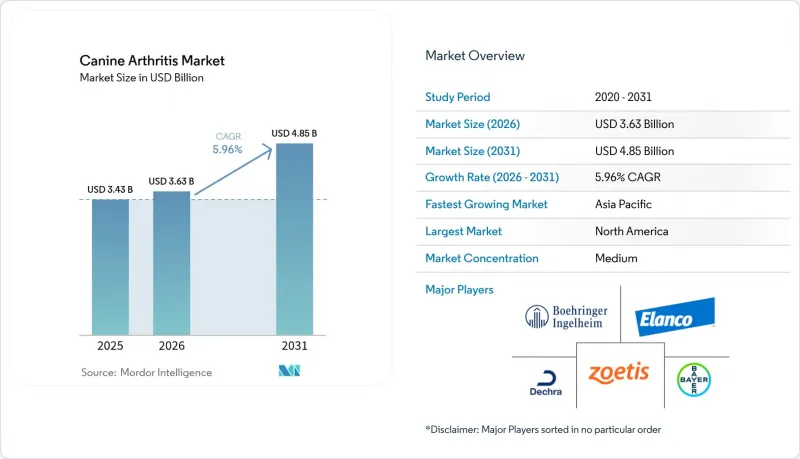
본 보고서는 제품 유형별(치료제 유형, 진단법), 질병 단계별(전임상 단계/등급 0-1, 경증/등급 2, 중등도/등급 3, 중증/등급 4), 반려견 크기별(소형, 중형, 대형, 초대형), 연령별(어린 개, 성견, 노령견), 최종 사용자별(동물병원 및 전문 클리닉 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 개 관절염 시장 동향 및 인사이트
반려견의 비만 및 운동으로 인한 부상 유병률 증가
2024년 기준, 미국 반려견의 59%가 과체중이거나 비만이며, 이는 체중을 지탱하는 관절 연골의 마모를 가속화하는 생체역학적 부담이 되고 있습니다. 영국에서 실시된 유사한 조사에 따르면 비만율이 50%로 나타났으며, 과체중 개의 경우 8세 미만의 퇴행성 관절염 진단이 2.8배 증가하는 것으로 밝혀졌습니다. 과도한 지방은 인터루킨-6과 같은 전신성 사이토카인을 증가시키고, 활액의 점도를 낮춥니다. 애질리티 경기나 딱딱한 노면이 많은 도시 지역에서의 운동은 작업견 품종의 관절 외상을 더욱 악화시킵니다. 현재 미국 가구의 67%가 반려동물을 기르고 있으며, 약 3,800만 마리의 개가 관절염 위험에 노출되어 있습니다. 이러한 인구통계학적 압박으로 인해, 돌이킬 수 없는 손상이 발생하기 전에 염증을 치료하고 조기 진단 및 체중 관리를 위한 영양 보조제에 대한 수요가 지속되고 있습니다.
반려동물의 고령화와 ‘반려동물의 인간화’ 동향
2024년, 미국 개들의 연령 중앙값은 6.2세에 달했으며, 이는 영양 상태의 개선과 예방 의료의 발전을 반영합니다. 관절염 환자의 58.38%를 이미 고령견이 차지하고 있으며, 반려인들은 반려견을 점점 더 가족의 일원으로 대하고 있어 2024년에는 1마리당 1,543달러를 수의학 치료비로 지출하고 있습니다. Z세대 반려인들은 과거에는 경기용 동물에게만 시행되던 혈소판 농축 혈장 요법이나 수처리 요법에 가처분 소득을 투자하고 있습니다. 일본에서는 38%의 가구가 반려견에 보험을 가입하고 있으며, 예방적 장수 관리 문화가 정착되고 있습니다. 이러한 투자 의지가 개 관절염 치료 및 진단 시장에서 질병 수정 요법과 재생 의학의 꾸준한 보급을 뒷받침하고 있습니다.
장기적인 진통 요법 및 생물학적 제제 요법의 높은 평생 비용
단일클론 항체의 월 1회 주사 비용은 80-120달러이며, 8세에 진단을 받은 개의 경우 평생 비용은 3,000달러를 초과합니다. 자가 줄기세포 치료 1주기는 2,500-4,500달러가 들기 때문에 그 이용은 경제적으로 여유가 있는 반려인에게만 국한되어 있습니다. 제네릭 NSAID는 여전히 저렴하지만, 무기한 투여와 빈번한 모니터링이 필요합니다. 보험 보급률이 낮은 지역에서는 비용이 주요 장벽이 되어, 반려견 관절염 치료 및 진단 시장의 확장을 억제하고 있습니다.
부문 분석
2025년 매출의 75.58%를 치료제군이 차지했으며, 개 관절염 치료·진단 시장에서 약물 요법에 대한 의존도가 높다는 점이 두드러지게 나타납니다. NSAID는 여전히 일상적인 통증 관리의 기반을 이루고 있지만, 베딘베토맙(bedinbetumab)과 같은 신경 성장 인자 단일클론 항체는 미국에서 첫해 매출 1억 2,000만 달러를 기록하며, 임상의들에 의한 빠른 채택이 진행되고 있음을 보여줍니다. 폴리설페이트화 글리코사미노글리칸과 같은 질병 수정 약물은 질병의 초기 단계에서 치료 선택지를 확대되고 있습니다.
진단 분야는 시장 규모는 작지만, X선 확인 이전에 조직의 퇴화를 감지하는 AI 레지오믹스 및 바이오마커 검사에 힘입어 연평균 성장률(CAGR) 6.78%로 성장하고 있습니다. 구독형 분석 플랫폼은 전문 병원 이외의 이용을 확대하고 새로운 접점을 창출함으로써, 개 관절염 치료·진단 시장 규모를 확대되고 있습니다.
2025년에도 중등도 관절염이 전체 사례의 33.89%를 차지하는 가장 큰 코호트로 남아 있을 것이며, 이는 반려인이 운동 기능 저하를 처음 인지하는 시기와 일치합니다. 중증인 4등급 질환의 경우, 다각적인 진통 요법을 시행하더라도 안락사를 고려해야 하는 경우가 종종 있습니다.
대조적으로, 전임상 단계 및 0-1등급의 사례는 건강 검진에서 라디오믹스 및 포스플레이트를 이용한 선별 검사가 일상화됨에 따라 연평균 성장률(CAGR) 7.01%로 확대되고 있습니다. 질환 수식제를 통한 조기 개입은 연골을 보호하고 고액의 수술을 미루게 합니다. 이러한 변화는 기술이 개 관절염 치료 및 진단 시장의 초기 단계에 어떻게 수익을 창출하고 있는지를 보여줍니다.
지역별 분석
북미는 2025년 매출의 34.88%를 차지했습니다. 미국의 수의학 치료비는 개 1마리당 평균 1,500달러이며, 관절염을 앓고 있는 개의 22%가 ‘리브렐라(Librela)’ 출시 후 12개월 이내에 단일클론 항체 주사를 맞은 것으로 나타나, 생물학적 제제의 보급이 진행되고 있음을 보여줍니다. 캐나다에서는 각 주에서 영상 진단에 대한 보험 우대 조치를 시행함에 따라 조기 진단률이 더욱 향상되고 있습니다. 한편, 멕시코에서는 신흥 중산층이 가격에 민감하기 때문에 바이오의약품의 보급은 둔화되고 있지만, 제네릭 NSAID의 판매는 활성화되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 9.88%로 가장 빠르게 성장하고 있는 지역입니다. 중국의 반려동물 시장은 2024년에 1,300억 위안(182억 달러)에 달할 전망이며, 밀레니얼 세대 반려인들은 예방 의학을 중시하고 있습니다. 일본의 경우, 보험 보급률이 높고 호스피스 서비스가 잘 갖춰져 있어 시장의 성숙도를 엿볼 수 있습니다. 인도 및 동남아시아 국가에서는 수의학용 생물학적 제제의 수입 규제가 완화되고 있으며, 이러한 정책 변화로 인해 개의 관절염 치료 및 진단 시장의 성장이 가속화될 것으로 예측됩니다.
유럽은 2025년 매출의 27.62%를 차지했습니다. 독일과 프랑스에서는 전체론적인 보조 요법이 선호되는 반면, 영국에서는 25%의 보험 보급률로 인해 재활 요법에 대한 수요가 증가하고 있습니다. EMA(유럽의약품청)의 바이오시밀러 집중 심사 절차는 가격 경쟁과 더 광범위한 접근성 확보를 가져올 것으로 기대됩니다. 남미 및 중동과 같은 신흥 지역은 현재 시장 규모는 작지만, 가처분 소득 증가와 수입 치료제의 접근성 개선에 힘입어 두 자릿수 성장 곡선을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.26According to Mordor Intelligence, the canine arthritis market size is expected to grow from USD 3.43 billion in 2025 to USD 3.63 billion in 2026 and is forecast to reach USD 4.85 billion by 2031 at 5.96% CAGR over 2026-2031.
This report is Segmented by Product Type (Therapeutic Drug Class, Diagnostic Modality), Disease Stage (Pre-clinical/Grade 0-1, Mild/Grade 2, Moderate/Grade 3, Severe/Grade 4), Dog Size (Small, Medium, Large, Giant), Age Group (Juvenile, Adult, Senior), End User (Veterinary Hospitals & Specialty Clinics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Canine Arthritis Market Trends and Insights
High Prevalence of Canine Obesity and Motion Injuries
Fifty-nine percent of U.S. dogs were overweight or obese in 2024, a biomechanical burden that accelerates cartilage wear in weight-bearing joints. Comparable surveys in the United Kingdom found a 50% obesity rate and a 2.8-fold rise in osteoarthritis diagnoses before age 8 among overweight dogs. Excess adiposity elevates systemic cytokines such as interleukin-6, eroding synovial viscosity. Agility sports and hard-surface urban exercise further compound joint trauma in working breeds. With 67% of U.S. households now owning pets, roughly 38 million dogs carry elevated arthritis risk. This demographic pressure sustains demand for early diagnostics and weight-management nutraceuticals that address inflammation before irreversible damage occurs.
Aging Pet Population and Pet-Humanization Trend
The median age of U.S. dogs climbed to 6.2 years in 2024, reflecting better nutrition and preventive medicine. Senior dogs already comprise 58.38% of arthritis patients, and owners increasingly treat them as family members, spending USD 1,543 per dog on veterinary care in 2024. Generation Z pet parents allocate discretionary income to platelet-rich plasma and hydrotherapy once reserved for performance animals. In Japan, 38% of households insure canine companions, reinforcing a culture of proactive longevity care. This willingness to invest underpins steady uptake of disease-modifying and regenerative therapies within the canine arthritis treatment and diagnostics market.
High Lifetime Cost of Long-Term Analgesic and Biologic Therapy
Monthly monoclonal antibody injections cost USD 80-120, pushing lifetime expense beyond USD 3,000 for dogs diagnosed at age 8. Autologous stem-cell cycles run USD 2,500-4,500, limiting uptake to affluent owners. Generic NSAIDs remain cheaper but require indefinite dosing and frequent monitoring. Where insurance penetration is low, cost becomes a primary barrier that tempers expansion of the canine arthritis treatment and diagnostics market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Penetration of Pet Insurance and Veterinary Spend
- Regulatory Fast-Track for Veterinary Monoclonal Antibodies
- NSAID-Related Safety Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Therapeutic classes controlled 75.58% of 2025 revenue, underscoring pharmacologic reliance in the canine arthritis treatment and diagnostics market. NSAIDs still underpin daily pain control, yet nerve-growth-factor monoclonal antibodies such as bedinvetmab recorded USD 120 million in first-year U.S. sales, signifying rapid clinician adoption. Disease-modifying agents like polysulfated glycosaminoglycans enlarge the toolbox for early-stage disease.
Diagnostics accounted for a smaller base but are growing at 6.78% CAGR, buoyed by AI radiomics and biomarker assays that spot degradation before radiographic confirmation. Subscription analytics platforms expand usage beyond specialty hospitals, creating new touchpoints that enlarge the canine arthritis treatment and diagnostics market size.
Moderate arthritis remained the largest cohort at 33.89% of cases in 2025, aligning with the first point when owners notice mobility decline. Severe Grade 4 disease often forces euthanasia discussions despite multimodal analgesia.
In contrast, pre-clinical and Grade 0-1 cases are expanding at 7.01% CAGR as radiomics and force-plate screens become routine in wellness visits. Early intervention with disease-modifying drugs preserves cartilage and delays costly surgery. This shift shows how technology is pulling revenue into the front end of the canine arthritis treatment and diagnostics market.
Complete Report Scope:
- By Product Type
- Therapeutic Drug Class
- NSAIDs
- Monoclonal Antibodies
- Nutraceutical Supplements
- Disease-Modifying OA Drugs (DMOADs)
- Autologous Cell & Gene Therapies
- Others
- Diagnostic Modality
- Physical Examination / Palpation
- Radiography (X-ray)
- Advanced Imaging (CT / MRI / Ultrasound)
- Force-plate & Gait-analysis Wearables
- Biomarker Panels (Serum / Synovial Fluid)
- Therapeutic Drug Class
- By Disease Stage
- Pre-clinical / Grade 0-1
- Mild / Grade 2
- Moderate / Grade 3
- Severe / Grade 4
- By Dog Size
- Small (Less than 10 kg)
- Medium (10-25 kg)
- Large (25-40 kg)
- Giant (More Than 40 kg)
- By Age Group
- Juvenile (Less Than 1 yr)
- Adult (1-7 yrs)
- Senior (More Than 7 yrs)
- By End User
- Veterinary Hospitals & Specialty Clinics
- General Veterinary Practices
- Research & Academic Institutes
- Home-care Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 34.88% of 2025 revenue. U.S. veterinary spend averaged USD 1,500 per dog, and 22% of arthritic dogs received a monoclonal antibody injection within 12 months of Librela's launch, illustrating biologic traction. Canada's provincial insurance incentives for imaging further increase early diagnosis rates, whereas Mexico's emerging middle class is price sensitive, dampening biologic uptake but stimulating generic NSAID sales.
Asia-Pacific is the fastest-growing region at 9.88% CAGR. China's pet economy hit RMB 130 billion (USD 18.2 billion) in 2024, with millennial owners prioritizing preventive care. Japan's high insurance penetration and hospice services showcase market maturity. India and South-East Asian nations are easing import rules for veterinary biologics, a policy change expected to accelerate growth of the canine arthritis treatment and diagnostics market.
Europe held 27.62% of 2025 revenue. Germany and France favor holistic adjuncts, while the United Kingdom's 25% insurance penetration boosts rehabilitative therapy demand. EMA's centralized procedure for biosimilar biologics promises price competition and broader access. Emerging regions in South America and the Middle East are smaller today yet show double-digit growth curves fueled by rising disposable income and greater availability of imported therapeutics.
- American Regent (Adequan)
- AniCell Biotech
- Antech Diagnostics
- Arthrex Vet Systems
- Boehringer Ingelheim Internation GmBH
- Can-Fite BioPharma
- Ceva Sante Animale
- Dechra Pharmaceuticals
- Elanco
- Epica Medical Innovation
- Heska
- IDEXX
- Medrego
- Merck
- Nutramax Laboratories
- Nutri-Vet
- OrthoPets / Movora
- Vetalogica
- Vetoquinol
- VetStem Biopharma
- Zoetis
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High Prevalence Of Canine Obesity & Motion Injuries
- 4.2.2 Ageing Pet Population & "Pet-Humanization" Trend
- 4.2.3 Rising Penetration Of Pet Insurance & Veterinary Spend
- 4.2.4 Regulatory Fast-Track For Veterinary Monoclonal Antibodies
- 4.2.5 AI-Driven Radiomics Enabling Sub-Clinical OA Detection
- 4.2.6 Preventive Joint-Health Functional Treats Gaining Traction
- 4.3 Market Restraints
- 4.3.1 High Lifetime Cost Of Long-Term Analgesic / Biologic Therapy
- 4.3.2 NSAID-Related Safety Concerns
- 4.3.3 Limited Reimbursement For Advanced Imaging & Gait Analytics
- 4.3.4 Divergent Global Rules For Autologous Cell & Gene Therapies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Therapeutic Drug Class
- 5.1.1.1 NSAIDs
- 5.1.1.2 Monoclonal Antibodies
- 5.1.1.3 Nutraceutical Supplements
- 5.1.1.4 Disease-Modifying OA Drugs (DMOADs)
- 5.1.1.5 Autologous Cell & Gene Therapies
- 5.1.1.6 Others
- 5.1.2 Diagnostic Modality
- 5.1.2.1 Physical Examination / Palpation
- 5.1.2.2 Radiography (X-ray)
- 5.1.2.3 Advanced Imaging (CT / MRI / Ultrasound)
- 5.1.2.4 Force-plate & Gait-analysis Wearables
- 5.1.2.5 Biomarker Panels (Serum / Synovial Fluid)
- 5.1.1 Therapeutic Drug Class
- 5.2 By Disease Stage
- 5.2.1 Pre-clinical / Grade 0-1
- 5.2.2 Mild / Grade 2
- 5.2.3 Moderate / Grade 3
- 5.2.4 Severe / Grade 4
- 5.3 By Dog Size
- 5.3.1 Small (Less than 10 kg)
- 5.3.2 Medium (10-25 kg)
- 5.3.3 Large (25-40 kg)
- 5.3.4 Giant (More Than 40 kg)
- 5.4 By Age Group
- 5.4.1 Juvenile (Less Than 1 yr)
- 5.4.2 Adult (1-7 yrs)
- 5.4.3 Senior (More Than 7 yrs)
- 5.5 By End User
- 5.5.1 Veterinary Hospitals & Specialty Clinics
- 5.5.2 General Veterinary Practices
- 5.5.3 Research & Academic Institutes
- 5.5.4 Home-care Settings
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 American Regent (Adequan)
- 6.3.2 AniCell Biotech
- 6.3.3 Antech Diagnostics
- 6.3.4 Arthrex Vet Systems
- 6.3.5 Boehringer Ingelheim Internation GmBH
- 6.3.6 Can-Fite BioPharma
- 6.3.7 Ceva Sante Animale
- 6.3.8 Dechra Pharmaceuticals
- 6.3.9 Elanco Animal Health
- 6.3.10 Epica Medical Innovation
- 6.3.11 Heska Corp.
- 6.3.12 Idexx Laboratories
- 6.3.13 Medrego
- 6.3.14 Merck Animal Health
- 6.3.15 Nutramax Laboratories
- 6.3.16 Nutri-Vet
- 6.3.17 OrthoPets / Movora
- 6.3.18 Vetalogica
- 6.3.19 Vetoquinol
- 6.3.20 VetStem Biopharma
- 6.3.21 Zoetis Services LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


