

|
시장보고서
상품코드
2114342
에틸렌아민 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Ethyleneamines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 에틸렌아민 시장 규모는 2025년에 22억 1,000만 달러로 평가되었고, 2026년 23억 3,000만 달러에서 2031년까지 30억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.28%를 나타낼 전망입니다.
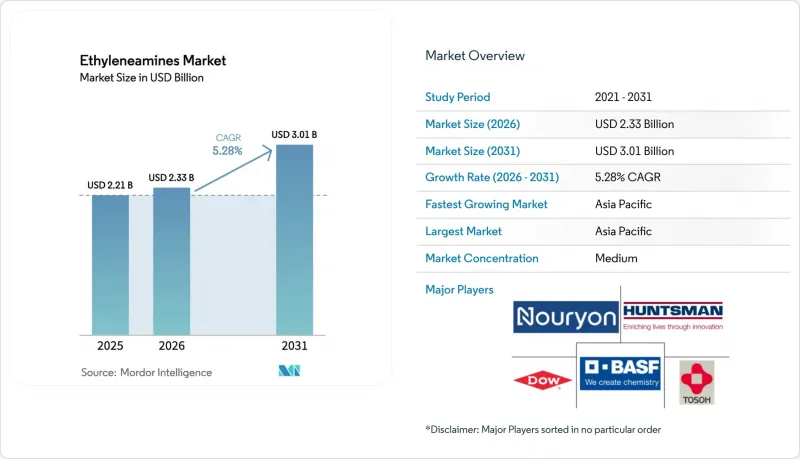
본 보고서는 유형별(에틸렌디아민 및 중급 에틸렌아민), 최종 사용자 산업별(퍼스널케어, 펄프 및 종이, 접착제·도료·수지, 농약, 자동차, 의약품, 석유 및 가스,섬유, 금속, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 에틸렌아민 시장 동향 및 인사이트
풍력 발전용 블레이드 생산에 따른 에폭시 수지 수요 급증
풍력 터빈 제조업체들과 수년에 걸친 에폭시 수지 공급 계약이 체결됨에 따라, 폴리아민계 경화제의 소비가 급증하고 있으며, 그 결과 에틸렌아민 시장의 거래량이 확대되고 있습니다. 헌츠맨(Huntsman)사는 실온에서 경화되는 에틸렌아민계 시스템을 제공하여, 길이 80미터를 초과하는 블레이드에 필요한 내피로성을 확보하고 있습니다. 2024년, 중국은 풍력 발전 용량을 대폭 확대했으나, 1기가와트당 다량의 에폭시 수지가 필요하기 때문에 중질 에틸렌아민에 대한 수요가 더욱 높아지고 있습니다. 유럽의 풍력 터빈 블레이드 제조업체들은 진공 주입용 수지로의 전환을 추진하고 있으며, 겔화 시간을 관리하기 위해 맞춤형 DETA 및 TETA 블렌드가 필요합니다. 로터 직경의 확대에 따라 더 신속한 완전 경화를 실현하기 위해 두꺼운 라미네이트가 요구되고 있으며, 그 결과 아민과 수지의 비율이 터빈 대수 증가 속도를 웃도는 속도로 상승하고 있습니다.
아시아 및 남미의 농약 소비량 증가
농가들이 글리포세이트 내성에 대응하는 가운데, 브라질과 아르헨티나에서는 에틸렌디아민 염을 이용한 제초제 제제가 다시 주목받고 있습니다. 2024년, 인도는 몇 가지 새로운 작물 보호 제제를 승인했는데, 그중 다수는 엽면 흡수를 높이기 위해 에틸렌디아민계 보조제를 배합하고 있습니다. 세계 최대의 글리포세이트 생산국인 중국은 제14차 5개년 계획에서 고부가가치 농약 중간체를 전략적 분야로 지정하여, 에틸렌디아민에 대한 국내 수요를 뒷받침하고 있습니다. 2024년에는 남미의 대두 재배 면적이 대폭 확대됨에 따라 제초제 살포량이 급증했고, 이에 따라 에틸렌디아민 유도체의 사용량도 증가했습니다. 규제 당국의 신속한 승인 및 국내 생산 능력 강화가 농약 분야의 에틸렌아민 시장의 단기적 성장을 뒷받침하고 있습니다.
독성에 기반한 작업장 노출 한계치 강화
산업안전보건 당국이 일부 에틸렌아민의 노출 한계치를 1 ppm으로 하향 조정한 데 따라, 각 생산 기업들은 격리 설비 업그레이드에 투자하고 있습니다. REACH에 따른 유럽화학물질청(ECHA)의 심사에 수반되는 승인 수수료는 생산 비용을 상승시킬 가능성이 있습니다. 헌츠맨(Huntsman)은 모스 공장의 가동 중단에 앞서, 2025년에 환경 및 안전 대책 지출을 포함한 사업 재편 비용을 계상했습니다. 제제 제조업체들은 폴리에테르아민을 부분적인 대체재로 시험하고 있지만, 경화 속도와 내구성 간의 상충 관계로 인해 광범위한 대체는 이루어지지 않고 있습니다. 규제 집행이 엄격해지는 가운데, 생산 능력 확충은 규제 방향이 명확한 지역으로 이동하고 있어, 에틸렌아민 시장의 세계적 구도를 재편하고 있습니다.
부문별 분석
에틸렌디아민은 2025년에 에틸렌아민 시장의 62.94%를 차지한 것으로 평가되었으며, 폴리에테르아민 제조 및 수처리용 킬레이트제로서의 이중 역할에 힘입어 2031년까지 연평균 성장률(CAGR) 5.36%로 성장할 것으로 전망됩니다. DETA, TETA, TEPA, AEP 등의 중질 에틸렌아민은 에폭시 수지의 경화, 아스팔트 개질, 유전용 화학 약품에 공급되고 있으며, 높은 아민 작용기가 접착성과 피막 형성을 촉진하고 있습니다. 바이오 유래 원료의 기세가 커지고 있으며, BASF와 에보닉은 2024년에 바이오물질 수지형 암모니아에 관한 합의를 체결하여, 가격 프리미엄이 붙는 ISCC PLUS 인증을 취득할 수 있게 되었습니다.
피페라진은 생산량은 적지만, 항히스타민제나 구충제의 중간체로 제약 분야에서 안정적인 수요가 있습니다. 아미노에틸피페라진은 고리형 및 직쇄형 화학 반응을 연결하는 역할을 수행하며, 폴리우레아 코팅의 신속한 경화 및 파이프라인에서 강력한 부식 방지 효과를 가져옵니다. 로터 블레이드의 대형화 및 저VOC 규제 강화에 따라, 배합 사양에서 아민 관능기의 허용 범위가 좁게 설정되는 경우가 많아, 폭넓은 중급 아민을 구비한 공급업체가 우위를 점하고 있습니다. 이러한 수요로 인해 에틸렌아민 시장에서 통합형 생산자의 우위가 더욱 강화되고 있습니다. 예측 기간 동안 복합재료, 유전, 특수 접착제 분야의 용도에 힘입어 중급 아민인 에틸렌아민 시장 규모는 꾸준히 확대될 것으로 전망됩니다.
지역별 분석
아시아태평양은 2025년에 전 세계 총량의 53.32%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.43%를 나타낼 것으로 전망됩니다. 중국에서는 통합형 복합 시설 확충이 진행 중이며, 헝리 석유화학(Hengli Petrochemical)이 특수 소재 부문을 주도하고 있습니다. 에틸렌아민을 포함한 이 부문은 자체 생산한 에틸렌옥사이드를 하류 유도체와 전략적으로 결합함으로써 비용 면에서의 우위를 확보하고 있습니다. 한편, 인도는 하류 화학제품에 대한 막대한 설비 투자로 주목받고 있으며, 특히 농약 및 계면활성제 분야의 후방 통합에 중점을 두고 있습니다. 일본과 한국은 전자 및 자동차 제조 분야에서 매우 중요한 역할을 하고 있지만, 그 성장률은 지역 평균보다 낮습니다. 동남아시아에서는 가처분 소득 증가가 다국적 퍼스널케어 기업들을 유치하고 있으며, 이에 따라 계면활성제의 현지 생산이 확대되고 에틸렌아민의 수입이 급증하고 있습니다.
북미는 견실한 생산 능력을 보유하고 있음에도 불구하고 경쟁 압박에 직면해 있습니다. 사우디아라비아에 위치한 다우의 합작 기업 ‘사다라’는 비용 경쟁력이 뛰어난 아민을 출하함으로써 전 세계적으로 주목을 받고 있으며, 이를 통해 걸프 코스트 지역의 수출 점유율을 서서히 빼앗고 있습니다. 모스 공장의 폐쇄에 따라 헌츠맨(Huntsman)은 초콜릿-바이유 공장의 사업 중점을 에폭시 및 유전 관련 고객으로 전환했습니다. 지속가능성을 향한 움직임의 일환으로, 캐나다의 Path2Zero 에틸렌 복합 시설은 저탄소 에틸렌옥사이드 생산을 시작했으며, 앨버타주를 환경 의식이 높은 구매자들에게 주요 공급 거점으로 자리매김하고 있습니다. 멕시코는 걸프 코스트의 원료 공급원과의 근접성을 활용하여, 미국의 퍼스널케어 브랜드에 대응하기 위해 계면활성제 생산 라인을 확충하고 있습니다.
유럽에서는 에너지 비용 급등과 엄격한 REACH 규제로 어려움을 겪고 있습니다. 이에 따라 BASF의 앤트워프 알킬에탄올아민 생산 확대나 에보닉의 난징 특수 아민 제조 시설 등, 유럽 수요에 전략적으로 대응하는 선택적 투자가 이루어지고 있습니다. 남미에서는 수입 의존도가 높은 품목과 여전히 농약 소비가 주목받고 있습니다. 중동은 SABIC의 에틸렌아민 제조 설비와 헌츠맨의 ‘아라비안 아민스(Arabian Amines)’ 합작 사업에 힘입어 아시아와 유럽 양쪽으로 수출을 진행하고 있습니다. 또한, 지속가능성 노력을 강조하기 위해 이산화탄소 포집 프로젝트 검토도 진행 중입니다. 아프리카에서는 이 시장이 아직 발전 초기 단계에 있지만, 수요는 주로 수입 농약과 도료에 의해 견인되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.26According to Mordor Intelligence, the ethyleneamines market size was valued at USD 2.21 billion in 2025 and is estimated to grow from USD 2.33 billion in 2026 to reach USD 3.01 billion by 2031, at a CAGR of 5.28% during the forecast period (2026-2031).
This report is Segmented by Type (Ethylenediamine and Heavy Ethyleneamines), End-User Industry (Personal Care, Pulp and Paper, Adhesives/Paints/Resins, Agrochemicals, Automotive, Pharmaceutical, Oil and Gas, Textile, Metal, and Other), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Ethyleneamines Market Trends and Insights
Booming Epoxy-Resin Demand from Wind-Energy Blade Production
Multi-year epoxy supply agreements are being inked by wind-turbine manufacturers, leading to a surge in the consumption of polyamine curing agents and, consequently, boosting volumes in the ethyleneamines market. Huntsman provides ethyleneamine-based systems that cure at room temperature, ensuring the necessary fatigue resistance for blades longer than 80 meters in length. In 2024, China bolstered its wind capacity significantly, with each gigawatt requiring substantial amounts of epoxy resin, thereby amplifying the demand for heavy ethyleneamines. European manufacturers of wind turbine blades are transitioning to vacuum-infusion resins, which necessitate customized DETA and TETA blends to manage gel time. With the expansion of rotor diameters, there's a need for thicker laminates to achieve a quicker through-cure, resulting in an amine-to-resin ratio that escalates at a pace outstripping the increase in turbine unit counts.
Rising Agrochemical Consumption in Asia and South America
As growers combat glyphosate resistance, Brazil and Argentina see a resurgence in herbicide formulations utilizing ethylenediamine salts. In 2024, India greenlit several new crop-protection formulations, many incorporating ethylenediamine-based adjuvants to boost foliar uptake. China, the globe's leading glyphosate producer, highlights high-value agrochemical intermediates as strategic in its 14th Five-Year Plan, bolstering local demand for ethyleneamines. With South American soybean acreage expanding significantly in 2024, herbicide application intensity surged, driving up the use of ethyleneamine derivatives. Swift regulatory approvals and bolstered domestic capacities fuel the short-term growth of the ethyleneamines market within the agrochemical sector.
Toxicity-Driven Workplace Exposure Limits Tightening
Producers are investing in containment upgrades as occupational agencies lower exposure limits for several ethyleneamines to 1 ppm. Authorization fees from European Chemicals Agency reviews under REACH could raise production costs. Before idling its Moers plant, Huntsman incurred restructuring charges in 2025, which included spending on environmental and safety measures. While formulators are testing polyetheramines as partial substitutes, trade-offs in cure speed and durability hinder widespread replacement. With tightening enforcement, capacity additions are moving toward regions with clearer regulatory pathways, reshaping the global footprint of the ethyleneamines market.
Other drivers and restraints analyzed in the detailed report include:
- Surfactant and Detergent Capacity Additions in Asia-Pacific
- Shift to Low-VOC Coatings Using Polyamine Curing Agents
- Volatile Ethylene Oxide and Ammonia Feedstock Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ethylenediamine captured 62.94% of the ethyleneamines market share in 2025 and is projected to grow at a 5.36% CAGR through 2031, underpinned by its dual role in polyetheramine production and water-treatment chelation. Heavy ethyleneamines such as DETA, TETA, TEPA, and AEP supply epoxy curing, asphalt modification, and oilfield chemicals where higher amine functionality drives adhesion and film build. Bio-attributed feedstocks are gaining momentum; BASF and Evonik signed a biomass-balanced ammonia agreement in 2024, allowing ISCC PLUS certification that carries a price premium.
Piperazine, though smaller in volume, enjoys steady pharmaceutical demand as an intermediate for antihistamines and anthelmintics. Aminoethylpiperazine bridges cyclic and linear chemistries, offering fast cure in polyurea coatings and robust corrosion inhibition in pipelines. As rotor blades lengthen and low-VOC regulations tighten, formulations often specify narrow amine functionality windows, favoring suppliers with broad heavy-amine slats. These needs reinforce the dominance of integrated producers within the ethyleneamines market. Over the forecast, the ethyleneamines market size for heavy amines is expected to expand steadily, supported by composite, oilfield, and specialty-adhesive applications.
Complete Report Scope:
- By Type
- Ethylenediamine (EDA)
- Heavy Ethyleneamines (DETA, TETA, TEPA, AEP, etc.)
- By End-user Industry
- Personal Care Industry
- Pulp and Paper Industry
- Adhesives, Paints, and Resins
- Agro Chemicals Industry
- Automotive Industry
- Pharmaceutical Industry
- Oil and Gas Industry
- Textile Industry
- Metal Industry
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 53.32% of global volume in 2025 and is forecast to post a 5.43% CAGR to 2031. China is ramping up its integrated complexes, with Hengli Petrochemical spearheading a specialty-materials unit. This unit, which includes ethyleneamines, strategically pairs captive ethylene oxide with downstream derivatives, ensuring a cost edge. Meanwhile, India is making waves with a substantial capital investment in downstream chemicals, particularly emphasizing backward integration in agrochemicals and surfactants. While Japan and South Korea play pivotal roles in electronics and auto manufacturing, their growth lags behind the regional average. In Southeast Asia, rising disposable incomes are luring multinational personal-care firms, leading to localized surfactant production and a surge in ethyleneamine imports.
North America, despite its robust production capabilities, grapples with competitive pressures. Dow's Sadara joint venture in Saudi Arabia is making global waves by shipping cost-advantaged amines, thereby nibbling away at the Gulf Coast's export share. Following the closure of its Moers facility, Huntsman has pivoted its Chocolate Bayou plant's focus towards epoxy and oilfield clientele. In a move towards sustainability, Canada's Path2Zero ethylene complex is rolling out low-carbon ethylene oxide, positioning Alberta as a prime supply hub for environmentally-conscious buyers. Capitalizing on its proximity to Gulf-Coast feedstocks, Mexico is ramping up its surfactant lines to cater to U.S. personal-care brands.
Europe grapples with soaring energy costs and stringent REACH regulations. This has led to selective investments, such as BASF's expansion of alkyl-ethanolamines in Antwerp and Evonik's specialty-amine facility in Nanjing, strategically catering to European demand. In South America, the focus remains on agrochemical consumption, albeit with a heavy reliance on imports. The Middle East, bolstered by SABIC's ethyleneamine unit and Huntsman's Arabian Amines venture, is exporting to both Asia and Europe. They're also exploring carbon-capture projects to bolster their sustainability image. Africa, still in its infancy in this market, sees demand primarily driven by imported agrochemicals and coatings.
- Alkyl Amines Chemicals Ltd.
- Arabian Amines Company
- Arkema
- BALAJI SPECIALITY CHEMICALS LIMITED
- BASF SE
- Delamine BV
- Diamines and Chemicals Ltd.
- Dow
- Eastman Chemical Company
- Evonik Industries
- Huntsman International LLC
- INEOS
- Nouryon
- Oriental Union Chemical Corporation
- SABIC
- Sadara Chemical Company
- Tosoh Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Booming epoxy-resin demand from wind-energy blade production
- 4.2.2 Rising agrochemical consumption in Asia and South America
- 4.2.3 Surfactant and detergent capacity additions in Asia-Pacific
- 4.2.4 Shift to low-VOC coatings using polyamine curing agents
- 4.2.5 CO2-capture solvent Research and Development using ethyleneamines blends
- 4.3 Market Restraints
- 4.3.1 Toxicity-driven workplace exposure limits tightening
- 4.3.2 Volatile ethylene oxide and ammonia feedstock pricing
- 4.3.3 Emerging bio-based polyamines cannibalising petro routes
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Ethylenediamine (EDA)
- 5.1.2 Heavy Ethyleneamines (DETA, TETA, TEPA, AEP, etc.)
- 5.2 By End-user Industry
- 5.2.1 Personal Care Industry
- 5.2.2 Pulp and Paper Industry
- 5.2.3 Adhesives, Paints, and Resins
- 5.2.4 Agro Chemicals Industry
- 5.2.5 Automotive Industry
- 5.2.6 Pharmaceutical Industry
- 5.2.7 Oil and Gas Industry
- 5.2.8 Textile Industry
- 5.2.9 Metal Industry
- 5.2.10 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Alkyl Amines Chemicals Ltd.
- 6.4.2 Arabian Amines Company
- 6.4.3 Arkema
- 6.4.4 BALAJI SPECIALITY CHEMICALS LIMITED
- 6.4.5 BASF SE
- 6.4.6 Delamine BV
- 6.4.7 Diamines and Chemicals Ltd.
- 6.4.8 Dow
- 6.4.9 Eastman Chemical Company
- 6.4.10 Evonik Industries
- 6.4.11 Huntsman International LLC
- 6.4.12 INEOS
- 6.4.13 Nouryon
- 6.4.14 Oriental Union Chemical Corporation
- 6.4.15 SABIC
- 6.4.16 Sadara Chemical Company
- 6.4.17 Tosoh Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


