

|
시장보고서
상품코드
2114383
주사 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Rosacea - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 주사 시장 규모는 2025년에 22억 7,000만 달러, 2026년 24억 6,000만 달러에서 2031년까지 36억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.22%를 기록할 전망입니다.
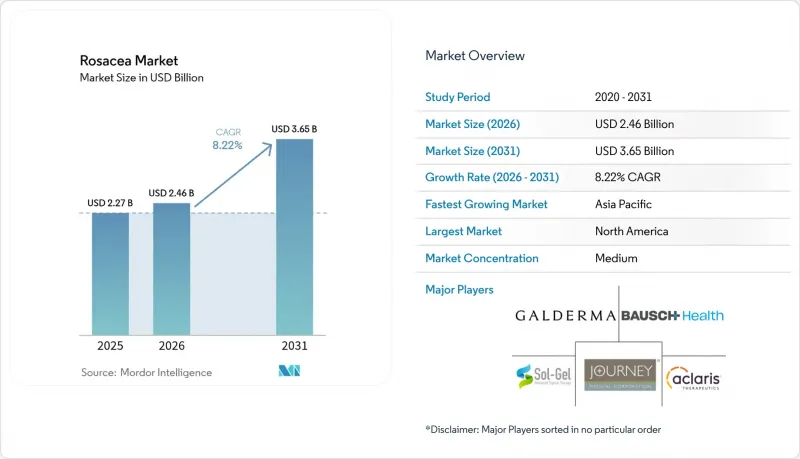
본 보고서는 약물 분류별(항생제, α-아드레날린 작용제, 레티노이드, 코르티코스테로이드, 면역억제제, 기타 약물 분류), 투여 경로별(외용 및 경구),지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 세분화되어 있습니다. 본 보고서에서는 상기 각 부문 시장 규모(100만 미달러)를 제시하고 있습니다.
전 세계 주사비 시장 동향 및 인사이트
30-60세 성인의 유병률 증가가 수요를 견인
30-60세 연령층의 발병률이 증가하고 있으며, 치료 수요가 소득이 가장 높은 시기나 의료 관련 의사 결정에 있어 자율성이 높아지는 시기와 겹치고 있습니다. 선진국에서 스트레스, 식생활, 환경적 요인에의 노출이 증상 발현을 촉진하여 내원자 수와 처방량이 증가하고 있습니다. 환자들은 로사세를 단순한 미용상의 고민이 아닌 의학적 질환으로 인식하는 경향이 강해지고 있으며, 만성적인 약물 치료를 지속하려는 의지가 높아지고 있습니다. 이 인구층의 확대는 치료 대상자의 안정적인 기반을 확보하여 로사세 시장의 장기적인 성장을 뒷받침하고 있습니다.
FDA의 신규 외용제 승인이 혁신을 가속화
최근 규제 측면의 진전으로 치료 기준이 재정의되었습니다. EPSOLAY의 마이크로캡슐화된 벤조일 퍼옥사이드(BPO)는 12주 만에 병변을 70% 가까이 감소시켜, 유효성과 내약성을 동시에 확보하는 수단으로서 서방형 제제의 유효성을 입증했습니다. Emrosi는 홍반과 염증성 병변을 동시에 조절하는 것으로 승인된 최초의 경구 치료제로, Oracea에 비해 우월성을 보여주면서도 동등한 안전성을 유지하고 있습니다. 이러한 승인으로 차세대 약물의 개발 기간이 단축되고 파이프라인에 대한 투자가 활성화되면서, 주사 산업 전체의 혁신 수준이 높아지고 있습니다.
고가의 브랜드 의약품 처방으로 인해 접근성이 제한됩니다.
고급 브랜드 젤의 소매 가격은 1일 분 치료당 60.90달러에서 152.25달러에 달할 수 있어, 환자와 보험사 모두에게 부담을 주고 있습니다. 사전 승인 절차의 장벽과 계층화된 처방약 목록으로 인해 많은 사용자가 구형 제네릭 의약품을 선택할 수밖에 없어, 임상적 우위가 있음에도 불구하고 혁신적인 약물의 보급이 제한되고 있습니다. 이러한 경제적 장벽은 신흥국에서 특히 두드러지며, 비용 억제책이나 차별화된 가격 모델이 정착되기 전까지는 주사(rosacea) 시장의 성장 가능성을 저해할 것입니다.
부문 분석
α-아드레날린 작용제는 혈관 수축 작용을 통해 안면의 홍반을 급속히 완화함으로써, 2025년에도 주사 시장의 38.12% 점유율을 유지했습니다. JAK 억제제는 규모는 작지만, 난치성 환자의 염증성 병변과 홍반을 모두 억제하는 능력이 임상적 증거로 입증되어 연평균 성장률(CAGR) 9.05%로 성장을 지속하고, 있습니다. 항생제, 특히 독시사이클린 유도체는 구진·농포형 아형에 대한 효능을 유지하고 있는 반면, 아젤라산은 경증 사례를 위한 이중 작용을 하는 외용제로 자리 잡았습니다. 이베르멕틴은 견조한 성장세를 유지하고 있지만, 특정 유효 성분(API)공급망에 의존하고 있기 때문에 이 부문은 가격 변동 위험에 노출될 가능성이 있습니다. 벤조일 퍼옥사이드(BPO)는 기존 제품의 내약성 문제를 극복한 마이크로캡슐 제형으로, 임상의들의 치료 옵션에 다시 포함되고 있습니다. 따라서 경쟁 우위는 작용기전의 상호 보완성과 환자의 편의성을 보장하는 첨단 제형 간의 조합에 달려 있습니다.
α-아드레날린 작용제의 주사 시장 규모는 꾸준히 확대될 것으로 예상되지만, JAK 억제제의 적응증이 확대되면 그 시장 점유율은 후퇴할 가능성이 있습니다. 파이프라인의 다양성은 급속한 혈관 수축과 면역 조절을 결합한 복합 제제에 유리하게 작용하며, 관해 기간을 연장하는 단계적 감량 전략을 기대하게 합니다. 기존 브랜드 의약품 제조업체들은 저농도 제제나 환자가 사용하기 편한 도포기 등 제품 수명 주기 연장을 위한 투자를 통해 이러한 위협에 대응하고 있습니다. 전반적으로, 약물 군별 경쟁은 획일적인 항염증 작용에서 정밀한 표적 치료로의 전환을 보여주고 있으며, 이러한 경향은 치료 알고리즘을 재정의하고 신규 진입 업체를 유치하고 있습니다.
지역별 분석
북미는 보험 적용 범위가 넓고 의사 밀도가 높은 점을 바탕으로 2025년 주사(rosacea) 시장 점유율의 41.85%를 차지했습니다. EPSOLAY나 Emrosi와 같은 신약 승인에 있어 FDA가 신속한 대응을 보임에 따라, 이 지역은 세계 시장 진출의 발판으로서의 입지를 더욱 공고히 하고 있습니다. 유럽은 엄격하면서도 조화로운 규제 하에서 꾸준한 성장을 보이고 있지만, 새로운 EU 미세 플라스틱 지침에 따라 일부 씻어내지 않는 유형의 젤 제제의 경우, 제형 변경에 따른 비용이 발생할 가능성이 있습니다. 아시아태평양은 도시 소비자들이 피부과 서비스를 이용하기 시작하고, 원격의료가 지방의 접근성 격차를 해소함에 따라 2031년까지 연평균 성장률(CAGR) 10.01%를 기록할 전망입니다. 남미와 중동 및 아프리카는 아직 발전의 초기 단계에 있지만, 전문의 양성 프로그램 증가와 대중 계몽 활동의 추진에 따라 유사한 추세를 보이고 있습니다.
로사시아 시장 규모 차이는 보험 환급 지원이 있는 지역에 유리하게 작용하지만, 인구 규모가 크기 때문에 아시아태평양이 장기적으로는 판매량의 주요 원동력이 될 것으로 보입니다. 유럽 및 미국 기업들은 신규 분자와 현지 유통망을 결합한 전략적인 라이선싱을 통해 해당 지역으로의 진출을 모색하고 있습니다. 한편, 현지 제네릭 의약품 제조업체들은 가격에 민감한 부문을 선점하고 있어 가격 경쟁을 격화시키고 있습니다. 환율 동향, 규제 심사 속도, 디지털 인프라의 성숙도가 예측 기간 동안 지역별 성장 궤적의 상호작용을 결정지을 것으로 보입니다.
유럽에서는 각국의 의료 기술 평가가 시장 출시 시기에 영향을 미치고 있어, 제조업체들은 주요 임상시험 외에도 확고한 실세계 증거(RWE)를 수집해야 합니다. 이러한 요건으로 인해 시장 침투가 지연될 가능성은 있지만, 궁극적으로는 입증된 비용 대비 효과를 통해 시장 입지를 공고히할 것으로 보입니다. 라틴아메리카 시장에서는 민관 파트너십을 활용하여 피부과 의료 체계의 기반 조성이 진행되고 있으며, 다국적 기업들에게는 구독형 케어 모델을 시범적으로 도입할 수 있는 장이 되고 있습니다. 이처럼 지역별 상황은 다양해지고 있으며, 북미의 성숙한 수익성과 신흥 시장 규모에 따른 성장 여력이 융합되어, 전체적으로 견조한 주사(rosacea) 시장을 견인하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측(금액, 2023-2030년)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.26According to Mordor Intelligence, the rosacea market size was valued at USD 2.27 billion in 2025 and estimated to grow from USD 2.46 billion in 2026 to reach USD 3.65 billion by 2031, at a CAGR of 8.22% during the forecast period (2026-2031).
This report is Segmented by Drug Class (Antibiotics, Alpha Agonists, Retinoid, Corticosteroids, Immunosuppressants, and Other Drug Classes), Mode of Administration (Topics and Oral), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America). The Market Provides the Value (in USD Million) for the Above Segments.
Global Rosacea Market Trends and Insights
Rising Prevalence Among Adults 30-60 Years Drives Demand
Incidence among people aged 30-60 years is climbing, aligning treatment need with peak earning capacity and autonomy in healthcare decision-making. Stress, diet, and environmental exposures in developed regions intensify symptom onset, boosting physician visits and prescription volumes. Patients increasingly recognize rosacea as a medical disorder rather than a cosmetic nuisance, bolstering willingness to pursue chronic pharmacotherapy. The demographic swell ensures a stable base of treatment candidates, underpinning long-range expansion of the rosacea treatment market .
FDA Approvals of Novel Topical Agents Accelerate Innovation
Recent regulatory momentum redefined therapeutic benchmarks. EPSOLAY's micro-encapsulated benzoyl peroxide achieved near-70% lesion reduction in 12 weeks, validating sustained-release chemistry as a means to marry efficacy with tolerability . Emrosi became the first oral therapy approved for concurrent control of erythema and inflammatory lesions, demonstrating superiority to Oracea yet retaining safety parity. These clearances compress development timelines for next-wave agents and intensify pipeline investment, lifting the innovation baseline across the rosacea industry.
High Cost of Branded Prescriptions Limits Access
Retail prices for premium branded gels can run between USD 60.90 and USD 152.25 per daily treatment success, burdening patients and insurers alike. Prior authorization hurdles and tiered formularies steer many users toward older generics, capping uptake of innovative agents despite clinical superiority. The financial barrier is most pronounced in emerging economies, dampening the rosacea market expansion potential until cost-containment or differential pricing models gain traction.
Other drivers and restraints analyzed in the detailed report include:
- Growing Tele-Dermatology & E-Pharmacy Uptake Transforms Care
- Advances in Micro-Encapsulated Drug Delivery Enhance Efficacy
- Treatment-Related Irritation & Poor Adherence Undermine Outcomes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Alpha-adrenergic agonists retained 38.12% of rosacea market share in 2025 by rapidly shrinking facial erythema through vasoconstriction. JAK inhibitors, albeit from a smaller base, are logging a 9.05% CAGR as clinical evidence confirms their ability to curb both inflammatory lesions and redness in refractory patients. Antibiotics, especially doxycycline derivatives, preserve utility for papulopustular subtypes, whereas azelaic acid persists as a dual-action topical for mild cases. Ivermectin remains resilient but relies on a concentrated API supply chain that could expose the segment to volatility. Benzoyl peroxide re-enters clinician armamentaria under micro-encapsulated designs that override historical tolerability barriers. Competitive positioning therefore revolves around combining mechanistic complementarity with advanced carriers that secure patient comfort.
The rosacea market size for alpha-adrenergic agonists is forecast to advance steadily, yet their rosacea market share could cede ground if JAK inhibitors achieve broader label indications. Pipeline diversity favors combination products that harness rapid vasoconstriction with immunomodulation, promising step-down strategies that prolong remission. Branded incumbents counter this threat by investing in lifecycle extensions such as lower-concentration formulations and patient-friendly applicators. Collectively, drug-class competition illustrates a pivot toward precision targeting over blanket anti-inflammation, a trajectory that redefines therapy algorithms and invites new entrants.
Complete Report Scope:
- By Drug Class
- Alpha-adrenergic Agonists
- Antibiotics (Tetracyclines, Macrolides)
- Azelaic Acid & Derivatives
- Ivermectin
- Benzoyl Peroxide & Others
- By Route of Administration
- Topical
- Oral
- Others (Injectables, Device-assisted)
- By End-user Facility
- Hospitals & Dermatology Clinics
- Home-care Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 41.85% rosacea market share in 2025 on the back of insurance coverage and physician density. FDA agility in green-lighting novel entities such as EPSOLAY and Emrosi further cements the region as the launchpad for global rollouts . Europe delivers steady gains amid stringent but harmonized regulation; the new EU micro-plastic directive may, however, nudge reformulation costs for certain leave-on gels. Asia-Pacific exhibits a 10.01% CAGR through 2031 as urban consumers adopt dermatology services and telehealth bridges rural access gaps. South America and the Middle East & Africa are earlier-stage but move in tandem with rising specialist training programs and public education drives.
The rosacea market size differential favors regions with reimbursement support, yet sheer population weight positions Asia-Pacific as the dominant long-run volume engine. Western companies court the region via strategic licensing that pairs novel molecules with local distribution prowess. Domestic generics producers, meanwhile, capture cost-sensitive segments, intensifying price competition. Exchange-rate trends, regulatory review pace, and digital infrastructure maturity will dictate regional trajectory interplay over the forecast window.
In Europe, national health technology assessments influence time-to-market, compelling manufacturers to compile robust real-world evidence beyond pivotal trials. This requirement could delay uptake but ultimately fortifies retention through proven cost-utility. Latin American markets lean on public-private partnerships to seed dermatology capacity, offering multinationals pilot grounds for subscription-based care models. The evolving geography matrix thus blends mature profitability in North America with emerging-market scale upside, collectively fueling a resilient rosacea market.
- Galderma
- Bausch Health
- Abbvie
- Leo Pharma
- Foamix Pharmaceuticals Ltd. (Sol-Gel)
- Journey Medical
- Sol-Gel Technologies Ltd.
- Almirall S.A.
- Novan, Inc.
- Pfizer
- Johnson & Johnson
- Sun Pharmaceuticals Industries
- Lupin
- Taro Pharmaceutical Industries Ltd.
- Sato Pharmaceutical Co., Ltd.
- Menlo Therapeutics Inc.
- Tarsus Pharmaceuticals, Inc.
- Mylan
- Perrigo Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence among adults 30-60 yrs
- 4.2.2 FDA approvals of novel topical agents
- 4.2.3 Growing tele-dermatology & e-pharmacy uptake
- 4.2.4 Advances in micro-encapsulated drug delivery
- 4.2.5 JAK-inhibitor pipeline targeting immune pathways
- 4.2.6 AI-powered diagnostic apps boosting early detection
- 4.3 Market Restraints
- 4.3.1 High cost of branded prescriptions
- 4.3.2 Treatment-related irritation & poor adherence
- 4.3.3 EU micro-plastic rule risk to leave-on gels
- 4.3.4 API supply-chain concentration for ivermectin
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, 2023-2030)
- 5.1 By Drug Class
- 5.1.1 Alpha-adrenergic Agonists
- 5.1.2 Antibiotics (Tetracyclines, Macrolides)
- 5.1.3 Azelaic Acid & Derivatives
- 5.1.4 Ivermectin
- 5.1.5 Benzoyl Peroxide & Others
- 5.2 By Route of Administration
- 5.2.1 Topical
- 5.2.2 Oral
- 5.2.3 Others (Injectables, Device-assisted)
- 5.3 By End-user Facility
- 5.3.1 Hospitals & Dermatology Clinics
- 5.3.2 Home-care Settings
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Galderma S.A.
- 6.3.2 Bausch Health Companies Inc.
- 6.3.3 AbbVie Inc.
- 6.3.4 Leo Pharma A/S
- 6.3.5 Foamix Pharmaceuticals Ltd. (Sol-Gel)
- 6.3.6 Journey Medical Corporation
- 6.3.7 Sol-Gel Technologies Ltd.
- 6.3.8 Almirall S.A.
- 6.3.9 Novan, Inc.
- 6.3.10 Pfizer Inc.
- 6.3.11 Johnson & Johnson (Janssen)
- 6.3.12 Sun Pharmaceutical Industries Ltd.
- 6.3.13 Lupin Limited
- 6.3.14 Taro Pharmaceutical Industries Ltd.
- 6.3.15 Sato Pharmaceutical Co., Ltd.
- 6.3.16 Menlo Therapeutics Inc.
- 6.3.17 Tarsus Pharmaceuticals, Inc.
- 6.3.18 Mylan N.V.
- 6.3.19 Perrigo Company plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


