

|
시장보고서
상품코드
2114500
인증 및 시험 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Certification And Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인증 및 시험 시장 규모는 2025년에 2,100억 3,000만 달러로 평가되었습니다. 2026년 2,180억 4,000만 달러에서 2031년까지 2,628억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 3.81%를 나타낼 전망입니다.
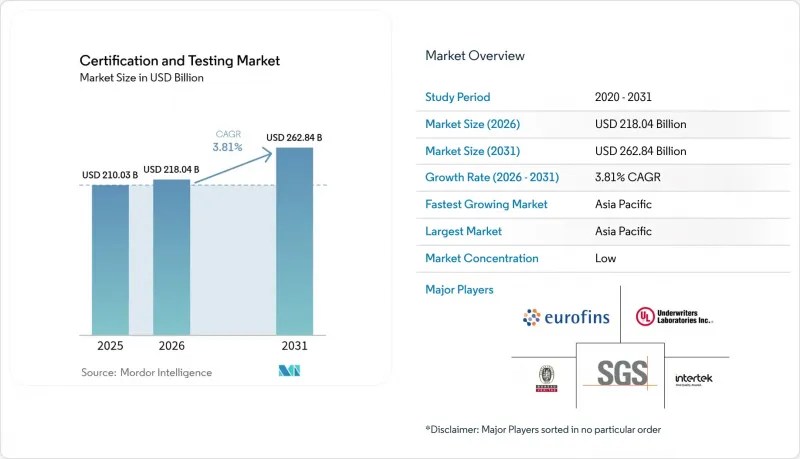
본 보고서는 조달 형태(사내 수행 및 외부 위탁), 최종 사용자 산업(건설 및 엔지니어링, 화학, 식품·헬스케어, 에너지·원자재 등), 시험 유형(기계 시험 등), 인증 유형(제품 유형, 경영 시스템 등), 서비스 유형(인증 및 시험), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 인증 및 시험 시장 동향 및 인사이트
전 세계 무역 규정 준수 요건의 강화
각국 정부는 원산지 확인 및 적합성 증명에 관한 요건을 지속적으로 강화하고 있습니다. 세계관세기구(WCO)는 2024년에 디지털 증명서에 관한 지침을 발표하고, 수출업체에게 조약 부속서에 부합하는 공인 시험소의 데이터를 제공할 것을 요구했습니다. EU의 ‘등록 수출업체(RE)’ 제도에서는 특정 상품에 대해 ISO 17025를 준수하는 시험 보고서 제출이 의무화되어 있으며, 2024년 중반 이후 동남아시아 공급업체의 인증 신청 건수가 2배로 증가했습니다. 미국은 개정된 ‘수출관리규정(Export Administration Regulations)’에 따라 이중용도 제품에 대한 제3자 시험 증거 제출을 의무화했습니다. 그 결과, 대규모로 여러 인증을 받은 시험소는 그 인증서가 전 세계에서 통용되기 때문에 수주량을 늘리고 있는 반면, 지역 공급업체들은 국제인증포럼(IAF) 인증 취득을 서두르고 있습니다.
국경을 초월한 전자상거래의 급속한 확대
주요 마켓플레이스에서는 상품 등록 전 심사 기준이 엄격해지고 있습니다. 아마존은 미국, EU, 일본에서 전자기기, 장난감, 개인 위생 용품에 대해 ISO 17025 보고서를 요구하고 있으며, 이에 따라 시험을 거치지 않은 상품은 제외되고 있습니다. 알리바바의 ‘Tmall Global’에서는 FCC, CE 또는 CCC 마크가 없는 상품이 자동으로 판매 중단되므로, 2024년에는 중국 수출업체들의 인증 관련 문의가 40% 급증했습니다. EU의 디지털 서비스법(DSA)은 안전 기준을 충족하지 않는 제품에 대해 플랫폼에 연대 책임을 부과하고 있어, 이러한 규제를 더욱 강화하고 있습니다. 그 결과, 중소 브랜드들은 규정 준수 업무를 외부 시험소에 위탁하게 되었으며, 인증 및 시험 시장에서 자산 경량화 운영으로의 전환이 가속화되고 있습니다.
산업 설비 투자 주기의 변동
시험 건수는 신제품 출시나 공장 가동 개시와 연동됩니다. 인도 통계청에 따르면, 2021-22 회계연도부터 2024-25 회계연도에 걸쳐 민간 부문의 설비 투자(CAPEX)가 66.3% 증가하여 일시적으로 시험소 수요를 끌어올렸습니다. 2024년 2분기에 전 세계 PMI 지수가 하락하자, 2분기 이내에 인증 수주 잔고가 감소하여 과잉 생산 능력이 발생했습니다. 사내 실험실은 고정 간접비를 부담하고 있어 이러한 압박을 더욱 심각하게 느끼고 있으며, 이로 인해 아웃소싱으로의 전환이 가속화되고 있습니다. 지역 공급업체들은 경기 침체기에 가격을 인하하는 경우가 많아, 인증 및 시험 시장 전체의 이익률을 압박하고 있습니다.
부문별 분석
외부 위탁 제공업체는 2025년에 인증 및 시험 시장의 63.98% 점유율을 차지했으며, 2031년까지 연평균 성장률(CAGR) 4.42%로 확대되어 전체 시장의 성장률을 크게 상회할 것으로 전망됩니다. 이러한 우위는 ISO 17025 인증 시험소를 최신 상태로 유지하는 데 필요한 막대한 투자에 기인하며, 이 비용은 현재 대부분의 제조업체가 고정비가 아닌 변동비로 처리하고 있습니다. UL 솔루션즈가 2024년 3분기에 기록한 8.1%의 매출 성장률은 고객들이 자사 시설에서 철수하는 가운데 대규모 네트워크가 어떻게 업무를 흡수하고 있는지를 보여줍니다.
하이브리드 모델은 여전히 중요합니다. 제약 회사와 반도체 기업은 지적 재산을 보호하기 위해 사내 시험소를 유지하고 있지만, 현재 60%의 기업이 주로 피크 시간대의 부하나 틈새 분야에서 시험량의 최소 30%를 외부에 위탁하고 있습니다. ISO 23247에 기반한 디지털 트윈 표준은 외부 검증에 앞서 내부 시뮬레이션을 통해 설계를 선별할 수 있게 함으로써, 그 경계를 더욱 모호하게 만들 가능성이 있습니다. 전반적으로, 전문 외부 위탁 기업들이 주도적인 역할을 하고 있으며, 이들의 대규모 운영은 인증 및 시험 시장에서 높은 효율성을 유지하는 데 필요한 분석 및 자동화에 대한 예산 투자를 가능하게 하고 있습니다.
식품 및 헬스케어 분야는 FDA의 FSMA 규정 204 및 GFSI 제도에 따라 추적성과 위생 요건이 강화됨에 따라 2025년 매출의 28.15%를 차지했습니다. 이러한 업종에서의 인증 및 시험 시장 규모는 재배, 가공, 유통의 모든 단계에 걸쳐 감사가 이루어지기 때문에 견조한 모습을 유지하고 있습니다.
한편, 운송 분야는 5.28%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 유엔 규정 155 및 156에 따라 EU 및 일본에서 판매되는 모든 신차에 대해 사이버 보안 및 소프트웨어 업데이트 감사가 의무화됨에 따라, 침투 테스트 및 무선 업데이트(OTA) 검증과 관련된 시험소의 업무량이 증가하고 있습니다. 2024년에는 IATF 16949 인증이 12% 증가하여 공급망에 연쇄적인 압박이 가해지고 있음을 보여주었습니다. 배터리 안전에 대한 노력도 새로운 요인으로 작용하고 있으며, 인터텍(Intertek)과 UL은 유엔 규정 38.3 및 IEC 62133의 요건을 충족하기 위해 전용 센터를 건설하고 있습니다. 전동화와 자율주행이 진전됨에 따라, 운송 부문은 인증 및 시험 시장의 성장을 이끄는 주요 동력이 되고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 39.88%를 차지했으며 연평균 성장률(CAGR) 4.21%로 확대되고 있는데, 이는 세계 평균의 거의 2배에 달하는 속도입니다. 중국에서는 CCC 인증 대상 범위가 확대되어 충전기와 산업용 로봇도 포함됨에 따라 현지 시험소의 처리량이 전년 대비 15% 증가했습니다. 인도에서는 BIS가 전자기기 및 통신기기 분야에 진출하면서 처리 지연이 발생했고, 이에 따라 방갈로르와 푸네의 처리 능력 확충이 촉진되었습니다.
북미는 시장 평균에 가까운 속도로 성장하고 있습니다. FCC 기기 승인 및 OSHA 안전 마크는 여전히 영구적인 요건인 반면, ‘인플레이션 억제법’에 따른 배터리 우대 조치로 인해 새로운 시험 범주가 도입되었습니다. 캐나다 표준 평의회는 ISO 17025 인증을 유지하고 있어 국경을 초월한 상호 인정이 유지되고 있습니다.
유럽에서는 CE 마킹 규정에 따라 안정적인 수요가 나타나고 있지만, 브렉시트로 인해 EU와 영국 양쪽에 제품을 판매하는 공급업체는 이중 인증을 받아야 합니다. 중동에서는 사우디아라비아의 SASO와 UAE의 ESMA가 독자적인 적합성 평가 체계를 도입함에 따라 병행 절차가 발생하여 시장 출시 주기가 장기화되는 등 규제가 강화되고 있습니다. 남미와 아프리카의 기여도는 여전히 미미하지만, 브라질의 INMETRO와 남아프리카공화국의 SABS가 강제 적용 품목 목록을 확대함에 따라 점차 수요가 증가할 조짐이 보입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, the certification and testing market size was valued at USD 210.03 billion in 2025 and estimated to grow from USD 218.04 billion in 2026 to reach USD 262.84 billion by 2031, at a CAGR of 3.81% during the forecast period (2026-2031).
This report is Segmented by Sourcing Type (In-House, and Outsourced), End-User Vertical (Construction and Engineering, Chemicals, Food and Healthcare, Energy and Commodities, and More), Testing Type (Mechanical, and More) Certification Type (Product, Management System, and More), Service Type (Certification, and Testing), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Certification And Testing Market Trends and Insights
Intensifying Global Trade Compliance Mandates
Governments continue to tighten origin-verification and conformity documentation. The World Customs Organization issued digital certificate guidelines in 2024, prompting exporters to provide accredited laboratory data that matches treaty annexes. The EU's Registered Exporter scheme now requires ISO 17025 test reports on select goods, doubling certification queues from Southeast Asian suppliers since mid-2024. The United States added third-party test evidence for dual-use items under updated Export Administration Regulations. Large multi-accredited labs, therefore, win volume as their certificates travel globally, while regional providers rush to secure International Accreditation Forum recognition.
Rapid Expansion of Cross-Border E-Commerce
Major marketplaces have imposed stricter pre-listing protocols. Amazon requires ISO 17025 reports for electronics, toys, and personal-care items in the United States, the EU, and Japan, thereby excluding untested goods. Alibaba's Tmall Global auto-delists products lacking FCC, CE, or CCC marks, resulting in a 40% surge in certification inquiries from Chinese exporters in 2024. The EU Digital Services Act makes platforms jointly liable for unsafe products, reinforcing these rules. Smaller brands, therefore, outsource compliance work to external labs, accelerating the shift toward asset-light operations in the certification and testing market.
Volatility in Industrial Capex Cycles
Testing volume tracks new-product launches and plant startups. India's statistical office documented a 66.3% increase in private-sector capital expenditure (capex) between fiscal 2021-22 and 2024-25, temporarily boosting laboratory demand. When global PMI indices dipped in Q2 2024, certification queues thinned within two quarters, leaving spare capacity. In-house labs feel the squeeze more acutely because they carry fixed overhead, which hastens the move to outsourcing. Regional providers often cut prices during downturns, squeezing margins across the certification and testing market.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of IoT and Smart Devices Requiring Certification
- Rising Focus on Product Safety and Quality Among Consumers
- Complex and Fragmented Regulatory Standards Across Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Outsourced providers controlled 63.98% certification and testing market share in 2025 and will climb at a 4.42% CAGR through 2031, well above the headline rate. This dominance stems from the significant investment required to keep ISO 17025 labs current, a cost that most manufacturers now treat as variable rather than fixed. UL Solutions' 8.1% revenue jump in Q3 2024 demonstrates how large networks capture flows as clients exit captive facilities.
Hybrid models still matter. Pharmaceutical and semiconductor firms maintain in-house labs to protect IP, yet 60% now outsource at least 30% of test volume, chiefly for peak loads or niche disciplines. Digital-twin standards under ISO 23247 could blur boundaries further by allowing internal simulation to screen designs before external confirmation. Overall, outsourced specialists set the pace, and their scale unlocks the analytics and automation budgets required to maintain high efficiency in the certification and testing market.
Food and healthcare accounted for 28.15% of 2025 revenue, as the FDA FSMA Rule 204 and GFSI schemes tightened traceability and hygiene demands. The certification and testing market size for these verticals remains resilient because audits occur across planting, processing, and distribution.
Transportation, however, registers the fastest 5.28% CAGR. UN Regulations 155 and 156 compel cybersecurity and software-update audits for every new vehicle type sold in the EU and Japan, expanding laboratory pipelines for penetration tests and over-the-air update validation. IATF 16949 certifications increased by 12% in 2024, indicating a cascading pressure on supply chains. Battery safety work adds another layer, with Intertek and UL constructing dedicated centers to meet UN 38.3 and IEC 62133 demands. As electrification and autonomy advance, transportation becomes the primary driver of growth within the certification and testing market.
Complete Report Scope:
- By Sourcing Type
- In-House
- Outsourced
- By End-User Vertical
- Construction and Engineering
- Chemicals
- Food and Healthcare
- Energy and Commodities
- Transportation
- Products and Retail
- Industrial
- Other End-User Verticals
- By Testing Type
- Mechanical Testing
- Electrical and Electronics Testing
- Chemical Testing
- Environmental and Climatic Testing
- Non-Destructive Testing (NDT)
- EMC and Radio Testing
- Software and Cybersecurity Testing
- By Certification Type
- Product Certification
- Management System Certification
- Personnel Certification
- Service Certification
- By Service Type
- Testing
- Certification
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific contributed 39.88% of 2025 turnover and is advancing at a 4.21% CAGR, almost double the global clip. China's widened CCC catalog now spans chargers and industrial robots, lifting local laboratory volume 15% year-over-year. India's BIS move into electronics and telecom equipment created processing backlogs and spurred capacity additions in Bangalore and Pune.
North America expands near the market average. FCC equipment authorization and OSHA safety marks remain evergreen requirements, while Inflation Reduction Act incentives for batteries introduce new test categories. Canada's Standards Council upholds ISO 17025 accreditation, sustaining cross-border equivalence.
Europe exhibits steady demand under CE marking rules, although Brexit necessitates dual certification for suppliers selling into both the EU and the United Kingdom. The Middle East is tightening rules as Saudi Arabia's SASO and the UAE's ESMA implement distinct conformity assessment schemes, creating parallel pathways that lengthen launch cycles. South America and Africa remain modest contributors, yet Brazil's INMETRO and South Africa's SABS are expanding lists of compulsory items, hinting at gradual upside.
- SGS SA
- Intertek Group PLC
- Bureau Veritas SA
- DEKRA SE
- TUV SUD AG
- Underwriters Laboratories Inc.
- DNV AS
- Eurofins Scientific SE
- ALS Limited
- BSI Group
- SAI Global Pty Limited
- MISTRAS Group Inc.
- Element Materials Technology Group Ltd.
- TUV Rheinland AG
- TUV NORD GROUP
- Applus Services SA
- Kiwa NV
- Lloyd's Register Group Ltd.
- MET Laboratories Inc.
- UL Solutions Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Intensifying Global Trade Compliance Mandates
- 4.2.2 Rapid Expansion of Cross-Border E-Commerce
- 4.2.3 Proliferation of IoT and Smart Devices Requiring Certification
- 4.2.4 Rising Focus on Product Safety and Quality Among Consumers
- 4.2.5 Growing Adoption of Digital Twin Based Remote Certification
- 4.2.6 Emergence of Sustainability Linked Certification Schemes
- 4.3 Market Restraints
- 4.3.1 Volatility in Industrial Capex Cycles
- 4.3.2 Complex and Fragmented Regulatory Standards Across Regions
- 4.3.3 Talent Shortage in Specialized Testing Disciplines
- 4.3.4 Cybersecurity Concerns Over Remote Auditing Platforms
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Investment Analysis
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitute Products
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sourcing Type
- 5.1.1 In-House
- 5.1.2 Outsourced
- 5.2 By End-User Vertical
- 5.2.1 Construction and Engineering
- 5.2.2 Chemicals
- 5.2.3 Food and Healthcare
- 5.2.4 Energy and Commodities
- 5.2.5 Transportation
- 5.2.6 Products and Retail
- 5.2.7 Industrial
- 5.2.8 Other End-User Verticals
- 5.3 By Testing Type
- 5.3.1 Mechanical Testing
- 5.3.2 Electrical and Electronics Testing
- 5.3.3 Chemical Testing
- 5.3.4 Environmental and Climatic Testing
- 5.3.5 Non-Destructive Testing (NDT)
- 5.3.6 EMC and Radio Testing
- 5.3.7 Software and Cybersecurity Testing
- 5.4 By Certification Type
- 5.4.1 Product Certification
- 5.4.2 Management System Certification
- 5.4.3 Personnel Certification
- 5.4.4 Service Certification
- 5.5 By Service Type
- 5.5.1 Testing
- 5.5.2 Certification
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Nigeria
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 SGS SA
- 6.4.2 Intertek Group PLC
- 6.4.3 Bureau Veritas SA
- 6.4.4 DEKRA SE
- 6.4.5 TUV SUD AG
- 6.4.6 Underwriters Laboratories Inc.
- 6.4.7 DNV AS
- 6.4.8 Eurofins Scientific SE
- 6.4.9 ALS Limited
- 6.4.10 BSI Group
- 6.4.11 SAI Global Pty Limited
- 6.4.12 MISTRAS Group Inc.
- 6.4.13 Element Materials Technology Group Ltd.
- 6.4.14 TUV Rheinland AG
- 6.4.15 TUV NORD GROUP
- 6.4.16 Applus Services SA
- 6.4.17 Kiwa NV
- 6.4.18 Lloyd's Register Group Ltd.
- 6.4.19 MET Laboratories Inc.
- 6.4.20 UL Solutions Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


