

|
시장보고서
상품코드
2114531
검체 회수 백 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Specimen Retrieval Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
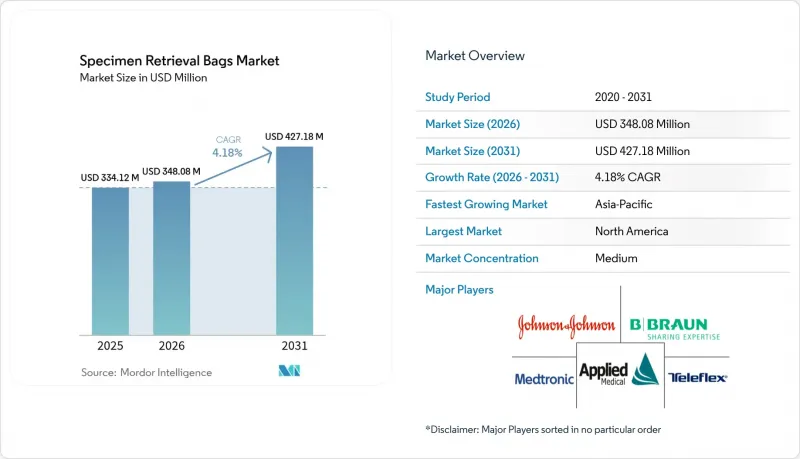
에 의하면, 2026년 검체 회수 백 시장 규모는 3억 4,808만 달러로 추정되고 있어 2025년 3억 3,412만 달러에서 확대해, 2031년에는 4억 2,718만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.18%로 성장할 것으로 전망됩니다.
본 보고서에서는 업계를 ‘유형별(탈부착식 검체 회수 백, 비탈부착식 검체 회수 백)’, ‘용도별(소화기 외과 수술, 비뇨기과 외과 수술, 산부인과 외과 수술, 기타 용도)’, 그리고 ‘지역별’로 분류하고 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
전 세계 검체 회수 백 시장 동향 및 인사이트
최소 침습 수술에 대한 수요 증가
외래수술센터(ASC)에서는 2034년까지 수술 건수가 21% 증가할 것으로 예상되며, 이에 따라 단축된 수술 시간에 적합한 신뢰성 높은 검체 회수 백에 대한 수요가 직접적으로 증가하고 있습니다. 메디케어는 2025년에 ASC에 대한 환급액을 3.8% 인상하여, 공급망 비용 상승에도 불구하고 복강경 수술의 경제적 여지를 확대했습니다. 로봇 수술의 워크플로우는 점유율을 확대하고 있지만, 현재는 복잡한 증례에서 수술 시간을 연장시키고 있어 혁신성과 처리 능력의 균형을 갖춘 채취 장치의 필요성이 부각되고 있습니다. 이에 대응하여, 사전에 내용물이 채워져 있고 자동으로 열리는 파우치를 제공하는 제조업체들은 ASC의 구매 결정을 좌우하는 효율성 지표를 충족하기 위해 도입의 용이성을 강조하고 있습니다. 유럽도 유사한 경향을 보이고 있으나, 순환 경제에 관한 규제 강화로 인해 차단 성능을 저해하지 않으면서 재활용이 가능한 폴리머 블렌드에 대한 관심이 높아지고 있습니다.
만성 질환으로 인한 전 세계 수술 건수 증가
세계은행의 추산에 따르면, 2024년 브라질의 수술 건수는 인구 10만 명당 4,433건으로, 이는 당뇨병, 암, 심혈관 질환과 관련된 사례 수 증가를 반영하고 있습니다. 그러나 사하라 이남 아프리카의 수술 후 사망률은 여전히 세계 평균의 2배에 달하며, 고부가가치 의료기기의 보급을 저해하는 인프라 격차가 두드러지게 나타나고 있습니다. 선진국에서는 현재 광범위한 종양 절제 수술에 대응하기 위해 배연 기능을 갖춘 씰이나 보강된 봉합선 등 회수 기능을 최적화하고 있는 반면, 저·중소득국에서는 합리적인 가격과 간편한 사용성이 우선시되고 있습니다. 이러한 임상 현장의 현실적 차이로 인해 단계적인 제품 전략이 마련되었으며, 각 제조업체는 천자 내구성을 향상시킨 고급 폴리우레탄 재질의 디자인 외에도 기존의 나일론 백도 제품 라인업에 계속 포함시키고 있습니다.
자체 개발한 적출 시스템의 높은 단가
2024년에 실시된 복강경 슬리브 위절제술에 관한 비교 연구에서는 브랜드 제품의 백과 직접 적출 간에 합병증 발생률에 통계적인 차이가 나타나지 않았으며, 이로 인해 전문 기기에 대한 가격 압박이 높아지고 있습니다. 라틴아메리카 각국의 보건부도 이러한 우려를 공유하고 있으며, 유통업체의 이익률을 압박하는 기준 가격 상한선을 부과하고 있습니다. 이에 대응하여 전 세계 공급업체들은 무균 차단 성능을 유지하면서도 더 얇은 필름 두께와 단순화된 폐쇄 토글을 특징으로 하는 가성비 제품군을 도입하고 있습니다. 아시아태평양의 병원들은 회수용 파우치와 트로카를 세트로 묶은 다년 계약을 협상하여, 규모의 경제를 활용해 단가를 낮추고 있습니다. 이러한 전략은 비용 절감의 영향을 부분적으로 상쇄하는 한편, 입증 가능한 치료 결과의 우월성을 보여줄 필요성을 더욱 강화하고 있습니다.
부문 분석
비분리형 백은 2025년 매출의 64.78%를 차지하며, 높은 처리 능력을 요구하는 환경에서 인정받는 신뢰성을 바탕으로 검체 회수 백 시장의 기반을 지탱하고 있습니다. 이 부문은 고장 모드를 최소화하는 간단한 당김줄식 개폐 기구의 이점을 누리고 있으며, 이 기능은 조작 공간이 제한된 단일 천자 부위 복강경 수술을 시행할 때 특히 유용합니다. 병원 측에서는 미리 장착된 강성 링 덕분에 파우치에 시료를 잘못 넣는 실수가 줄어들어 회전율이 향상되고 있다고 보고하고 있습니다. 분리형 제품은 시장 점유율이 35.22%에 그치지만, 외과의들이 복강 내 조작 부담을 줄여주는 단계적 적출 방식을 높이 평가함에 따라 5.01%의 연평균 성장률(CAGR)을 기록하고 있습니다. 탈착식 시스템용 검체 회수 백 시장 규모는 2026년에 1억 2,342만 달러로 추정되며, 2031년까지 1억 5,768만 달러에 달할 것으로 예측됩니다. 이는 비만 수술 및 산부인과 수술 분야에서 목표로 하는 성장을 반영한 것입니다. Applied Medical사의 ‘Inzii(R)’ 시리즈는 체강 밖으로 나오면 개구부가 다시 열리는 가이드 비즈를 통합하여, 이전의 사용 편의성 문제를 해결하는 단계적인 진전을 보여주고 있습니다. 한편, 주변부 보강 및 선택적 분리 기능을 갖춘 하이브리드 파우치가 등장하여, 정형외과 및 스포츠 의학 분야의 관절경 검사 수요를 충족시키고 있습니다. 각 제조업체는 제품 라인업의 폭과 비용 효율성 간의 균형을 맞추어야 하며, 대부분의 경우 공통 인트로듀서 플랫폼을 기반으로 한 모듈식 핸들-백 조합을 제공합니다. 시료 회수 업계에서는 폴리머 기술 혁신이 계속해서 주목받고 있으며, 환상 올레핀 공중합체 블렌드는 수술 중 가시성을 높이는 높은 투명성을 기대할 수 있지만, 현 시점에서는 고가 제품군에 속합니다. 외과의사들은 여전히 자기 폐쇄 시스템 래치의 고장을 우려하고 있으며, 견고한 실전 데이터를 통해 대체품의 신뢰성이 확인될 때까지는 비분리형 파우치가 시장 점유율의 대부분을 계속 차지할 것으로 예측됩니다.
지역별 분석
북미는 2025년에 전 세계 매출의 42.30%를 차지했습니다. 이는 견실한 보험 환급 제도와 종양학 분야의 봉쇄 지침에 대한 조기 준수로 인해 기기 이용률이 높아지고 있기 때문입니다. 2025년에 da Vinci 플랫폼의 업그레이드가 널리 도입된 것도 비뇨기과 및 일반외과 분야에서 트로카 호환 파우치에 대한 수요를 뒷받침하고 있습니다. 그러나 보험사들은 일회용 제품 지출을 억제하기 위해 DRG(진단 관련 그룹)에 기반한 종합적 심사를 실시하고 있으며, 이로 인해 가치 중심의 제품 제공이 촉진되어 공급업체들은 2025년 중반에 가격대를 단계적으로 설정한 제품 라인을 도입하게 되었습니다.
아시아태평양은 의료 투자 증가, 고령화, 그리고 2선 도시로의 복강경 수술 기술의 급속한 보급에 힘입어 연평균 성장률(CAGR) 5.89%로 성장을 주도하고 있습니다. 2025년 중국 국가의약품감독관리국(NMPA)이 보스턴 사이언티피크(Boston Scientific)사의 ‘FARAPULSE(TM)’를 승인한 것은 첨단 시스템에 대한 규제 당국의 수용 태도를 보여주는 것으로, 보완적인 회수 솔루션의 병행 도입을 뒷받침하고 있습니다. 일본과 호주에서는 가장자리에 미끄럼 방지 처리가 된 고급 파우치가 선호되는 반면, 인도, 인도네시아, 베트남에서는 기본적인 누수 방지 요건을 충족하는 비용 효율적인 나일론 백이 주류를 이루고 있습니다. 유럽에서는 조달 지침이 순환 경제 목표를 중시하고 있어 시장이 완만한 확장을 보이고 있습니다. 독일과 북유럽 국가들의 병원에서는 사용한 파우치를 산업용 원료로 전환하는 회수 체계의 시범 운영이 진행되고 있습니다. 중동에서는 걸프 지역에 대규모 로봇 수술센터에 대한 투자가 진행되고 있어, 작은 근막 개구부를 통해 비대해진 갑상선이나 신장 검체를 적출할 수 있는 대용량 백에 대한 수요로 이어지고 있습니다. 아프리카에서는 여전히 인력 부족과 수술 후 사망률이라는 과제에 직면해 있지만, 남아프리카공화국과 나이지리아의 교육 병원에서는 기증자 유래 이식 프로그램을 위한 검체 회수 시스템이 도입되고 있습니다. 라틴아메리카에서는 브라질과 멕시코를 필두로, 현지에서 제조된 파우치에 대한 세제 혜택과 민간 의료 네트워크 내 해외 브랜드의 프리미엄 제품이 공존하고 있어 도입 현황은 제각각입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, specimen retrieval bags market size in 2026 is estimated at USD 348.08 million, growing from 2025 value of USD 334.12 million with 2031 projections showing USD 427.18 million, growing at 4.18% CAGR over 2026-2031.
This report Segments the Industry Into by Type (Detachable Specimen Retrieval Bags, Non-Detachable Specimen Retrieval Bags), by Application (Gastrointestinal Surgeries, Urological Surgeries, Gynecological Surgeries, Other Applications), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Specimen Retrieval Bags Market Trends and Insights
Rising Demand for Minimally-Invasive Surgery
Ambulatory surgery centers (ASCs) expect 21% procedure growth by 2034, directly elevating demand for reliable retrieval bags that fit shortened case times . Medicare raised ASC reimbursement 3.8% in 2025, widening the economic runway for laparoscopic cases despite rising supply-chain costs. Robotic workflows gain share but currently lengthen operating times in complex cases, highlighting the need for extraction devices that balance innovation with throughput. Manufacturers responding with pre-loaded, self-opening pouches emphasize ease of deployment to satisfy efficiency metrics that dominate ASC purchasing. Europe follows a similar arc, but heightened circular-economy mandates spur interest in polymer blends that enable recycling without compromising barrier integrity.
Increasing Global Surgical Volumes from Chronic Diseases
The World Bank identifies 4,433 procedures per 100,000 people in Brazil for 2024, reflecting higher case volumes tied to diabetes, cancer, and cardiovascular disease . Yet postoperative mortality in Sub-Saharan Africa remains twice the global average, underscoring infrastructure gaps that dampen high-value device uptake. Advanced economies now tailor retrieval features-including smoke evacuation-ready seals and reinforced seams-to support extensive oncologic resections, while low- and middle-income nations prioritize affordability and straightforward usability. These diverging clinical realities create tiered product strategies, prompting manufacturers to keep legacy nylon bags in portfolios alongside premium polyurethane designs offering improved puncture resistance.
High Unit Cost of Proprietary Retrieval Systems
A 2024 comparative study on laparoscopic sleeve gastrectomy found no statistical difference in complication rates between branded bags and direct extraction, intensifying price pressure on specialized devices. Latin American health ministries echo this concern, imposing reference-pricing caps that compress distributor margins. In response, global suppliers introduce value segments featuring thinner film gauges and simplified closure toggles while preserving sterile barrier performance. Asia-Pacific hospitals negotiate multiyear tenders that bundle retrieval pouches with trocars, exploiting economies of scale to trim per-unit cost. Such strategies partially offset the restraint but reinforce the need for demonstrable outcome advantages.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Upgrade Cycle in Laparoscopic Instrumentation
- Adoption Surge in Emerging Ambulatory Surgery Centers
- Evidence Questioning Clinical Benefit Versus Glove/Direct Extraction
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-detachable bags controlled 64.78% 2025 revenue, anchoring the specimen retrieval bags market through reliability that resonates in high-throughput settings. The segment benefits from simple drawstring closure that minimizes failure modes, a feature especially valuable when adopting single-site laparoscopy where articulation space is scarce. Hospitals report fewer pouch-loading errors with pre-attached rigid rings, supporting faster turnovers. Detachable formats, despite only 35.22% share, post 5.01% CAGR as surgeons appreciate staged extraction that reduces intra-abdominal manipulations. The specimen retrieval bags market size for detachable systems is estimated at USD 123.42 million in 2026 and is projected to reach USD 157.68 million by 2031, reflecting targeted gains in bariatric and gynecologic procedures. Applied Medical's Inzii(R) line integrates guide beads that reopen the mouth once outside the cavity, illustrating incremental advances addressing earlier usability concerns. Meanwhile, hybrid pouches featuring peripheral reinforcement and optional detachment emerge, catering to orthopedic sports-medicine arthroscopy. Manufacturers must balance inventory breadth with cost efficiency, often offering modular handle-bag combinations built on a shared introducer platform. The specimen retrieval industry continues to monitor polymer innovation, with cyclic-olefin co-polymer blends promising higher clarity for intra-operative visualization though currently at premium price points. Surgeons remain wary of latch failures on magnetic closure systems, suggesting non-detachable pouches will sustain majority share until robust field data confirm alternative reliability.
Complete Report Scope:
- By Type
- Detachable Retrieval Bags
- Non-Detachable Retrieval Bags
- By Application
- Gastrointestinal Surgeries
- Urological Surgeries
- Gynecological Surgeries
- Other Surgeries (Thoracic, Bariatric, Oncology)
- By End User
- Hospitals
- Ambulatory Surgery Centers (ASCs)
- Specialty & Physician-Owned Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 42.30% of global revenue in 2025 as robust reimbursement and early compliance with oncology containment guidance ensure high device utilization. Widespread adoption of da Vinci platform upgrades in 2025 also boosts trocar-compatible pouch demand across urology and general surgery. Yet payers invoke bundled DRG reviews to curb disposable expenditure, encouraging value offerings and prompting suppliers to introduce tiered lines in mid-2025.
Asia-Pacific leads growth at 5.89% CAGR thanks to rising healthcare investment, aging demographics, and rapid diffusion of laparoscopic skills into secondary-tier cities. China's NMPA approval of Boston Scientific's FARAPULSE(TM) in 2025 signals regulatory openness to advanced systems, encouraging parallel acceptance of complementary retrieval solutions. Japan and Australia favor premium pouches with anti-slip perimeters, while India, Indonesia, and Vietnam lean on cost-efficient nylon bags that satisfy basic leakage requirements. Europe posts moderate expansion as procurement directives emphasize circular-economy goals; hospitals in Germany and the Nordics pilot take-back schemes where used pouches are converted into industrial feedstock. The Middle East invests in large robotic surgery centers in the Gulf, translating into demand for high-capacity bags capable of removing enlarged thyroid or kidney specimens through small fascial openings. Africa remains constrained by workforce shortages and postoperative mortality challenges, though teaching hospitals in South Africa and Nigeria adopt retrieval systems for donor-derived transplant programs. Latin America, led by Brazil and Mexico, shows mixed adoption as tax incentives on locally manufactured pouches coexist with foreign-branded premium offerings in private networks.
- Johnson & Johnson
- Medtronic
- Teleflex
- Applied Medical Resources
- CONMED Corp.
- B. Braun
- Grena
- LaproSurge
- Stryker
- Purple Surgical
- The Cooper Companies
- Duomed Group
- Locamed
- Microval
- EndoEvolution
- Espiner Medical
- Victor Medical Instruments
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for minimally-invasive surgery
- 4.2.2 Increasing global surgical volumes from chronic diseases
- 4.2.3 Rapid upgrade cycle in laparoscopic instrumentation
- 4.2.4 Adoption surge in emerging ambulatory surgery centers
- 4.2.5 "In-bag" morcellation standards post-2024 oncology guidelines
- 4.2.6 Circular-economy push for recyclable polymer retrieval bags
- 4.3 Market Restraints
- 4.3.1 High unit cost of proprietary retrieval systems
- 4.3.2 Evidence questioning clinical benefit versus glove / direct extraction
- 4.3.3 Low penetration of advanced MIS in low-income countries
- 4.3.4 Skills gap for robotic-assisted specimen extraction
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value - USD Million)
- 5.1 By Type
- 5.1.1 Detachable Retrieval Bags
- 5.1.2 Non-Detachable Retrieval Bags
- 5.2 By Application
- 5.2.1 Gastrointestinal Surgeries
- 5.2.2 Urological Surgeries
- 5.2.3 Gynecological Surgeries
- 5.2.4 Other Surgeries (Thoracic, Bariatric, Oncology)
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgery Centers (ASCs)
- 5.3.3 Specialty & Physician-Owned Clinics
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Johnson & Johnson (Ethicon)
- 6.3.2 Medtronic plc
- 6.3.3 Teleflex Inc.
- 6.3.4 Applied Medical Resources
- 6.3.5 CONMED Corp.
- 6.3.6 B. Braun SE
- 6.3.7 Grena Ltd.
- 6.3.8 LaproSurge
- 6.3.9 Stryker Corp.
- 6.3.10 Purple Surgical
- 6.3.11 CooperSurgical
- 6.3.12 Duomed Group
- 6.3.13 Locamed
- 6.3.14 Microval
- 6.3.15 EndoEvolution
- 6.3.16 Espiner Medical
- 6.3.17 Victor Medical Instruments
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


