|
시장보고서
상품코드
2114551
바이러스 불활성화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Viral Inactivation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
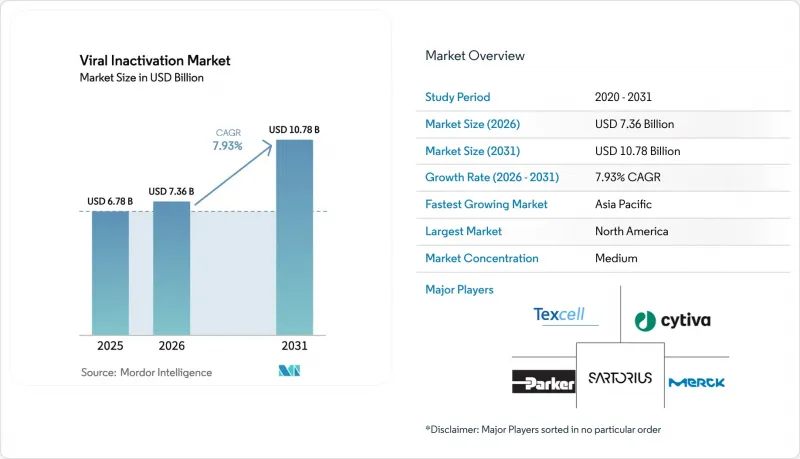
에 의하면, 바이러스 불활성화 시장 규모는 2025년에 67억 8,000만 달러로 평가되었습니다. 2026년 73억 6,000만 달러에서 2031년까지 107억 8,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.93%를 나타낼 전망입니다.
본 보고서는 방법별(용매·계면활성제 등), 제품별(바이러스 불활성화 시스템·부속품 등), 용도별(백신·치료제, 혈액·혈장 제제 등), 최종 사용자별(바이오의약품·생명공학 기업 등), 지역별(북미, 유럽,아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 바이러스 불활성화 시장 동향 및 인사이트
생물학적 제제 및 유전자 치료 파이프라인의 확대
2025년 Itvisma 및 Papzimeos가 FDA의 승인을 받은 것은 아데노연관바이러스(AAV) 치료 분야에서 복제 능력을 가진 AAV에 대한 견고한 업스트림 공정에서의 바이러스 불활성화가 필요하다는 규제 당국의 기대를 여실히 보여주었습니다. 미국 유전자·세포 치료 학회(ASGCT)의 기록에 따르면, 2025년 3분기 시점에서 2,129건의 진행 중인 유전자 치료 프로그램이 있었으며, 그중 거의 절반에서 불활성화 공정을 프로세스의 더 이른 단계로 이전시키는 생체 내 벡터가 사용되고 있었습니다. 각 스폰서사는 크로마토그래피 업스트림 공정에 전용 스키드를 도입하고 있으며, 이로 인해 설비 투자는 증가하지만 희석 공정을 생략함으로써 개발 기간을 단축하고 있습니다. 신흥 시장의 바이오시밀러 개발 기업들은 긴 공정 개발 작업을 피하기 위해 계면활성제, 완충액, 보관 용기의 사양이 패키지화된 턴키형 시약 키트를 선호하고 있습니다. ICH Q5A(R2)에서는 공정의 유사성이 입증된 경우, 플랫폼형 바이러스 제거 데이터의 제출이 허용되어 프로그램별 검증 부담이 경감되고 있습니다.
바이러스 오염에 의한 리콜 사례 증가
FDA는 2024년부터 2025년에 걸쳐 바이러스 안전성에 미비점이 확인됨에 따라, Coherus사, Scholar Rock사 및 여러 CAR-T 제약사에 대해 완전 답변 요청서(CRL) 및 경고장을 발부했습니다. 이러한 조치를 계기로, 설령 단일 공정만으로 대수 감소 목표를 달성할 수 있는 경우라 하더라도, 용매·세제 처리와 낮은 pH 유지 또는 나노 여과를 결합한 이중 직교 불활성화 방식이 널리 채택되게 되었습니다. 또한, 시판 후 조사에서 파르보바이러스 B19의 DNA가 미량 검출됨에 따라 혈장 분획 제조업체에 대한 감시가 더욱 엄격해졌으며, 유럽의약품청(EMA)은 2024년에 문서화 요건을 강화했습니다. 이에 대해 제조업체들은 세제 처리 시간을 연장하고, 비봉투형 바이러스 대책으로 UV-C 배리어를 추가하는 등의 조치를 취했습니다. 이러한 일련의 사건들은 전반적으로 생물학적 제제 포트폴리오 전체에 걸쳐 검증된 다단계 제거 전략의 확립이 필수적임을 다시 한번 부각시켰습니다.
첨단 불활성화 인프라에 수반되는 고액의 설비 투자(CAPEX)
관류형 바이오리액터와 연동되는 인라인 시스템의 비용은 라인당 150만-300만 달러에 달하여, 인도나 브라질의 소규모 CDMO에게는 극복하기 어려운 장벽이 되고 있습니다. 삼성바이오로직스가 21억 달러를 투자한 손도(Sondo) 사업장에는 전용 바이러스 불활성화 시설이 구축되었지만, 중견 기업들은 자본 지출을 줄이기 위해 기존 반응조를 개조하거나 사이클 시간 연장을 수용하고 있습니다. 열 불활성화용 파스퇴라이저 1대당 가격이 80만 달러를 초과하고, 혈장 분획 장치는 대개 6-8대를 병렬로 가동해야 하기 때문에 공정 분석 업그레이드에 사용되어야 할 자금이 묶이게 됩니다. 유전자 치료제 생산 거점도 유사한 경제적 과제에 직면해 있지만, 배치 규모가 작아 투자 자본 수익률이 낮아지면서 도입 속도가 둔화되고 있습니다.
부문별 분석
2025년, 용매 및 계면활성제 처리는 4시간의 불활성화 시간대와 혈장 풀에서의 확고한 사용에 힘입어 바이러스 불활성화 시장 점유율 46.71%를 유지했습니다. 그러나 저pH 조절법은 항체 제조 라인에서 프로테인 A 포집 후 공정에 원활하게 통합됨에 따라 바이러스 불활성화 시장 전체를 상회하는 연평균 성장률(CAGR) 11.48%를 나타낼 것으로 예측됩니다. 열 살균법은 많은 재조합 단백질이 50℃ 이상에서 변성되기 때문에 생물 제제 처리량의 15% 미만에 그치며, 여전히 틈새 시장으로 남아 있습니다. 나노여과 및 UV-C는 비엔벨로프 바이러스에 대한 툴킷을 보완하는 기술이지만, 더 큰 시장 점유율을 확보하기 위해서는 추가적인 검증이 필요합니다.
용매·계면활성제 처리가 우위를 유지하고 있는 배경에는 2만-5만 리터의 혈장 풀에서 HIV, HBV, HCV를 제거해 온 실적을 규제 당국이 신뢰하고 있다는 점도 반영되어 있습니다. 하지만 EU에서 Triton X-100 사용이 금지됨에 따라 새로운 계면활성제를 사용한 재인증이 요구되어, 프로젝트 일정이 1년 연장되는 사태가 발생하고 있습니다. 저pH 환경에서 작업하는 사용자들은 화학 물질을 전혀 대체하지 않고, 대신 완충액 조정에 의존하고 있습니다. AAV 및 렌티바이러스 제조 분야에서 나노여과 기술이 점차 보급되고 있습니다. 2024년, Planova사의 카트리지는 마우스 미세바이러스를 6로그 제거함을 입증했으며, 이에 따라 여러 CDMO가 중복성을 확보하기 위해 20nm 필터와 pH 유지 기술을 결합하기 시작했습니다.
2025년에는 키트 및 시약이 매출의 39.23%를 차지했습니다. 그러나 일회용 바이러스 불활성화 시스템은 전체 제품 중 가장 높은 연평균 성장률(CAGR) 12.23%를 나타낼 것으로 예측됩니다. Cytiva사의 FlexFactory와 Sartorius사의 일회용 믹서는 세척 검증 시간을 몇 주에서 몇 시간으로 단축하여, CDMO가 제조 캠페인을 신속하게 전환할 수 있도록 지원합니다.
아시아의 바이오시밀러 제조업체들이 적극적인 가격 정책을 펼치고 있어 소모품의 이익률은 여전히 압박을 받고 있으며, 공급업체들은 세정제를 사전 인증된 튜브나 백과 세트로 판매하고 있습니다. ICH Q5A(R2)에 따라 스폰서는 정상 상태에서 바이러스 제거를 문서화해야 할 의무가 부여됨에 따라, 검증 서비스 매출이 증가하고 있습니다. Charles River사와 Texcell사는 2025년에 300건 이상의 스파이크 시험을 완료할 예정이며, 전문 지식의 아웃소싱 추세가 두드러지고 있습니다. UV-C 챔버나 나노 여과 하우징과 같은 부수적인 제품은 틈새 시장을 차지할 뿐이지만, 위험 프로파일에서 비봉피 바이러스가 주류를 이루는 상황에서는 그 중요성이 커지고 있습니다.
지역별 분석
북미는 2025년 매출의 43.64%를 차지했습니다. 이는 유전자 치료 개발 기업이 밀집해 있다는 점과, 2024년부터 2025년에 걸쳐 오염 관리 미비 사항에 대해 여러 차례 경고장을 발부하며 강경한 태도를 보인 FDA의 존재가 배경에 있습니다. FDA의 이러한 입장으로 인해, 단일 방법으로도 약전 기준을 충족하는 경우라도 후원사는 두 가지 상호 보완적인 불활성화 기법을 병용해야 합니다. 캐나다와 멕시코의 기여도는 낮지만, 국경을 넘는 공급망을 유지하기 위해 프로토콜을 미국 기준에 맞추고 있습니다. 벤처 캐피털은 매사추세츠주와 캘리포니아주의 바이러스 벡터 생산 능력에 대한 자금 지원을 지속하고 있어, 이 지역의 우위를 더욱 공고히 하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 13.16%를 나타낼 것으로 예측됩니다. 한국의 우대 조치와 삼성바이오로직스의 21억 달러 규모 확장 계획이 이 지역의 성장세를 뒷받침하는 한편, 우시바이오로직스의 싱가포르 시설 확장으로 동남아시아 임상 거점 근처에 바이러스 벡터 생산 능력이 확보될 것입니다. 인도의 Biocon과 Syngene은 EU 및 미국의 수출 기준을 충족하기 위해 다운스트림 공정을 저pH 유지 기능이 있는 방식으로 개조하고 있습니다. 중국 국가약품감독관리국(NMPA)은 2025년에 ICH Q5A(R2)를 채택하여 플랫폼형 바이러스 제거 접근법의 도입을 가속화했습니다. 일본의 의약품 및 의료기기 종합기구(PMDA)는 2024년에 지침을 조화시켜 다지역 시험의 검증 주기를 단축했습니다.
독일에서는 Sartorius사가 중요한 일회용 기기를 생산하고 있는 반면, 영국에서는 2025년에 네레이드 시험이 완료되어 내분비계에 안전한 용매·세제법이 확립되었습니다. 프랑스와 이탈리아의 혈장 네트워크에서는 용매 및 세정법에 열처리를 결합한 워크플로가 계속되고 있는 반면, 스페인의 바이오시밀러 제조업체는 저pH 법에 의존하고 있습니다. 스위스와 북유럽 국가들은 위탁 시험 서비스와 특수 필터를 공급하고 있습니다. 중동 및 아프리카에서는 혈장 분획 기술에 대한 투자가 점진적으로 진행되고 있습니다. 걸프협력회의(GCC)는 지역 자급자족을 목표로 하고 있지만, 완제품 면역글로불린의 대부분은 여전히 수입에 의존하고 있습니다. 남미는 자금 면에서 제약을 겪고 있으며, 브라질과 아르헨티나는 기존의 용매·계면활성제 방식에 따른 생산 라인을 유지하고 있어 트리톤 X-100의 대체 사용을 의무화하지는 않고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the viral inactivation market size was valued at USD 6.78 billion in 2025 and is estimated to grow from USD 7.36 billion in 2026 to reach USD 10.78 billion by 2031, at a CAGR of 7.93% during the forecast period (2026-2031).
This report is Segmented by Method (Solvent-Detergent, and More), Product (Viral Inactivation Systems & Accessories, and More), Application (Vaccines & Therapeutics, Blood & Plasma Products, and More), End-User (Biopharma & Biotechnology Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Viral Inactivation Market Trends and Insights
Expansion of Biologics & Gene-Therapy Pipelines
FDA approvals of Itvisma and Papzimeos in 2025 highlighted the regulatory expectation that adeno-associated virus (AAV) therapies demonstrate robust upstream viral inactivation against replication-competent AAV. The American Society of Gene and Cell Therapy documented 2,129 active gene-therapy programs in Q3 2025, nearly half of which used in vivo vectors that shift inactivation earlier in the process. Sponsors are installing dedicated skids upstream of chromatography, which raises capital outlays but compresses timelines by eliminating dilution steps. Biosimilar developers in emerging markets favor turnkey reagent kits that package detergent, buffer, and hold-vessel specifications to sidestep lengthy process-development work. ICH Q5A(R2) now allows platform viral clearance data when process similarity is proven, reducing the per-program validation burden.
Rising Incidence of Viral-Contamination Recalls
The FDA issued Complete Response Letters and warning letters to Coherus, Scholar Rock, and multiple CAR-T producers during 2024-2025 after detecting shortcomings in viral safety. These actions triggered the widespread adoption of dual orthogonal inactivation, which combines solvent-detergent treatment with a low-pH hold or nanofiltration, even when one step alone meets log-reduction targets. Plasma fractionators faced extra scrutiny after trace amounts of parvovirus B19 DNA were detected in post-market surveillance, prompting the European Medicines Agency to tighten documentation requirements in 2024. Manufacturers responded by extending detergent hold times and adding UV-C barriers for non-enveloped viruses. Collectively, these events reinforced the imperative for validated, multi-step clearance strategies across biologics portfolios.
High CAPEX for Advanced Inactivation Infrastructure
Inline systems that couple with perfusion bioreactors cost between USD 1.5 million and USD 3 million per line, a hurdle that small CDMOs in India and Brazil struggle to clear. Samsung Biologics' USD 2.1 billion Songdo outlay covered dedicated viral-inactivation suites, yet mid-tier firms retrofit legacy vessels and accept longer cycles to hold capital spending down. Heat-inactivation pasteurizers exceed USD 800,000 each, and plasma fractionators often run six to eight units in parallel, tying up cash that could be used to fund process analytics upgrades. Gene-therapy sites face similar economic challenges, but with smaller batch sizes, which dilutes the return on invested capital and slows adoption.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Global Regulatory Mandates for Viral Safety
- Shift Toward Single-Use Bioprocessing Platforms
- Complex & Lengthy Validation / Regulatory Approval Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solvent-detergent processing retained 46.71% of the viral inactivation market share in 2025, underpinned by its four-hour inactivation window and entrenched use in plasma pools. Low-pH adjustment, however, is forecast to post an 11.48% CAGR, outpacing the overall viral inactivation market by integrating seamlessly after protein-A capture in antibody lines. Heat-pasteurization stays niche at <15% of biologic volumes because many recombinant proteins denature above 50 °C. Nanofiltration and UV-C round out the toolkit for non-enveloped viruses but await broader validation before capturing a larger share.
The solvent-detergent's strength also reflects regulators' confidence in its track record of eliminating HIV, HBV, and HCV from plasma pools ranging from 20,000 to 50,000 liters. Still, the EU ban on Triton X-100 forces requalification with new surfactants, stretching project timelines by a year. Low-pH users avoid chemical substitutions altogether, relying instead on buffer adjustments. Nanofiltration is rising in AAV and lentiviral manufacture; Planova cartridges demonstrated 6-log removal of minute virus of mice in 2024, prompting several CDMOs to pair 20-nm filters with pH holds for redundancy.
Kits and reagents accounted for 39.23% of revenue in 2025; however, single-use viral-inactivation systems are projected to grow at a 12.23% CAGR, the fastest among all products. Cytiva's FlexFactory and Sartorius single-use mixers compress cleaning validation from weeks to hours, allowing CDMOs to swing quickly between campaigns.
Consumable margins remain under pressure because biosimilar producers in Asia price aggressively, leading suppliers to bundle detergents with pre-qualified tubing and bags. Validation-service revenue is climbing as ICH Q5A(R2) obliges sponsors to document viral clearance during steady state. Charles River and Texcell completed over 300 spiking studies in 2025, marking a shift toward outsourced expertise. Ancillary products, such as UV-C chambers and nanofiltration housings, occupy smaller niches but gain relevance where non-enveloped viruses dominate the risk profile.
Complete Report Scope:
- By Method
- Solvent-Detergent
- Low-pH Adjustment
- Pasteurization / Heat
- Other Methods
- By Product
- Viral Inactivation Systems & Accessories
- Kits & Reagents
- Validation & Testing Services
- Other Products
- By Application
- Vaccines & Therapeutics
- Blood & Plasma Products
- Cellular & Gene-Therapy Products
- Other Applications
- By End-User
- Biopharma & Biotechnology Companies
- Contract Development & Manufacturing Organizations (CDMOs)
- Contract Research Organizations (CROs)
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 43.64% of 2025 revenue, driven by a dense cluster of gene-therapy developers and an assertive FDA that issued multiple warning letters regarding contamination-control lapses between 2024 and 2025. The agency's stance compels sponsors to deploy dual orthogonal inactivation even when single methods satisfy pharmacopeial benchmarks. Canada and Mexico contribute lower volumes, but they align their protocols with U.S. standards to preserve cross-border supply chains. Venture capital continues to fund viral-vector capacity in Massachusetts and California, reinforcing regional dominance.
Asia-Pacific is forecast to register a 13.16% CAGR to 2031. Korean incentives and Samsung Biologics' USD 2.1 billion expansion underpin regional momentum, while WuXi Biologics' Singapore build-out delivers viral-vector capability near Southeast Asian clinical hubs. India's Biocon and Syngene retrofit downstream trains with low-pH holds to meet EU and U.S. export standards. China's NMPA adopted ICH Q5A(R2) in 2025, accelerating uptake of platform viral-clearance approaches. Japan's PMDA harmonized guidance in 2024, shortening validation cycles for multiregional trials.
Germany hosts key single-use hardware output from Sartorius, while the United Kingdom completed Nereid trials in 2025, securing an endocrine-safe solvent-detergent path. France and Italy's plasma networks continue solvent-detergent plus heat workflows, whereas Spain's biosimilar producers lean on low-pH alternatives. Switzerland and the Nordics supply contract testing and specialized filters. The Middle East and Africa invest gradually in plasma fractionation; the Gulf Cooperation Council aims for regional self-sufficiency but still imports most finished immunoglobulin. South America faces capital constraints; Brazil and Argentina maintain legacy solvent-detergent lines and have yet to mandate the substitution of Triton X-100.
- Asahi Kasei Medical
- Catalent
- Charles River
- Clean Cells
- Cygnus Technologies
- Cytiva
- Getinge
- Lonza Group
- Meissner Filtration
- Merck
- Pall
- Parker Hannifin
- Rad Source Technologies
- Repligen
- Sartorius
- Texcell
- Thermo Fisher Scientific
- Vironova
- Wuxi Biologics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Biologics & Gene-Therapy Pipelines
- 4.2.2 Rising Incidence of Viral-Contamination Recalls
- 4.2.3 Stringent Global Regulatory Mandates for Viral Safety
- 4.2.4 Shift Toward Single-Use Bioprocessing Platforms
- 4.2.5 Phase-Out of Triton X-100 Accelerating Alternative Chemistries
- 4.2.6 AI-Enabled Real-Time Inline Viral-Safety Analytics
- 4.3 Market Restraints
- 4.3.1 High CAPEX for Advanced Inactivation Infrastructure
- 4.3.2 Complex & Lengthy Validation / Regulatory Approval Cycles
- 4.3.3 Supply-Chain Volatility for GMP-Grade Detergents & Filters
- 4.3.4 Bioprocess Integration Challenges with Continuous Manufacturing
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Method
- 5.1.1 Solvent-Detergent
- 5.1.2 Low-pH Adjustment
- 5.1.3 Pasteurization / Heat
- 5.1.4 Other Methods
- 5.2 By Product
- 5.2.1 Viral Inactivation Systems & Accessories
- 5.2.2 Kits & Reagents
- 5.2.3 Validation & Testing Services
- 5.2.4 Other Products
- 5.3 By Application
- 5.3.1 Vaccines & Therapeutics
- 5.3.2 Blood & Plasma Products
- 5.3.3 Cellular & Gene-Therapy Products
- 5.3.4 Other Applications
- 5.4 By End-User
- 5.4.1 Biopharma & Biotechnology Companies
- 5.4.2 Contract Development & Manufacturing Organizations (CDMOs)
- 5.4.3 Contract Research Organizations (CROs)
- 5.4.4 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Asahi Kasei Medical
- 6.3.2 Catalent Inc.
- 6.3.3 Charles River Laboratories
- 6.3.4 Clean Cells
- 6.3.5 Cygnus Technologies
- 6.3.6 Cytiva (Danaher Corporation)
- 6.3.7 Getinge AB
- 6.3.8 Lonza Group
- 6.3.9 Meissner Filtration
- 6.3.10 Merck KGaA
- 6.3.11 Pall Corporation
- 6.3.12 Parker Hannifin Corp
- 6.3.13 Rad Source Technologies
- 6.3.14 Repligen Corporation
- 6.3.15 Sartorius AG
- 6.3.16 Texcell SA
- 6.3.17 Thermo Fisher Scientific Inc.
- 6.3.18 Vironova AB
- 6.3.19 WuXi Biologics
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment