|
시장보고서
상품코드
2114606
열성형 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Thermoform Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
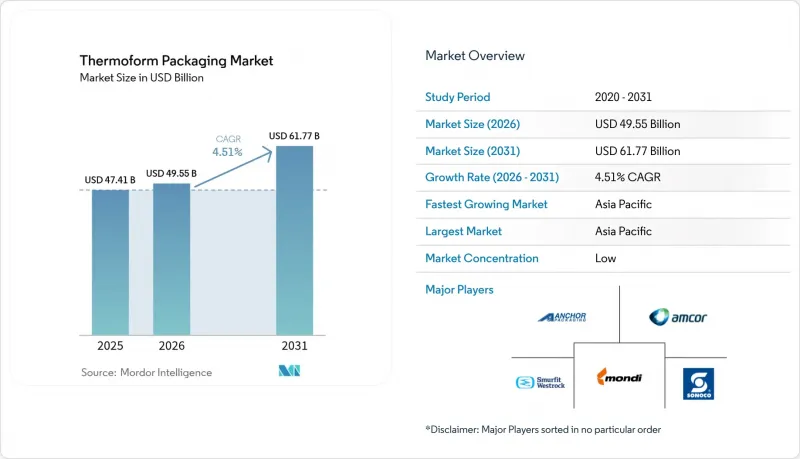
에 의하면, 2026년 열성형 포장 시장 규모는 495억 5,000만 달러로 추정되고 2025년 474억 1,000만 달러에서 확대해, 2031년에는 617억 7,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.51%로 성장할 것으로 전망됩니다.
본 보고서는 소재(플라스틱, 종이 및 판지, 알루미늄, 바이오 폴리머), 제품 유형(블리스터, 클램쉘, 트레이, 컵),포장 두께(200 Mm 이하, 200-500 Mm, 500 Mm 이상), 최종 사용자 산업(식품, 의약품, 퍼스널케어, 가전제품), 기술(진공, 가압, 기계식, 플러그 어시스트 성형), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시됩니다.
세계의 열성형 포장 시장 동향 및 인사이트
단일 소재 재활용 가능 트레이에 대한 수요 급증
순환형 경제 규제에 따라 각 컨버터 기업들은 가정 쓰레기 분리 수거 시험을 통과하는 PET 또는 PE만으로 구성된 트레이 구조로 전환하고 있습니다. 예를 들어, Graphic Packaging International의 Ecoflex PET 제품 라인은 냉장 식품의 상단 밀봉 무결성을 유지하면서 EU의 2030년 재활용 가능성 요건을 충족합니다. 유럽의 환경 조정 요금 인하와 브랜드 소유자의 노력이 맞물리면서, 다층 차단 기능을 재현하기 위해 필요한 벽 두께 증가에도 불구하고 비즈니스 타당성이 강화되고 있습니다. ExxonMobil과 Alpine은 공동으로 9회의 재활용 주기를 거친 후에도 산소 차단성을 유지하는 전 PE 열성형 제품의 실증에 성공하며, 재료 과학의 진보를 입증했습니다.
신선 식재료 키트 배송 스타트업의 성장
HelloFresh 및 동종 업계 플랫폼들은 주간 제공 식사 수를 수천만 식 규모로 확대하고 있으며, 이에 따라 포장 업체들은 며칠에 걸친 운송 중 신선도 유지를 최적화하고, 무게를 줄이며, 탄소 배출 목표를 달성해야 할 필요성이 대두되고 있습니다. 차단성을 높인 폴리프로필렌 트레이와 재활용 가능한 필름 뚜껑을 결합한 제품이 보급되고 있는 한편, 진공 스킨 포장은 액체 누출을 방지하고 유통기한을 연장합니다. 뚜껑에 내장된 온도 센서나 QR 코드를 통한 원산지 태그는 새로운 차별화 요인으로 부상하고 있으며, 프리미엄 가격 책정을 뒷받침하고 있습니다.
EU 및 북미의 플라스틱 사용세 도입 가속화
2024년에는 이탈리아가 버진 폴리머에 대해 1kg당 0.45유로의 과세를 도입하여 영국의 재생재 함유세에 합류했습니다. 이로 인해 재료 배합에 재생재가 30% 이상 포함되지 않는 한, 가공업체의 이익률은 압박을 받고 있습니다. 영국의 등록 기업들은 도입 후 18개월 동안 2억 파운드 이상을 납부했으며, 이는 이 세제가 미치는 재정적 영향이 얼마나 큰지를 여실히 보여주고 있습니다.
부문별 분석
플라스틱은 2025년 매출의 62.07%를 차지하며, 열성형 포장 시장에서 가장 큰 점유율을 기록했습니다. rPET 트레이와 PP 컵은 차단 성능 및 생산 라인 효율성 측면에서 경쟁력을 유지하고 있는 반면, 원료 수지의 가격 급등으로 인해 재생 재료의 경제성이 향상되고 있습니다. PLA 블렌드를 필두로 한 바이오 폴리머는 연평균 성장률(CAGR) 8.21%로 성장을 지속하고 있으며, EU의 퇴비화 가능 표시와 같은 정책적 우대 조치의 혜택을 받고 있습니다. 대규모 외식 체인점이 저탄소 포장 계약을 체결함에 따라, 바이오베이스 등급의 열성형 포장 시장 규모는 2025-2030년 3배로 확대될 것으로 예측됩니다. 다만, 원료 공급의 안정성이나 60°C를 초과하는 열변형 온도와 관련된 과제 등, 규모 확대의 장벽은 여전히 남아 있습니다.
대조적으로, 판지 열성형 제품은 식물 유래 코팅을 통해 내유성을 부여할 수 있는 베이커리 제품이나 즉석식사 용기 뚜껑과 같은 분야에서 틈새 시장을 개척하고 있습니다. 알루미늄은 경량성과 높은 강도 비율 덕분에 항공기 기내식 용도로 여전히 사용되고 있지만, 비용 변동과 재활용에 따른 에너지 부하로 인해 그 점유율은 서서히 감소하고 있습니다. Cascades의 100% rPET 롤 엣지 트레이는 재활용 함량 제고 요건을 충족하기 위해 기존 폴리머가 어떻게 진화하고 있는지를 여실히 보여줍니다.
블리스터 팩은 일반의약품 및 영양보충제 분야에서 위조 방지 기능과 1회 투여량의 정확성을 활용하여 2025년 매출의 37.05%를 차지했습니다. 판매량 증가는 고령화 사회 및 엄격한 의약품 규정 준수와 연동되어 있습니다. 한편, 트레이와 뚜껑은 연평균 성장률(CAGR) 7.6%로 가장 빠르게 성장하고 있으며, 밀키트 기업들이 분량이 조절된 단백질 및 농산물 구획을 표준화하고 있습니다. 트레이 열성형 포장 시장 규모는 슈퍼마켓 델리 코너가 EPS에서 투명 PET로 전환함에 따라 2026년에는 156억 달러를 돌파했습니다. 가압 성형된 2실 구조의 인서트는 2차 골판지 상자를 사용하지 않고 진열 효과를 높이고자 하는 프리미엄 제과 제조업체들로부터 지지를 받고 있습니다.
블리스터 포장 혁신 기업들은 진위 확인을 위해 디지털 워터마크를 도입하고 있는 반면, 트레이의 경우 EPR(확대 생산자 책임) 비용을 절감하기 위해 재활용을 고려한 설계에 대한 감사가 이루어지고 있습니다. 재밀봉이 가능한 클립식 뚜껑은 소비자의 편의성을 높이고 재사용을 촉진할 뿐만 아니라, 브랜드의 폐기물 감축 노력과도 부합합니다.
지역별 분석
아시아태평양이 열성형 포장 시장에서 차지하는 39.76%의 점유율은 중국과 인도의 수직 통합형 수지 허브와 가처분 소득 증가에 힘입어 강화되고 있습니다. 정부 주도의 제약 단지와 2선 도시에서의 전자상거래 급성장이 이 지역의 연평균 성장률(CAGR) 7.05%를 뒷받침하고 있습니다. 인도의 가공업체들은 확대 생산자 책임(EPR) 크레딧을 활용하여 PET 플레이크 공장에 공동 투자하고, 패스트푸드점을 위한 rPET 트레이 생산량을 늘리고 있습니다.
북미는 성숙한 시장이지만, 혁신에 대한 수요가 높은 상황입니다. 미국의 4개 주에서는 EPR법이 제정되어 브랜드 소유주에게 사용 후 제품 회수 및 처리 프로그램에 자금을 지원해야 할 의무가 부과되고 있습니다. 이에 따라 각 변환 업체들은 분리 수거 작업을 용이하게 하기 위해 착색제를 사용하지 않은 PET 및 디지털 워터마크 기술의 시범 도입을 추진하고 있습니다. FDA(미국 식품의약국)의 첨단 제조 인센티브로 인해 국내 블리스터 포장 생산 능력이 확대되어, 중요한 의약품 포장의 국내 생산 복귀가 촉진되고 있습니다.
유럽에서는 가장 엄격한 규제가 시행되고 있으며, 2030년 재활용 가능성에 관한 규정과 단계적인 재생재 함유율 기준에 따라 소재의 재조성이 급속히 진행되고 있습니다. 이탈리아와 스페인의 플라스틱 과세로 인해 버진 폴리머 비용은 최대 550달러/톤 상당으로 상승했으며, 재활용 가능한 PP 및 PET 블렌드의 채택이 가속화되고 있습니다. Faerch가 식품 트레이에 연간 10만 톤의 사용 후 PET를 포함시키겠다고 약속한 것은 해당 지역 특유의 순환 경제 규모 확대를 상징하는 사례입니다.
라틴아메리카와 중동 및 아프리카는 시장 규모 면에서는 뒤처져 있지만, 도시화와 식품 소매업의 현대화를 배경으로 안정적인 한 자릿수 중반의 성장률을 보이고 있습니다. 현지 기업들은 수입 관세를 회피하고 새롭게 도입되는 지역 폐기물 정책을 준수하기 위해 rPET 시트 압출 생산 능력에 투자하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, thermoform packaging market size in 2026 is estimated at USD 49.55 billion, growing from 2025 value of USD 47.41 billion with 2031 projections showing USD 61.77 billion, growing at 4.51% CAGR over 2026-2031.
This report is Segmented by Material (Plastic, Paper, Aluminum, Bio-Based Polymers), Product Type (Blisters, Clamshells, Trays, Cups), Packaging Thickness (Up To 200 Mm, 200-500 Mm, Above 500 Mm), End-User Industry (Food, Pharmaceuticals, Personal Care, Electronics), Technology (Vacuum, Pressure, Mechanical, Plug-Assist Forming), and Geography. Market Forecasts in Value (USD).
Global Thermoform Packaging Market Trends and Insights
Surge in demand for mono-material recyclable trays
Circular-economy rules are steering converters toward PET- or PE-only tray structures that pass curbside sortation tests. Graphic Packaging International's Ecoflex(TM) PET line, for instance, meets the EU 2030 recyclability requirement while preserving top-seal integrity for chilled foods. Lower eco-modulated fees in Europe, coupled with brand owner commitments, boost the business case despite thicker walls needed to replicate multilayer barriers. ExxonMobil and Alpine jointly validated all-PE thermoforms that sustain oxygen barriers after nine recycling loops, underscoring material science advances.
Growth of fresh meal-kit delivery startups
HelloFresh and peer platforms have scaled to tens of millions of weekly servings, forcing packagers to optimize freshness over multiday transit, curb mass and hit carbon targets. Barrier-enhanced polypropylene trays paired with recyclable film lidding are proliferating, while vacuum-skin formats suppress drip loss and extend shelf life. Temperature sensors and QR-based provenance tags embedded into lids are emerging differentiators, fostering premium pricing.
Accelerating plastic-use taxation in EU and North America
Italy's levy of EUR 0.45/kg on virgin polymers joined the UK's recycled-content tax in 2024, slicing converter margins unless material mixes exceed 30% recyclate. Registered UK businesses remitted more than GBP 200 million in the first 18 months, highlighting fiscal bite.
Other drivers and restraints analyzed in the detailed report include:
- Per-capita rise in single-serve convenience foods
- Shift from glass vials to thermoform blister packs in injectables
- Sporadic supply of medical-grade PP and PET sheets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics delivered 62.07% of 2025 sales, equating to the largest slice of the thermoform packaging market. rPET trays and PP cups stay competitive on barrier metrics and line efficiency, while price spikes in prime resin strengthen recyclate economics. Bio-based polymers, led by PLA blends, chart an 8.21% CAGR and benefit from policy carrots such as EU compostability labeling. The thermoform packaging market size for bio-based grades is projected to triple between 2025 and 2030 as high-volume food service chains lock in low-carbon packaging contracts. Scaling hurdles persist around feedstock supply continuity and heat-distortion thresholds beyond 60 °C.
In contrast, paperboard thermoforms carve niche demand in bakery and ready-meal lids where grease resistance can be engineered with plant-based coatings. Aluminum retains service in airline catering owing to lightweight-to-strength ratios but its share inches downward on cost volatility and recycling energy load. Cascades' 100% rPET rolled-edge tray underlines how incumbent polymers evolve to satisfy rising recycled-content quotas.
Blister packs captured 37.05% of 2025 turnover, leveraging tamper evidence and unit-dose accuracy for OTC medicines and nutraceuticals. Volume growth aligns with ageing demographics and strict drug compliance rules. Trays and lids, however, are the fastest climber at 7.6% CAGR, with meal-kit firms standardizing portioned protein and produce cells. The thermoform packaging market size for trays surpassed USD 15.6 billion in 2026, supported by supermarket delis converting from EPS to clear PET. Pressure-formed dual-compartment inserts appeal to premium confectionery seeking elevated shelf presence without secondary cartons.
Blister innovators embed digital watermarking for authentication, while trays undergo design-for-recycling audits to shave EPR fees. Recloseable clip-on lids boost consumer convenience, encouraging reuse and aligning with brand waste-reduction pledges.
Complete Report Scope:
- By Material
- Plastic
- Paper and Paperboard
- Aluminum
- Bio-based/Biodegradable Polymers
- By Product Type
- Blisters
- Clamshells
- Trays and Lids
- Cups and Bowls
- Other Product Type
- By Packaging Thickness
- Up to 200 µm
- 200-500 µm
- Above 500 µm
- By End-user Industry
- Food and Beverage
- Pharmaceuticals and Medical
- Personal Care and Cosmetics
- Consumer Electronics
- Other End-user Industry
- By Thermoforming Technology
- Vacuum Forming
- Pressure Forming
- Mechanical Forming
- Plug-Assist Forming
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific's 39.76% hold on the thermoform packaging market is fortified by vertically integrated resin hubs in China and India coupled with rising disposable incomes. Government-led pharma parks and e-commerce booms in tier-2 cities sustain a 7.05% regional CAGR. Indian converters leverage Extended Producer Responsibility credits to co-invest in PET flake plants, boosting rPET tray output for quick-service restaurants.
North America presents a mature but innovation-hungry landscape. Four US states have enacted EPR statutes compelling brand owners to bankroll end-of-life programs; converters thus pilot colorant-free PET and digital watermarks to ease sorting. FDA advanced manufacturing incentives accelerate domestic blister capacity, supporting on-shoring of critical drug packaging.
Europe enforces the strictest regime, with the 2030 recyclability rule and graduated recycled-content thresholds pushing rapid material reformulation. Plastic levies in Italy and Spain raise virgin-polymer costs by as much as USD 550/tonne equivalent, hastening adoption of recyclable PP and PET blends. Faerch's pledge to incorporate 100,000 t/yr of post-consumer PET into food trays exemplifies region-specific circularity scale-ups.
Latin America and the Middle East & Africa trail in market size yet post stable mid-single-digit growth on back of urbanization and food retail modernization. Local players invest in rPET sheet extrusion capacity to circumvent import tariffs and adhere to emerging regional waste policies.
- Amcor PLC
- Sonoco Products Company
- International Paper
- Placon Corporation
- Display Pack Inc.
- Smurfit WestRock
- Tekni-Plex Inc.
- Anchor Packaging Inc.
- D&W Fine Pack
- Sealed Air Corporation
- Mondi Group
- Huhtamaki Oyj
- Pactiv Evergreen Inc.
- Fabri-Kal LLC
- Dart Container Corp.
- Sabert Corporation
- Genpak LLC
- Silgan Plastics
- Rompa Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in demand for mono-material recyclable trays
- 4.2.2 Growth of fresh meal-kit delivery startups
- 4.2.3 Per-capita rise in single-serve convenience foods
- 4.2.4 Shift from glass vials to thermoform blister packs in injectables
- 4.2.5 Automation lowering tooling?changeover cost (Industry 4.0 lines)
- 4.2.6 Government stimulus for on-shore pharmaceutical packaging
- 4.3 Market Restraints
- 4.3.1 Accelerating plastic-use taxation in EU and North America
- 4.3.2 Sporadic supply of medical-grade PP and PET sheets
- 4.3.3 High energy intensity vs. molded-fiber forming
- 4.3.4 Limited barrier performance for oxygen-sensitive SKUs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Plastic
- 5.1.2 Paper and Paperboard
- 5.1.3 Aluminum
- 5.1.4 Bio-based/Biodegradable Polymers
- 5.2 By Product Type
- 5.2.1 Blisters
- 5.2.2 Clamshells
- 5.2.3 Trays and Lids
- 5.2.4 Cups and Bowls
- 5.2.5 Other Product Type
- 5.3 By Packaging Thickness
- 5.3.1 Up to 200 µm
- 5.3.2 200-500 µm
- 5.3.3 Above 500 µm
- 5.4 By End-user Industry
- 5.4.1 Food and Beverage
- 5.4.2 Pharmaceuticals and Medical
- 5.4.3 Personal Care and Cosmetics
- 5.4.4 Consumer Electronics
- 5.4.5 Other End-user Industry
- 5.5 By Thermoforming Technology
- 5.5.1 Vacuum Forming
- 5.5.2 Pressure Forming
- 5.5.3 Mechanical Forming
- 5.5.4 Plug-Assist Forming
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Australia and New Zealand
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 United Arab Emirates
- 5.6.4.1.2 Saudi Arabia
- 5.6.4.1.3 Turkey
- 5.6.4.1.4 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Nigeria
- 5.6.4.2.3 Egypt
- 5.6.4.2.4 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor PLC
- 6.4.2 Sonoco Products Company
- 6.4.3 International Paper
- 6.4.4 Placon Corporation
- 6.4.5 Display Pack Inc.
- 6.4.6 Smurfit WestRock
- 6.4.7 Tekni-Plex Inc.
- 6.4.8 Anchor Packaging Inc.
- 6.4.9 D&W Fine Pack
- 6.4.10 Sealed Air Corporation
- 6.4.11 Mondi Group
- 6.4.12 Huhtamaki Oyj
- 6.4.13 Pactiv Evergreen Inc.
- 6.4.14 Fabri-Kal LLC
- 6.4.15 Dart Container Corp.
- 6.4.16 Sabert Corporation
- 6.4.17 Genpak LLC
- 6.4.18 Silgan Plastics
- 6.4.19 Rompa Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment