

|
시장보고서
상품코드
2114667
아달리무맙 제제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Adalimumab Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
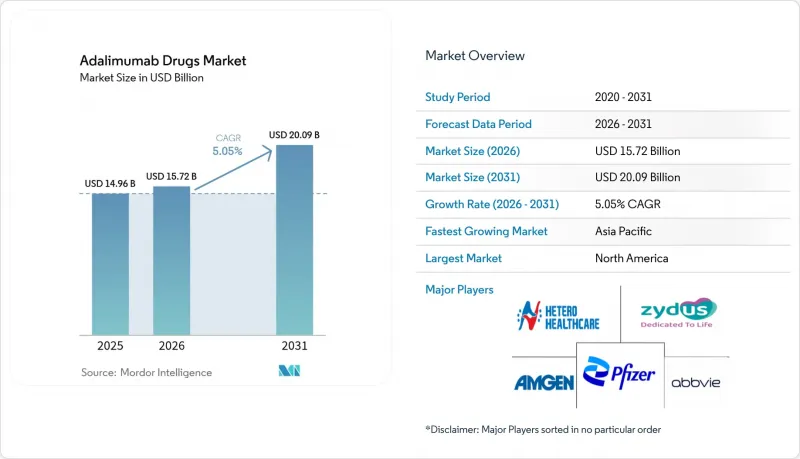
아달리무맙 제제 시장 규모는 2025년에 149억 6,000만 달러로 평가되었습니다. 2026년 157억 2,000만 달러에서 2031년까지 200억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.05%를 나타낼 전망입니다.
본 보고서는 제품 유형(생물학적 제제, 바이오시밀러), 적응증(류마티스 관절염, 건선성 관절염, 강직성 척추염, 크론병, 궤양성 대장염, 일반 건선 등),유통 채널(병원 약국, 소매 약국, 온라인 약국), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 아달리무맙 제제 시장 동향 및 인사이트
휴미라의 독점권 상실이 바이오시밀러 출시를 촉진
FDA의 일괄 승인 물결에 힘입어, 휴미라의 특허 만료 후 18개월 이내에 10종 이상의 바이오시밀러가 미국 시장에 출시되었으며, 리베이트 적용 전 가격은 최대 80% 인하되었고, 주요 PBM(의약품 혜택 관리 회사)에서 우선적으로 처방되는 바이오시밀러의 처방량은 3배로 증가했습니다. 2024년 6월에 발표된 개정된 상호교환성 지침에 따라 개발 주기가 18-24개월 단축되고, 자본 요건이 감소하며, 시장 진입 장벽이 낮아졌습니다. 심란디(Simlandi)사는 미국 조제량의 88%를 차지하는 고농도 40 mg/0.4 mL 제제에 대해 시장 최초로 상호교환성을 확보함으로써, 스폰서 기업의 가격 결정력을 일시적으로 회복시켰습니다. 그러나 이후 ‘유프리마’와 ‘하일리모즈’가 상호 대체성을 인정받으면서, 이러한 독점적 우위는 12개월 이내에 사라졌고, 가격 하락은 더욱 가속화되었습니다. 캘리포니아 블루 쉴드(California Blue Shield)의월1회 투여분 525달러 계약으로 대표되는 병행 직접 구매 모델은 구매자가 PBM의 마진을 피하고자 하는 의향을 보여줍니다.
전 세계 자가면역 질환 유병률 증가
세계 류마티스 관절염 환자 수는 연간 2-3% 증가하고 있으며, 건선 사례 수는 2020년 이후 15% 상승했고, 개발도상국에서 염증성 장질환의 진단 건수는 연간 5-7%의 속도로 증가하고 있습니다. 질병 감시 강화, 영상 진단 기술의 향상, 평균 수명의 연장이 맞물려 생물학적 제제의 대상이 되는 환자층이 확대되고 있습니다. 장기 등록 연구에 따르면, TNF-α 억제제를 조기에 투여하면 사망률이 40-50% 감소하는 것으로 밝혀졌으며, 치료 지침에서 생물학적 제제가 1차 선택제로서의 입지가 강화되고 있습니다. 아시아태평양에서는 진단이 미흡했던 환자층이, 보험 보상 제도 개혁에 따라 전문 의료에 대한 자금 지원이 확대됨에 따라 치료 대상으로 파악되기 시작하여 환자 수가 대폭 증가할 것으로 예측됩니다. 비감염성 포도막염 및 소아 특발성 관절염과 같은 새로운 적응증으로 인해 사용 영역이 더욱 확대되었으며, 경쟁하는 생물학적 제제가 존재하는 상황에서도 해당 수요가 유지되고 있습니다.
저소득 시장에서의 고가 가격 책정
많은 개발도상국에서 아달리무맙 1개월 분의 투여량만으로도 평균 가구 소득을 초과하며, 이것이 치료 중단이나 애초에 치료를 시작조차 할 수 없는 원인이 되고 있습니다. 정부 의약품 예산 중 전문 의약품에 배정되는 비율은 5% 미만이며, 임상적으로 적격한 환자 중 극히 일부만이 보험 적용을 받을 수 있습니다. 현지에서의 바이오시밀러 제조는 아직 의미 있는 가격 인하를 실현하지 못하고 있으며, 규정 준수 관련 제반 비용으로 인해 단위 비용은 원개발품 수준의 60-70%에 그치고 있습니다. 병행수입의 위험이, 본래라면 합리적인 가격을 실현할 수 있는 단계적 가격 책정 방식의 도입을 방해하고 있습니다. 체계적인 의료기술평가 프로세스가 마련되어 있지 않아, 상환위원회는 예산을 바이오의약품에 배정하는 것의 정당성을 입증하는 데 어려움을 겪고 있으며, 그 결과 접근까지의 지연이 길어지고 보급 곡선이 정체되고 있습니다.
부문별 분석
바이오시밀러의 판매량은 증가 추세를 보이고 있지만, 확고히 자리 잡은 의사 대상 선호 프로그램과 본인 부담금 보조 제도 덕분에 2025년에도 휴미라는 아달리무맙 제제 시장에서 67.62%의 점유율을 유지했습니다. 바이오시밀러에 대해 예측되는 5.62%라는 강력한 CAGR은 처방 의사의 개입 없이 약국 수준에서 대체를 허용하는 ‘호환성 승인’을 통해 지불자 측의 영향력이 강해지고 있음을 나타냅니다. 경쟁의 초점은 고농도이며 구연산염을 함유하지 않은 제제에 집중되어 있으며, 이는 미국 내 주사제의 10개 중 9개 가까이 차지하고 있습니다. 심란디의 초기 독점 기간으로 인해 실질 실현 가격은 일시적으로 상승했으나, 유프리마(Yuflima)와 같은 후발 제품들이 곧바로 이 프리미엄을 무력화시키면서 가격 하락 추세가 다시 강해졌습니다. 퀄렌트 파마슈티컬즈(Quarent Pharmaceuticals)의 자체 브랜드 플랫폼은 여러 공급처로부터의 조달을 통합하고 있으며, 이를 통해 고용주는 휴미라(Humira)의 2023년 순가격의 4분의 1 미만으로 브랜드명이 없는 아달리무맙을 조달할 수 있게 되었습니다. 전 세계적으로 볼 때, 대규모 지불 기관의 입찰에서 브랜드명이 없는 바이오시밀러는 이미 아달리무맙 제제 시장 규모의 15-20%를 차지하고 있으며, 이는 돌이킬 수 없는 상품화 추세를 보여줍니다.
각 제약사는 분자 수준의 차이가 아닌, 디바이스 생태계 및 종합적인 환자 서비스를 통해 차별화를 꾀하고 있습니다. 디지털 복약 순응도 모니터링 기능을 갖춘 전기기계식 재사용 가능 자동 주사기는 구체적인 임상적 이점을 제공하며, 이러한 통합 기능을 갖추지 않은 할인 가격의 바이오시밀러 제품에 비해 적정한 가격 프리미엄을 정당화합니다. 애브비가 새로운 작용기전-특히 ‘스카이리지’의 IL-23 억제나 ‘린복’의 JAK1 선택성-으로 전략적 전환을 꾀하고 있는 것은 아달리무맙의 매출이 감소하는 가운데 프랜차이즈의 수익을 지키기 위함입니다. 파이프라인의 미래 전망은 밝지만, 차세대 제품들의 적응증 전반에 걸친 보급으로 인해 ‘휴미라’ 수요가 부분적으로 잠식되고 있으며, 바이오시밀러의 성장 여지가 더욱 확대되고 있습니다. 승인까지의 기간을 약 2년 단축하는 규제 변경은 신규 진출기업의 의욕을 더욱 높여, 2031년까지 경쟁 심화가 지속될 것임을 확실히 하고 있습니다.
지역별 분석
북미는 2025년 매출의 55.64%를 차지했으며, 지불자 주도형 바이오시밀러 대체 규정에 따라 여전히 경쟁의 중심지 역할을 하고 있습니다. 현재 4개의 바이오시밀러가 상호 대체성이 인정되어 약국 차원의 자동적인 대체 도입이 진행되고 있으며, 브랜드 충성도 유지 기간이 단축되고 있습니다. 전문 약국 증가로 인해 견고한 콜드체인 관리와 실시간 임상 모니터링이 확보되어, 가격 협상이 격화되는 상황에서도 생물학적 제제의 이용률은 계속해서 높은 수준을 유지하고 있습니다. 그러나 투명성 확보 의무와 주 차원의 기준가 제도 관련 법안이 순가격 실현에 추가적인 압박을 가하고 있어, 제약사들은 문서화된 치료 성과 보장을 중심으로 계약 전략을 재검토해야 하는 상황에 직면해 있습니다.
유럽에서는 정교한 가치 기반 합의가 채택되어 있으며, 의료 기술 평가 기관은 피부과 중증도 척도의 개선이나 류마티스학 복합 점수를 기준으로 환급을 결정하고 있습니다. 입찰 주도형 조달로 인해 독일, 네덜란드, 프랑스에서는 바이오시밀러 보급률이 25%를 넘어섰으나, 이탈리아와 스페인에서는 처방집 갱신이 지연되면서 보급이 더딘 상황입니다. 안정적인 환자에 대한 의사의 전환에 대한 소극적인 태도는 여전히 남아 있지만, 스칸디나비아 국가들의 전국적인 전환 의무화에서는 정책 시행 후 12개월 이내에 85% 이상의 준수율이 나타났습니다. EMA(유럽의약품청)의 간소화된 바이오시밀러 심사 절차에 기반한 통합 규제 심사를 통해 신청 서류 접수가 최단 150일 만에 가능해졌으며, 기존 소요 기간보다 약 1년이 단축되었습니다.
아시아태평양은 중산층의 보험 가입률 상승과 국산 바이오시밀러를 우대하는 공공 입찰 개혁에 힘입어 연평균 성장률(CAGR) 5.71%라는 지역 최고 성장률을 기록하고 있습니다. 중국의 수량 기준 조달 라운드로 인해 아달리무브의 가격이 75% 이상 인하되었으며, 이는 단위 이익률의 축소를 상쇄하는 수요 탄력성을 창출하고 있습니다. 일본에서는 초고령화 사회가 안정적인 기본 사용량을 뒷받침하고 있으며, 호주의 의약품 급여 제도(Pharmaceutical Benefits Scheme)는 다국적 공급업체에게 매력적이고 예측 가능한 상환 주기를 보장하고 있습니다. 인도는 듀얼 트랙 시장의 대표적인 사례입니다. 도시 지역의 3차 의료 센터에서는 OECD 평균에 육박하는 도입률을 보이고 있는 반면, 지방 지역에서는 불충분한 콜드체인 인프라로 인해 공급이 제한되고 있습니다. 동남아시아 전역에서는 ASEAN에 의한 규제 조화가 추진되고 있으며, 바이오시밀러 승인을 신속화하는 것을 목표로 하고 있습니다. 이에 따라 각국의 심사 기간이 2년 이내에 통일될 가능성이 있어, 지역 전체 수요 증가가 더욱 가속화될 전망입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the adalimumab market size was valued at USD 14.96 billion in 2025 and estimated to grow from USD 15.72 billion in 2026 to reach USD 20.09 billion by 2031, at a CAGR of 5.05% during the forecast period (2026-2031).
This report is Segmented by Product Type (Biologics, Biosimilars), Indication (Rheumatoid Arthritis, Psoriatic Arthritis, Ankylosing Spondylitis, Crohn's Disease, Ulcerative Colitis, Plaque Psoriasis, and More), Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Adalimumab Drugs Market Trends and Insights
Loss of Humira Exclusivity Spurring Biosimilar Launches
A synchronized wave of FDA approvals has placed 10+ biosimilars on U.S. shelves within eighteen months of Humira's patent cliff, cutting pre-rebate prices by up to 80% and tripling prescription volume for preferred biosimilars under major PBMs. Updated interchangeability guidance issued in June 2024 shaved 18-24 months off development cycles, reducing capital requirements and lowering entry barriers. Simlandi secured first-to-market interchangeability for the high-concentration 40 mg/0.4 mL strength that covers 88% of U.S. dispenses, briefly restoring pricing leverage for its sponsors. Nevertheless, subsequent designations for Yuflyma and Hyrimoz eliminated this exclusivity buffer inside twelve months, intensifying price erosion. Parallel direct-purchase models-exemplified by Blue Shield of California's USD 525 monthly dose agreement-demonstrate purchaser appetite for bypassing PBM spreads.
Escalating Global Autoimmune Disease Prevalence
The global rheumatoid arthritis population is adding 2-3% annually, psoriasis cases have climbed 15% since 2020, and inflammatory bowel disease diagnoses in developing economies are rising by 5-7% per year. Increased disease surveillance, improved diagnostic imaging, and longer life expectancy collectively expand biologic-eligible cohorts. Long-term registries reveal 40-50% mortality reduction when TNF-a inhibitors are initiated early, reinforcing first-line biologic placement in treatment guidelines. Asia-Pacific's underdiagnosed patient pool is transitioning into treated prevalence as reimbursement reforms fund specialty care, unlocking substantive volume growth. Emerging indications such as non-infectious uveitis and juvenile idiopathic arthritis further widen usage scenarios, sustaining addressable demand despite competitive biologic classes.
Premium Pricing in Low-Income Markets
In many developing economies a single monthly adalimumab dose exceeds the average household income, leading to treatment discontinuation or complete non-initiation. Government drug budgets allocate under 5% to specialty pharmaceuticals, restricting coverage to a fraction of clinically eligible patients. Biosimilar manufacturing locally has yet to unlock meaningful discounts, with compliance overheads keeping unit costs at 60-70% of originator levels. Parallel import risks deter tiered-pricing schemes that could otherwise broaden affordability. Without structured health technology assessment pathways, reimbursement committees struggle to justify budget diversion toward biologics, elongating access latency and flattening uptake curves.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Specialty-Pharmacy Penetration in the U.S.
- Patient-Friendly Autoinjector Upgrades Enhancing Adherence
- Cold-Chain Bottlenecks in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biosimilars captured escalating volume yet Humira still held 67.62% adalimumab market share in 2025 thanks to entrenched physician preference programs and copay assistance. The vigorous 5.62% CAGR projected for biosimilars illustrates payer leverage following interchangeable approvals that authorize pharmacy-level substitution without prescriber intervention. Competitive focus centers on high-concentration, citrate-free formulations, the presentation that accounts for nearly nine in every ten U.S. injections. Simlandi's initial exclusivity window temporarily raised its net realized price, but follow-on entrants such as Yuflyma quickly nullified this premium, reinstating downward pricing momentum. Quallent Pharmaceuticals' private-label platform aggregates multisource supply, enabling employers to procure unbranded adalimumab at less than one-quarter of Humira's 2023 net price. On a global scale, unbranded biosimilars already account for 15-20% of adalimumab market size in large-payer tenders, signaling an irreversible commoditization trend.
Manufacturers pursue differentiation via device ecosystems and wrap-around patient services rather than molecular variance. Electromechanical reusable autoinjectors bundled with digital adherence monitoring offer tangible clinical benefits that justify modest price premiums over discount biosimilars lacking such integrations. AbbVie's strategic pivot toward novel mechanisms-most visibly IL-23 blockade with Skyrizi and JAK1 selectivity with Rinvoq-aims to protect franchise earnings as adalimumab revenue slides. Despite pipeline promise, cross-indication uptake of next-generation assets partially cannibalizes Humira demand, amplifying biosimilar growth headroom. Regulatory shifts that shorten approval timelines by nearly two years further embolden new entrants, ensuring sustained competitive churn through 2031.
Complete Report Scope:
- By Product Type
- Biologics (Humira)
- Biosimilars
- By Indication
- Rheumatoid Arthritis
- Psoriatic Arthritis
- Ankylosing Spondylitis
- Crohn's Disease
- Ulcerative Colitis
- Plaque Psoriasis
- Hidradenitis Suppurativa
- Juvenile Idiopathic Arthritis
- Uveitis
- Others
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 55.64% of 2025 revenue and remains the axis of competitive disruption owing to payer-driven biosimilar substitution rules. Four biosimilars now hold interchangeability status, introducing automatic pharmacy-level substitution and compressing brand loyalty cycles. Specialty-pharmacy proliferation ensures robust cold-chain stewardship and real-time clinical monitoring, supporting continued high biologic utilization despite intensified price negotiations. Yet transparency mandates and state-level reference-pricing bills apply incremental pressure on net-price realization, prompting manufacturers to refine contracting tactics around documented outcome guarantees.
Europe adopts sophisticated value-based arrangements, with health technology assessment agencies tying reimbursement to dermatology severity scale improvements or rheumatology composite scores. Tender-driven procurement has pushed biosimilar penetration above 25% in Germany, the Netherlands, and France, while Italy and Spain lag due to slower formulary updates. Physician reluctance to switch stable patients persists, though national switching mandates in Scandinavian states display adherence rates exceeding 85% within twelve months of policy enactment. Centralized regulatory reviews under the EMA's streamlined biosimilar pathway now permit dossier acceptance in as little as 150 days, shaving roughly one year off historic timelines.
Asia-Pacific records the highest regional growth at a 5.71% CAGR, fueled by rising middle-class insurance coverage and public tender reforms that favor domestically produced biosimilars. China's volume-based procurement rounds have slashed adalimumab prices by upward of 75%, igniting demand elasticity that offsets unit margin contraction. Japan's super-aged demographic underpins consistent baseline use, while Australia's Pharmaceutical Benefits Scheme guarantees predictable reimbursement cycles attractive to multinational suppliers. India exemplifies a dual-track market: urban tertiary centers exhibit adoption rates approaching OECD averages, whereas rural districts remain supply constrained by inadequate cold-chain infrastructure. Across Southeast Asia, coordinated ASEAN regulatory convergence aims to fast-track biosimilar approvals, potentially aligning national reviews within a two-year window and magnifying regional demand uplift.
- Abbvie
- Alvotech
- Amgen
- Bio-Thera Solutions Ltd.
- Biogen
- Boehringer Ingelheim Intl. GmbH
- Celltrion
- Coherus Biosciences
- Dr. Reddy's Laboratories Ltd.
- Fresenius
- Lupin
- Organon
- Pfizer
- Reliance Life Sciences Pvt. Ltd.
- Samsung Bioepis Co., Ltd.
- Sandoz Group AG
- Shanghai Henlius Biotech Inc.
- Stada Arzneimittel
- Viatris
- Zydus Lifesciences Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Loss of Humira exclusivity spurring biosimilar launches
- 4.2.2 Escalating global autoimmune disease prevalence
- 4.2.3 Increasing specialty-pharmacy penetration in the U.S.
- 4.2.4 Patient-friendly autoinjector upgrades enhancing adherence
- 4.2.5 Value-based contracting gaining traction in Europe
- 4.2.6 Government tender reforms in Asia-Pacific boosting biosimilar uptake
- 4.3 Market Restraints
- 4.3.1 Premium pricing of biologics in low-income markets
- 4.3.2 Interchangeability hurdles for biosimilars in the U.S.
- 4.3.3 Cold-chain bottlenecks in emerging markets
- 4.3.4 Physician reluctance to switch stable patients in Asia-Pacific
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Biologics (Humira)
- 5.1.2 Biosimilars
- 5.2 By Indication
- 5.2.1 Rheumatoid Arthritis
- 5.2.2 Psoriatic Arthritis
- 5.2.3 Ankylosing Spondylitis
- 5.2.4 Crohn's Disease
- 5.2.5 Ulcerative Colitis
- 5.2.6 Plaque Psoriasis
- 5.2.7 Hidradenitis Suppurativa
- 5.2.8 Juvenile Idiopathic Arthritis
- 5.2.9 Uveitis
- 5.2.10 Others
- 5.3 By Distribution Channel
- 5.3.1 Hospital Pharmacies
- 5.3.2 Retail Pharmacies
- 5.3.3 Online Pharmacies
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Alvotech
- 6.3.3 Amgen Inc.
- 6.3.4 Bio-Thera Solutions Ltd.
- 6.3.5 Biogen Inc.
- 6.3.6 Boehringer Ingelheim Intl. GmbH
- 6.3.7 Celltrion Inc.
- 6.3.8 Coherus BioSciences, Inc.
- 6.3.9 Dr. Reddy's Laboratories Ltd.
- 6.3.10 Fresenius Kabi AG
- 6.3.11 Lupin Limited
- 6.3.12 Organon & Co.
- 6.3.13 Pfizer Inc.
- 6.3.14 Reliance Life Sciences Pvt. Ltd.
- 6.3.15 Samsung Bioepis Co., Ltd.
- 6.3.16 Sandoz Group AG
- 6.3.17 Shanghai Henlius Biotech Inc.
- 6.3.18 Stada Arzneimittel AG
- 6.3.19 Viatris Inc.
- 6.3.20 Zydus Lifesciences Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


