

|
시장보고서
상품코드
2114704
의료용 방사선 차폐 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Medical Radiation Shielding - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 의료용 방사선 차폐 시장 규모는 2025년에 15억 9,000만 달러로 평가되었습니다. 2026년에 16억 9,000만 달러에 달하고, 2031년까지 23억 2,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년에 걸쳐 CAGR 6.54%로 성장할 전망입니다.
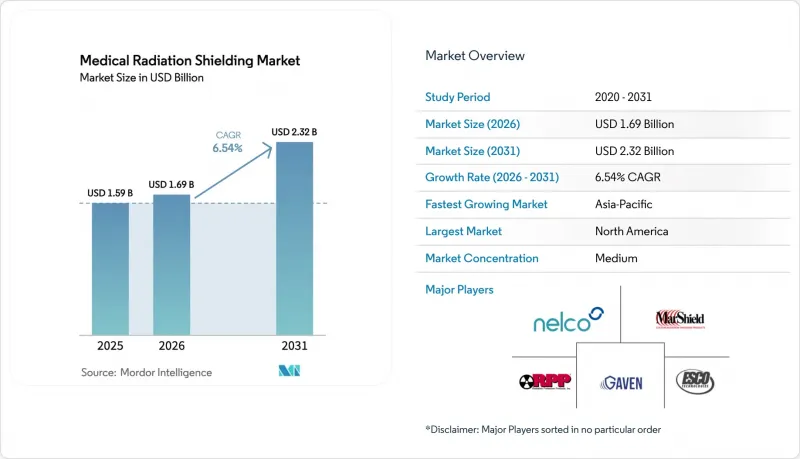
본 보고서는 소재별(납, 납 복합재, 비납),영상 진단·치료법별(진단 방사선학, 핵의학/PET, 외부 조사 요법, 양성자·중이온선 치료), 최종 사용자별(병원 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 의료용 방사선 차폐 시장 동향 및 인사이트
전 세계 암 발병률 증가로 인해 방사선 치료 및 영상 진단 장비의 설치가 증가하고 있습니다.
암은 여전히 전 세계 사망 원인 2위를 차지하고 있으며, 환자의 50-60%가 치료 중 방사선 치료를 필요로 합니다. 사하라 이남 아프리카 23개국에서는 여전히 방사선 치료 장비가 부족하기 때문에 IAEA의 ‘Rays of Hope’ 프로그램을 통해 이 지역에 선형 가속기 및 코발트-60 장비가 도입되고 있습니다. 새로운 방사선 차폐실 1개를 건설하려면 벽, 천장, 바닥에 2-4mm 두께의 납에 상응하는 차폐재가 필요하며, 이를 위해서는 수 메트르톤의 자재가 소요됩니다. 신흥 시장에서 CT 및 투시 검사의 보급 확대는 기술자 보호를 목적으로 한 차폐재 수요를 더욱 가속화하고 있습니다. 지속적인 검진 정책과 의료 보편적 보장을 위한 노력으로 전 세계적으로 차폐 프로젝트의 견실한 파이프라인이 유지되고 있으며, 향후 4년 내에 정점에 달할 것으로 예측됩니다.
첨단 방사선 치료법의 도입에 따라 차폐 강화가 필요해지고 있습니다.
세계 양성자 치료 센터의 수는 2025년까지 114곳으로 증가했으며, 2030년까지 40곳이 추가로 완공될 예정입니다. 이러한 시설에는 붕소 첨가 폴리에틸렌 층으로 보강된 두께 3m의 중성자 감쇠 콘크리트 벽이 필요합니다. 영상 유도형 및 강도 변조형(IMRT) 선형 가속기에서도 산란 방사선에 대한 보다 엄격한 제어가 요구되고 있어, 기존 벙커의 개조 수요를 뒷받침하고 있습니다. 히타치와 같은 공급업체들은 벙커 설계와 장비 공급을 패키지로 묶어 공사 기간을 단축하는 한편, 2기의 갠트리를 갖춘 양성자선 치료실 1세트당 프로젝트 비용을 1억 달러 이상으로 끌어올리고 있습니다. 토목 공사, 차폐 물리학 및 인허가 절차를 일괄적으로 관리하는 통합 공급업체는 이러한 장기 계약을 수주하는 데 유리한 입장에 있습니다.
차폐 시설 및 벙커 건설에 소요되는 막대한 설비 투자
외부 조사용 벙커의 건설비는 1기당 150만-300만 달러이지만, 양성자선 치료 센터의 경우 1억 달러를 초과하며, 그 지출의 최대 30%를 차폐 공사가 차지합니다. 저소득 지역의 많은 공립 병원은 매년 예산 배분에 의존하고 있기 때문에 조달 주기가 18개월 이상 걸리는 경우가 있습니다. 미국 환경보호청(EPA)은 이 폐기물을 유해 폐기물로 분류하고 있으며, 이로 인해 1메트르톤당 200-400달러의 처분 비용이 추가되어 기존 시설의 개보수를 방해하고 있습니다. 조립식 차폐벽이나 3D 프린팅 복합재가 해결책이 될 수 있으나, 여전히 건축 기준 적합성 확인이 필요하며, 자금 사정이 어려운 시장에서는 의사결정 기간이 길어지고 있습니다.
지역별 분석
북미는 높은 의료비 지출과 인증된 차폐 재료의 사용을 의무화하는 FDA의 엄격한 감독에 힘입어 2025년 매출의 35.65%를 차지했습니다. 노후된 방호실의 교체 주기가 도시 지역 시장의 프로젝트를 뒷받침하고 있는 한편, 코네티컷주와 탬파의 양성자 치료 시설 확장에선 높은 수준의 중성자 방호가 요구되고 있습니다. EPA의 폐기물 규제로 인해 납 이외의 대체 재료 채택이 가속화되고 있으며, 폐쇄형 재활용이 촉진되고 있습니다.
아시아태평양은 성장의 원동력이 되고 있으며, 중국과 인도의 공공 부문 시설 확충에 힘입어 2031년까지 연평균 성장률(CAGR)은 7.23%로 예측됩니다. 중국에서는 비용의 최대 60%를 지원하는 성(省) 차원의 보조금 덕분에 2024년에 방사선 치료 장비 대수가 3,000대를 돌파했습니다. 인도의 15억 달러 규모 암 센터 건설 계획에서는 공사 기간을 단축하기 위해 모듈식 패널이 우선적으로 채택되고 있습니다. 아폴로 병원(Apollo Hospitals) 등 민간 병원 체인은 첸나이와 콜카타에 양성자 치료 센터를 신설하고 있으며, 이에 따라 중성자 등급 콘크리트에 대한 수요가 증가하고 있습니다.
유럽에서는 유해물질 사용 제한(RoHS) 지침에 따라 무연 솔루션이 중시되고 있으며, 비스무트와 텅스텐 복합재료에 대한 연구 개발이 촉진되고 있습니다. 중동에서는 의료 관광의 해외 유출을 막기 위해 아랍에미리트와 사우디아라비아에 ‘센터 오브 엑설런스(Center of Excellence)’에 대한 자금 지원이 이루어지고 있습니다. 사하라 이남 아프리카에서는 여전히 의료 서비스가 불충분하지만, IAEA의 ‘Rays of Hope’ 이니셔티브를 통해 외부 조사용 차폐실 건설이 수년에 걸쳐 계획되고 있습니다. 남미 최초의 양성자 치료 시설이 2025년 부에노스아이레스에서 가동을 시작할 예정이며, 이는 고품질 차폐재에 대한 수요가 증가하고 있음을 보여줍니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the medical radiation shielding market size is projected to be USD 1.59 billion in 2025, USD 1.69 billion in 2026, and reach USD 2.32 billion by 2031, growing at a CAGR of 6.54% from 2026 to 2031.
This report is Segmented by Material (Lead, Lead Composite, and Non-Lead), Imaging/Therapy Modality (Diagnostic Radiology, Nuclear Medicine/PET, External Beam Radiation Therapy, and Proton & Heavy Ion Therapy), End User (Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Radiation Shielding Market Trends and Insights
Rising Global Cancer Incidence Elevating Radiotherapy and Imaging Installations
Cancer remains the second-leading cause of death worldwide, and 50-60% of patients need radiotherapy during treatment. Twenty-three Sub-Saharan countries still lack radiotherapy devices, so the IAEA's Rays of Hope program is deploying linear accelerators and cobalt-60 units in these regions. Each new vault requires 2-4 mm of lead-equivalent shielding for walls, ceilings, and floors, which necessitates several metric tons of material. The growing adoption of CT and fluoroscopy in emerging markets further accelerates shielding demand for technician protection. Continued screening initiatives and universal coverage pledges are maintaining a robust global pipeline of shielding projects, which is expected to crest in the next four years.
Adoption of Advanced Radiation Modalities Necessitating Enhanced Shielding
The number of global proton therapy centers rose to 114 by 2025, with an additional 40 centers slated for completion by 2030. These facilities require 3 m neutron-attenuating concrete walls complemented by borated polyethylene layers. Image-guided and intensity-modulated linear accelerators also require tighter control over scatter radiation, driving the need for retrofits of existing bunkers. Vendors such as Hitachi bundle vault design with equipment supply, compressing schedules but pushing project costs over USD 100 million for a two-gantry proton suite. Integrated suppliers that manage civil works, shielding physics, and approvals are positioned to win these long-cycle contracts.
High Capital Expenditure for Shielded Facilities and Bunker Construction
External-beam vaults cost USD 1.5-3 million each, while proton centers exceed USD 100 million, with shielding accounting for up to 30% of the expenditure. Many public hospitals in low-income regions rely on annual appropriations, stretching procurement cycles beyond 18 months. The U.S. EPA classifies waste as hazardous, adding USD 200-400 per metric ton in disposal fees and deterring retrofits. Prefabricated barriers and 3D-printed composites offer relief but still need code validation, prolonging decision timelines in cash-constrained markets.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Nuclear Medicine and Radiopharmaceutical Manufacturing
- Government-Funded Oncology Infrastructure in Emerging Markets
- Volatile Prices of Lead, Tungsten, and Non-Lead Alloys
For complete list of drivers and restraints, kindly check the Table Of Contents.
Geography Analysis
North America generated 35.65% of 2025 revenue, buoyed by high healthcare spending and stringent FDA oversight that mandates certified shielding materials. Replacement cycles for aging vaults sustain projects in urban markets, while proton therapy expansions in Connecticut and Tampa require premium neutron protection. EPA waste rules are accelerating the adoption of non-lead alternatives, encouraging closed-loop recycling.
The Asia-Pacific region is the growth engine, with a projected 7.23% CAGR through 2031, driven by public-sector build-outs in China and India. China surpassed 3,000 radiotherapy machines in 2024, thanks to provincial subsidies that cover up to 60% of the costs. India's USD 1.5 billion cancer-center program prefers modular panels to compress timelines. Private chains, such as Apollo Hospitals, are adding proton centers in Chennai and Kolkata, thereby amplifying demand for neutron-grade concrete.
Europe emphasizes lead-free solutions under the Restriction of Hazardous Substances (RoHS) directive, spurring research and development in bismuth and tungsten composites. The Middle East funds centers of excellence in the United Arab Emirates and Saudi Arabia to stem the flow of outbound medical tourism. Sub-Saharan Africa remains underserved, but the IAEA Rays of Hope initiative is opening a multi-year pipeline of external-beam vaults. South America's first proton therapy unit commenced operations in Buenos Aires in 2025, signaling a rising demand for premium shielding.
- A&L Shielding
- Alpha Source Group
- AmRay Group
- Barrier Technologies
- ETS-Lindgren
- Esco Technologies Inc.
- Gaven Industries
- Global Partners In Shielding Inc.
- JL Goslar GmbH
- Kemper Medical
- Lite Tech Inc.
- MarShield
- MAVIG GmbH
- Mirion Technologies Inc.
- Nelco
- Radiation Protection Products
- Ray-Bar Engineering
- Shandong EM Radiation Protection Materials
- Veritas Medical Solutions
- Wardray Premise Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Cancer Incidence Elevating Radiotherapy & Diagnostic Imaging Installations
- 4.2.2 Adoption of Advanced Radiation Modalities Necessitating Enhanced Shielding
- 4.2.3 Expansion of Nuclear Medicine & Radiopharmaceutical Manufacturing Capacity
- 4.2.4 Government-Funded Oncology Infrastructure Programs in Emerging Markets
- 4.2.5 Rapid Uptake of Intraoperative Radiation Therapy Suites
- 4.2.6 Use of 3-D Printed Polymer/Tungsten Composite Shielding for Cost-Effective Retrofits
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure for Shielded Facilities and Bunker Construction
- 4.3.2 Volatile Prices of Lead, Tungsten, and Non-Lead Alloys
- 4.3.3 Environmental Liability from Lead-Contaminated Waste Streams
- 4.3.4 Limited Availability of Certified Radiation Shielding Engineers in Developing Regions
- 4.4 Regulatory & Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Material
- 5.1.1 Lead
- 5.1.2 Lead Composite
- 5.1.3 Non-Lead (Bismuth, Tungsten, Antimony, Borated PE)
- 5.2 By Imaging / Therapy Modality
- 5.2.1 Diagnostic Radiology (X-ray, CT, Fluoroscopy)
- 5.2.2 Nuclear Medicine / PET
- 5.2.3 External Beam Radiation Therapy (LINAC, IMRT, IGRT)
- 5.2.4 Proton & Heavy Ion Therapy
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Diagnostic Imaging Centers
- 5.3.3 Ambulatory Surgery Centers
- 5.3.4 Other End Users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest Of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest Of Asia-Pacific
- 5.4.4 Middle-East And Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest Of Middle East And Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest Of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 A&L Shielding
- 6.3.2 Alpha Source Group
- 6.3.3 AmRay Group
- 6.3.4 Barrier Technologies
- 6.3.5 ETS-Lindgren
- 6.3.6 Esco Technologies Inc.
- 6.3.7 Gaven Industries Inc.
- 6.3.8 Global Partners In Shielding Inc.
- 6.3.9 JL Goslar GmbH
- 6.3.10 Kemper Medical Inc.
- 6.3.11 Lite Tech Inc.
- 6.3.12 MarShield
- 6.3.13 MAVIG GmbH
- 6.3.14 Mirion Technologies Inc.
- 6.3.15 Nelco Inc.
- 6.3.16 Radiation Protection Products Inc.
- 6.3.17 Ray-Bar Engineering Corp.
- 6.3.18 Shandong EM Radiation Protection Materials
- 6.3.19 Veritas Medical Solutions LLC
- 6.3.20 Wardray Premise Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


