

|
시장보고서
상품코드
2114766
페이스 및 이어 보우 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Face And Ear Bow - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
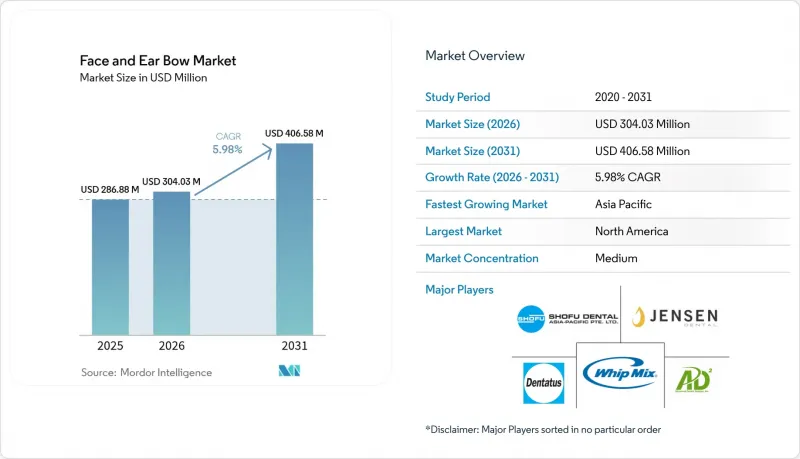
에 의하면, 페이스 및 이어 보우 시장 규모는 2025년에 2억 8,688만 달러로 평가되었습니다. 2026년 3억 403만 달러에서 2031년까지 4억 658만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.98%를 나타낼 전망입니다.

본 보고서는 제품 유형(키네마틱(힌지 축) 페이스 보우, 임의형 페이스 보우, 이어보우, 기타), 소재(알루미늄 합금, 스테인리스, 기타), 용도(교정치과·교합 분석, 기타), 최종 사용자(치과 기공소, 치과 병원, 기타),지역(북미, 유럽, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 페이스 및 이어 보우 시장 동향 및 인사이트
고령화에 따른 보철 시술 증가
대부분의 선진국에서 급속한 인구 고령화로 인해, 복잡한 전악 재건이 필요한 무치악 또는 부분 결손 환자 수가 증가하고 있습니다. 페이스 보우를 사용하여 힌지 축의 관계를 정확하게 전사함으로써, 임플란트의 성공률, 저작 효율, 장기적인 편안함이 크게 향상됩니다. 공중보건 정책에서 구강 기능은 건강한 노화의 핵심 요소로 자리매김하게 되었으며, 보험사 및 정책 입안자들은 조기 수복 치료를 장려하고 있습니다. 그 결과, 교육 과정에서는 페이스 보우 조작 기술이 중요시되고 있으며, 각 제조업체는 고령자의 인체공학적 요구를 충족시키기 위해 더 가벼운 프레임과 단순화된 클램프를 시장에 출시하고 있습니다. 이러한 요인들이 결합되어 정밀한 기록이 노인 돌봄의 일상 업무에 통합됨에 따라, 페이스 및 이어 보우 시장은 변화를 겪고 있습니다.
디지털·가상 페이스 보우가 체어사이드 CAD-CAM을 실현
가상 페이스 보우 시스템은 광학식 턱 추적 센서와 구강 내 스캐너를 통합하여 4D 교합 위치를 실시간으로 생성합니다. 이 워크플로는 CAD 플랫폼과 직접 연동되므로 기계적인 위치 조정 오차가 제거되고, 내원 횟수가 약 40% 감소합니다. 치과의사들로부터는 특히 양측 프리엔드 새들 치료 시, 실험실과의 협업이 원활해지고 재제작이 신속해지며, 첫 번째 시착 성공률이 높아졌습니다는 보고가 접수되고 있습니다. 소프트웨어 업데이트를 통해 턱관절 장애 진단을 지원하는 자동 관절두 채널 시뮬레이션이 추진되면서, 임상 현장에서의 보급이 더욱 확대되고 있습니다. 유럽과 미국의 초기 도입자들에 의해 구매 결정 과정에서 현저한 변화가 일어나며, 디지털 제품이 페이스 및 이어 보우 시장에서 프리미엄 제품군으로서의 입지를 확고히 하고 있습니다.
치과 보철 치료에 대한 보험 급여 제한
대부분의 공적 및 민간 보험사는 보철 치료를 선택적 치료로 분류하고 있어, 치료비의 대부분을 환자가 부담하게 됩니다. 높은 본인 부담 비용으로 인해 티타늄 페이스 보우 키트나 완전 디지털 솔루션과 같은 프리미엄 부속품에 대한 수요가 억제되고 있습니다. 유럽에서는 급여 상한선과 긴 대기 목록으로 인해 많은 고령자들이 상세한 교합 관계 전사를 거치지 않는 기본적인 틀니를 선택할 수밖에 없는 상황에 처해 있습니다. 일부 보험사는 재제작률 감소와 연계하여 정밀 마운트 비용을 최종적으로 보상할 가능성이 있는 치료 성과에 따른 포괄 지급 제도를 시범적으로 도입하고 있으나, 그 움직임은 여전히 더딘 실정입니다. 그 결과, 가격 측면의 압박으로 인해 페이스 및 이어 보우 시장에서의 첨단 시스템의 완전한 보급이 저해되고 있습니다.
부문별 분석
2025년, 범용 페이스 보우는 페이스·이어 보우 시장에서 45.12%라는 최대 점유율을 차지했습니다. 디지털·가상 페이스 보우는 초기 시장 규모는 작지만, 2031년까지 12.24%라는 높은 연평균 성장률(CAGR)을 기록하며 다른 모든 기기 카테고리를 능가할 것으로 예측됩니다. 이러한 인기의 상승은 클리닉이 ‘한 번의 내원으로 완료되는 보철 치료’ 및 ‘클라우드 연동형 랩 서비스’로 전환되고 있음을 반영합니다. 한편, 키네마틱 페이스 보우는 대학원 과정이나 연구센터에서 핵심적인 입지를 유지하고 있으며, 이어보우는 측두골의 참조가 필수적인 턱 교정 수술에 대응하고 있습니다.
모션 캡처 광학 기술 및 AI를 활용한 랜드마크 감지에 대한 투자로 인해 디지털 제품과 기계식 제품의 비용 격차가 줄어들면서, 의료 종사자들의 장비 업그레이드를 뒷받침하고 있습니다. 각 제조업체는 도입을 간소화하기 위해 클라우드 라이선싱, 아티큘레이터 모델, 온라인 교육을 세트로 제공합니다. 포크 팬이나 안와 인디케이터와 같은 부속품의 경우, 클리닉의 프린터와 호환되는 재활용 가능한 수지 모델이 점점 더 보급되면서 수명 주기 전반에 걸친 가치를 확대되고 있습니다. 이러한 동향이 융합되는 가운데, 페이스 및 이어 보우 시장은 신뢰성이 높은 기계식 베이스라인을 완전히 대체하지는 않으면서도 데이터가 풍부한 가상 기기로 계속해서 전환되고 있습니다.
알루미늄 합금은 2025년에 매출의 37.10%를 차지했으며, 가공이 쉽고 취급이 간편하다는 점 때문에 계속해서 엔트리 레벨 키트의 주력 제품으로 자리 잡고 있습니다. 티타늄 부품은 비용이 높지만 연평균 성장률(CAGR) 9.28%를 나타낼 것으로 예측되며, 뛰어난 내식성과 환자 알레르기 유발 가능성이 낮은 특성을 추구하는 고급 치과에서 인기를 끌고 있습니다. 스테인리스는 예산에 민감한 지역에서 여전히 일정한 입지를 유지하고 있는 반면, 강화 엔지니어링 플라스틱은 바이트 포크와 같은 일회용 부속품 분야에서 점유율을 확대되고 있습니다.
적층 가공 기술로 인해 스크랩률이 감소하고, 체어사이드에서의 피로를 줄여주는 중공 프레임 형태가 가능해짐에 따라, 티타늄 어셈블리의 페이스 및 이어 보우 시장 규모는 확대될 것으로 예측됩니다. 주요 아티큘레이터 공급업체들이 도입한 상호 호환성 기준은 모듈식 업그레이드를 촉진하고 있으며, 치과에서는 기존의 알루미늄 프레임에 티타늄 포크를 추가할 수 있게 되었습니다. 현재, 지속 교육 과정에서는 경량이며 고강도인 합금의 생체역학적 이점이 강조되고 있으며, 이를 통해 치과의사의 편의성이 향상되고, 페이스 및 이어 보우 산업에 대한 미래 지향적인 구매 결정이 촉진되고 있습니다.
지역별 분석
북미는 임플란트 치과에 대한 보험 적용이 성숙하고, 체어사이드 CAD-CAM 시스템의 보급률이 높기 때문에 2025년에는 전 세계 매출의 34.40%를 차지하며 계속해서 주도적인 위치를 유지했습니다. 미국과 캐나다의 치과에서는 대규모 그룹 클리닉이 재시술을 줄이는 표준화된 증거 기반 프로토콜을 중시하고 있어, 가상 레지스트리로의 전환이 진행되고 있습니다. 지역별 연구 지원금을 통해 턱 추적 센서와 AI 교합 시뮬레이터를 결합한 프로토타입이 개발되어, 페이스 및 이어 보우 시장에서 기술적 리더십과 브랜드 충성도가 유지되고 있습니다.
유럽도 비슷한 길을 걷고 있지만, 각국의 의료 제도에 따라 도입 현황에는 차이가 보입니다. 독일, 프랑스, 북유럽 국가에서는 1인당 지출액이 높은 반면, 남유럽 국가에서는 여전히 가격에 민감하여 알루미늄이나 스테인리스 재질의 키트에 의존하는 경향이 있습니다. 2025년에 강화된 의료기기 규정(MDR)에 따라 공급업체들은 시판 후 조사에 대한 투자를 강요받고 있으며, 이로 인해 페이스 및 이어 보우 산업 전반의 신뢰성이 향상되고 있습니다. 헝가리, 크로아티아, 스페인으로의 국경 간 치과 관광은 비용 경쟁력이 있는 클리닉들이 가상 교합을 포함한 풀 아치 패키지를 홍보하고 있어 수량 증가를 뒷받침하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 연평균 성장률(CAGR) 8.51%를 나타낼 것으로 예측됩니다. 중국과 인도의 의료 현대화 프로그램으로 인해 공공 치과 보험의 적용 범위가 확대되고 있는 반면, 태국과 한국의 민간 병원은 인바운드 의료 관광을 활용하여 수익을 올리고 있습니다. 이 지역의 페이스 및 이어 보우 시장 규모는 현지 제조업체들이 국제 기준을 준수하면서도 저렴한 3D 프린팅 부속품을 제공함에 따라 더욱 확대되고 있습니다. 정부 주도의 구강 보건 캠페인으로 인해 중산층의 기능적 재활에 대한 인식이 높아지면서, 정밀한 턱 위치 등록 서비스에 대한 안정적인 수요가 창출되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the face and ear bow market size was valued at USD 286.88 million in 2025 and estimated to grow from USD 304.03 million in 2026 to reach USD 406.58 million by 2031, at a CAGR of 5.98% during the forecast period (2026-2031).
This report is Segmented by Product Type (Kinematic (Hinge-Axis) Facebows, Arbitrary Facebows, Ear-Bows, and More), Material (Aluminum Alloys, Stainless Steel, and More), Application (Orthodontics & Occlusal Analysis, and More), End User (Dental Laboratories, Dental Clinics, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Face And Ear Bow Market Trends and Insights
Rising Prosthodontic Procedures Among Ageing Population
Rapid population ageing in most high-income nations is enlarging the pool of edentulous or partially dentate patients who require complex full-arch rehabilitations. Accurate transfer of the hinge-axis relationship with a facebow materially raises implant success, masticatory efficiency, and long-term comfort. Public health agendas now frame oral function as central to healthy ageing, prompting insurers and policymakers to promote early restorative interventions. Academic curricula consequently reinforce facebow skills, while manufacturers roll out lighter frames and simplified clamps to serve geriatric ergonomics. Taken together, these forces transform the face and ear bow market by embedding precision recording into routine senior care.
Digital/Virtual Facebows Enable Chair-Side CAD-CAM
Virtual facebow systems integrate optical jaw-tracking sensors with intraoral scanners to generate 4D articulator positions in real time. The workflow merges directly into CAD platforms, eliminating mechanical indexing errors and cutting appointment counts by nearly 40%. Dentists report streamlined lab communication, faster remakes, and higher first-fit rates, especially when treating bilateral free-end saddles. Software updates push automatic condylar path simulation that aids TMJ diagnostics, further widening clinical uptake. Early adopters in Europe and the United States have driven a visible shift in purchasing decisions, anchoring digital options as the premium tier of the face and ear bow market.
Limited Reimbursement for Dental Prosthetics
Most public and private payers classify prosthodontics as elective, leaving patients to cover the bulk of procedure costs. Out-of-pocket expenditure dampens demand for premium accessories, including titanium facebow kits or full digital solutions. In Europe, benefit caps and long waiting lists steer many seniors toward basic dentures without detailed jaw-relation transfer. Some insurers pilot outcome-based bundles that could eventually reimburse precision mounting when linked to reduced remake rates, yet momentum remains slow. Consequently, pricing pressure restrains full penetration of advanced systems within the face and ear bow market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Cosmetic & Orthodontic Corrections
- 3-D Printed Custom Facebow Parts Lower Costs
- Evidence Questioning Routine Facebow Need
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, Arbitrary Facebows controlled the largest slice of the face and ear bow market share at 45.12%. Digital/Virtual Facebows, though smaller in starting base, are forecast to post a compelling 12.24% CAGR to 2031, outpacing every other device class. The rising preference mirrors clinics' shift toward single-visit prosthetics and cloud-linked lab services. Meanwhile, Kinematic Facebows sustain a core presence in postgraduate programs and research centers, whereas Ear-Bows cater to orthognathic surgery where temporal bone references are essential.
Investments in motion-capture optics and AI-driven landmark detection have narrowed the cost gap between digital and mechanical alternatives, encouraging practitioners to trade up. Manufacturers bundle cloud licenses, articulator models, and online training to simplify onboarding. Accessories, including fork pans and orbital indicators, increasingly come in recyclable resin variants compatible with office printers, extending lifecycle value. As these trends coalesce, the face and ear bow market continues to pivot toward data-rich virtual instrumentation without entirely displacing reliable mechanical baselines.
Aluminum Alloys accounted for 37.10% revenue in 2025 and continue to anchor entry-level kits through ease of machining and familiar handling. Titanium components, although costlier, are projected to log a 9.28% CAGR, attracting high-end clinics seeking superior corrosion resistance and reduced patient allergenicity. Stainless Steel retains a foothold in budget-sensitive regions, while reinforced engineering plastics gain share in disposable accessories such as bite forks.
The face and ear bow market size for titanium assemblies is expected to widen as additive manufacturing cuts scrap rates and supports hollow-frame geometries that lower chairside fatigue. Cross-compatibility standards introduced by major articulator vendors encourage modular upgrades, allowing practices to add titanium forks to existing aluminum frames. Continuing education courses now highlight the biomechanical benefits of lightweight, high-yield alloys, raising practitioner comfort and futureproofing purchase decisions within the face and ear bow industry.
Complete Report Scope:
- By Product Type
- Kinematic (Hinge-axis) Facebows
- Arbitrary Facebows
- Digital / Virtual Facebows
- Ear-Bows
- Accessories
- By Material
- Aluminum Alloys
- Stainless Steel
- Titanium
- Engineering Plastics & Composites
- By Application
- Prosthodontics
- Orthodontics & Occlusal Analysis
- Maxillofacial & Implant Surgery
- By End User
- Dental Laboratories
- Dental Clinics
- Hospitals & Surgical Centers
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained leadership with 34.40% of global revenue in 2025 thanks to mature insurance coverage for implant dentistry and deep penetration of chair-side CAD-CAM systems. Clinics across the United States and Canada continue migrating to virtual registries because large group practices favor standardized, evidence-based protocols that reduce remakes. Regional research grants foster prototypes that pair jaw-tracking sensors with AI occlusal simulators, sustaining technology leadership and brand loyalty in the face and ear bow market.
Europe follows a similar path, although adoption varies among national health systems. Germany, France, and the Nordics show high per-capita expenditure, whereas Southern Europe remains price-sensitive and leans on aluminum or stainless-steel kits. Tightened Medical Device Regulation (MDR) rules in 2025 push suppliers to invest in post-market surveillance, improving reliability across the face and ear bow industry. Cross-border dental tourism into Hungary, Croatia, and Spain supports volume growth as cost-competitive clinics advertise full-arch packages that include virtual articulation.
Asia-Pacific is the fastest-growing territory, expected to post an 8.51% CAGR. Healthcare modernization programs in China and India expand public dental insurance coverage, while private hospitals in Thailand and South Korea capitalize on inbound medical travel. The face and ear bow market size in the region widens further as local manufacturers offer 3-D printed accessories that comply with global standards but at lower price points. Government-led oral-health campaigns heighten functional-rehabilitation awareness among middle-income populations, channeling steady demand for precise jaw registration services.
- Solventum Corporation
- Dentsply Sirona
- KaVo Kerr (Envista)
- Amann Girrbach
- Whip Mix Corp.
- Panadent
- Jensen Dental
- Dentatus
- Shofu Inc.
- Ivoclar Vivadent
- Hager & Werken
- Advance Dental Designs
- Bio-Art Equipamentos
- Denar (Whip Mix)
- Sam Dental Articulators
- CoriDent
- Dentflex
- Zhermack
- Artex (Amann Girrbach)
- Whipmix Store
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prosthodontic Procedures Among Ageing Population
- 4.2.2 Surge In Cosmetic & Orthodontic Corrections
- 4.2.3 Increasing Oral-Hygiene Awareness Campaigns
- 4.2.4 Digital/Virtual Facebows Enable Chair-Side CAD-CAM
- 4.2.5 Dental-Tourism Driven Procedure Volumes
- 4.2.6 3-D Printed Custom Facebow Parts Lower Costs
- 4.3 Market Restraints
- 4.3.1 High Device & Accessory Pricing
- 4.3.2 Limited Reimbursement For Dental Prosthetics
- 4.3.3 Evidence Questioning Routine Facebow Need
- 4.3.4 AI Occlusion-Mapping Scanners As Substitutes
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Kinematic (Hinge-axis) Facebows
- 5.1.2 Arbitrary Facebows
- 5.1.3 Digital / Virtual Facebows
- 5.1.4 Ear-Bows
- 5.1.5 Accessories
- 5.2 By Material
- 5.2.1 Aluminum Alloys
- 5.2.2 Stainless Steel
- 5.2.3 Titanium
- 5.2.4 Engineering Plastics & Composites
- 5.3 By Application
- 5.3.1 Prosthodontics
- 5.3.2 Orthodontics & Occlusal Analysis
- 5.3.3 Maxillofacial & Implant Surgery
- 5.4 By End User
- 5.4.1 Dental Laboratories
- 5.4.2 Dental Clinics
- 5.4.3 Hospitals & Surgical Centers
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Solventum Corporation
- 6.3.2 Dentsply Sirona
- 6.3.3 KaVo Kerr (Envista)
- 6.3.4 Amann Girrbach
- 6.3.5 Whip Mix Corp.
- 6.3.6 Panadent Corporation
- 6.3.7 Jensen Dental
- 6.3.8 Dentatus
- 6.3.9 Shofu Inc.
- 6.3.10 Ivoclar Vivadent
- 6.3.11 Hager & Werken
- 6.3.12 Advance Dental Designs
- 6.3.13 Bio-Art Equipamentos
- 6.3.14 Denar (Whip Mix)
- 6.3.15 Sam Dental Articulators
- 6.3.16 CoriDent
- 6.3.17 Dentflex
- 6.3.18 Zhermack
- 6.3.19 Artex (Amann Girrbach)
- 6.3.20 Whipmix Store
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


