

|
시장보고서
상품코드
2114886
응집제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Coalescing Agents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
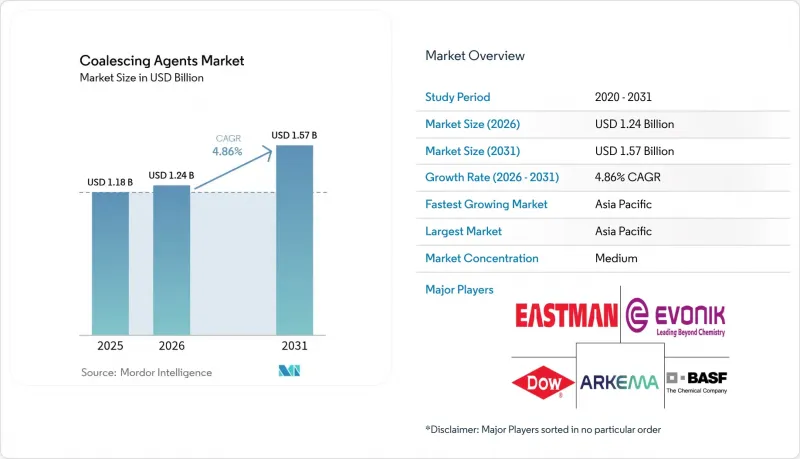
에 의하면, 응집제 시장 규모는 2025년 11억 8,000만 달러로 평가되었고, 2026년에는 12억 4,000만 달러로 추정되고, 2026-2031년 CAGR 4.86%로 성장을 지속할 전망이며, 2031년에는 15억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(친수성, 소수성), 화학 성분별(에스테르, 케톤, 알코올류, 디올·글리콜 에테르, 기타 화학물질), 용도별(페인트 및 코팅, 접착제·실런트,잉크, 퍼스널케어, 기타 용도), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 응집제 시장 동향 및 인사이트
신흥 경제국에서의 산업용 코팅 라인 확대
중국, 인도, 동남아시아 전역에서 사상 최고 수준의 인프라 투자가 이루어지고 있으며, 이로 인해 산업용 코팅 처리량이 확대되어 응집제 시장 수요를 견인하고 있습니다. SABIC이 진행하는 연간 생산 능력 180만 톤, 64억 달러 규모의 푸젠성 프로젝트 등 새로운 에틸렌 및 프로파일렌 크래커의 가동으로 인해, 첨가제 제조에 필수적인 아크릴 에스테르 및 글리콜 에테르 유도체의 후방 통합이 확보되고 있습니다. 공장 도장용 금속, 플라스틱, 목재용 도료에 수성 배합이 의무화됨에 따라, 주변 습도 조건에서 피막 형성을 촉진하는 소수성 등급에 대한 수요가 집중되고 있습니다. 또한, 지역별 석유화학제품의 자급자족으로 인해 수입 의존도가 낮아지면서, 현지 공급업체는 리드 타임을 단축하는 동시에 각국의 서로 다른 VOC 규제에 맞추어 제품을 맞춤화할 수 있게 되었습니다. 이러한 요인들이 맞물려 공급 안정성이 향상되었고, 광범위한 응집제 시장에서 아시아태평양의 우위가 강화되고 있습니다.
자동차 재도장 부문에서 저온 성막 첨가제의 채택 확대
전기차(EV) 플랫폼과 대기질 관리 지역의 엄격한 규제로 인해, 재도장 공장은 에너지를 절약하고 민감한 배터리 부품을 보호하기 위해 더 낮은 소성 프로파일로 전환해야 하는 압박을 받고 있습니다. 2025년 5월에 시행될 사우스코스트 대기질 관리 구역의 개정 규칙 제1151호는 프라이머,베이스 코트, 클리어 코트 시스템 전체에 대한 VOC 상한치를 엄격히 규정하고 있어, 60°C 이하에서 적절한 피막 응집을 실현하는 고비점·저취 응집제로의 전환을 가속화하고 있습니다. 주요 재도장용 도료 제조업체들은 라텍스와의 융합을 촉진하기에 충분한 시간 동안 도막 내에 머무르면서도, 차량 인도 전에는 휘발되는 에스테르 혼합물을 채택하고 있으며, 이를 통해 판금 도장 공장은 사이클 타임 KPI를 달성할 수 있게 되었습니다. 플라스틱 마감, 항공우주 분야의 터치업, 복합재료 보수 분야에서도 유사한 저온 처리 수요가 존재하기 때문에 전 세계적으로 보급이 급속히 진행되고 있습니다. 이러한 산업 전반에 걸친 채택으로 인해 응집제 시장은 확대되고 있으며, 자동차 생산 대수에만 좌우되던 주기적인 변동이 완화되고 있습니다.
고VOC 에스테르 알코올에 대한 REACH·EPA 규제
EU의 REACH 신청 서류와 미국의 국가 VOC 배출 기준에서는 반응성이 높은 에스테르 알코올이 순차적으로 블랙리스트에 등재되고 있어, 배합 설계자는 원료 재검토나 최종 용도 도료의 재인증을 피할 수 없게 되었습니다. 규정 준수를 위한 일정은 연구개발 예산을 압박하고 있으며, 특히 중소기업의 경우 제품 출시를 지연시키고 있습니다. 허용되는 대체품은 대개 비용이 높고, 라텍스 입자를 안정화하기 위해 추가적인 계면활성제 첨가가 필요할 수 있어, 전체 배합의 경제성이 악화되고 있습니다. 지역별 규제 차이는 규모의 경제를 더욱 제한하고, 재고 분산을 초래하며, 물류 복잡성을 증가시켜 응집제 시장의 발전을 저해하고 있습니다.
부문 분석
2025년, 소수성 카테고리는 고부하용 도료에서 입증된 접착력과 내수성 특성을 활용하여 응집제 시장 점유율의 60.10%를 유지했습니다. 건설 기계, 해양 플랫폼, 선박용 탑코트는 모두 습기나 용제에 장기간 노출되기 때문에 소수성 혼합이 지정되어 있습니다. 그러나 배합 담당자들은 높은 고형분 함량에서 광택의 균일성을 관리하기 위해 이러한 첨가제에 보조적인 습윤제를 조합하는 경우가 늘고 있습니다. 대형 도료 제조업체들은 안정적인 수주를 보장하는 장기 계약을 선호하기 때문에 이익률은 계속해서 매력적인 수준을 유지하고 있습니다.
친수성 등급은 현재 시장 규모가 작지만, 엄격한 실내 공기질 기준을 배경으로 2031년까지 연평균 성장률(CAGR) 5.51%를 나타낼 것으로 예측됩니다. 수성 포장재에 대한 분자 수준의 친화성 덕분에 소수성 제품에 비해 사용량을 10-15% 절감할 수 있어, 리터당 총 VOC 배출량을 줄일 수 있습니다. 화장품용 에멀젼 제조업체들은 이러한 제제를 활용하여 수포유형 제제를 안정화하고, 합성 계면활성제를 사용하지 않고도 관능적 특성을 향상시키고 있습니다. 연구 개발을 통해 피막 형성 특성이 정교해짐에 따라, 실내용 라텍스 도료 및 차세대 접착제에의 채택이 가속화되어 응집제 시장은 더욱 다양해질 전망입니다.
지역별 분석
2025년, 아시아태평양은 응집제 시장 규모의 38.40%를 차지했습니다. 중국 연안 성 및 베트남 롱손 복합 단지에 신설된 에틸렌 및 아크릴 에스테르 생산 거점들은 원료 공급을 확보하고 운송 비용을 절감하고 있습니다. 각 지방 정부는 VOC 대책에 대한 OECD 기준과의 조화를 지속적으로 추진하고 있으며, 이는 수성 도료의 채택을 뒷받침하고 있습니다. 이러한 정책적 지원에 더해, 소비자 수요 증가와 전자상거래용 포장 시장의 성장이 맞물리면서 2031년 연평균 성장률(CAGR)은 5.29%를 기록해 전 세계에서 가장 빠른 성장률을 보일 전망입니다.
북미는 수요의 약 4분의 1을 차지하고 있으며, 성숙 단계에 접어들었음에도 혁신이 활발한 도료 및 퍼스널케어 부문이 이를 뒷받침하고 있습니다. 미국 환경보호청(EPA)이 에어로졸 도료 규제 시한을 2027년 1월까지 연장한 조치는 배합 검사 유예 기간을 제공하여 단기적인 수요를 안정시키고 있습니다. 한편, 전기차 조립 라인으로의 전환에 따라 재도장 및 플라스틱 내장 부품 분야의 저온 응집형 혼합물 소비량이 증가하고 있습니다. 원자재 가격 변동은 여전히 이 지역의 주요 역풍으로 작용하고 있으며, 하류 사용자들은 계약 기간 단축을 요구하며 협상을 진행하고 있습니다.
유럽은 북미와 마찬가지로 기술 도입이 진행되고 있으나, 아크릴산 및 글리콜 에테르 생산에 파급되는 천연가스 가격 급등으로 어려움을 겪고 있습니다. 생산자들은 제로 VOC 혁신 기술과 바이오 원료의 추적성 인증을 중시함으로써 비용 상승을 상쇄하고 있습니다. 사용 후 플라스틱 재활용 목표에 관한 규제의 명확화는 연구개발(R&D) 파트너십을 촉진하고 있으며, 이를 통해 유럽 기업들은 순환형 화학의 최전선에 자리매김하며 응집제 시장에 꾸준한 기여를 이어가고 있습니다.
라틴아메리카, 중동 및 아프리카는 합쳐서 높은 성장이 예상되는 신흥 시장을 형성하고 있습니다. 사우디아라비아와 아부다비에서 진행 중인 석유화학 플랜트 확장은 수지용 용매공급 기반을 강화하고 있으며, 하류 첨가제 사업으로의 진출을 촉진하고 있습니다. 브라질과 멕시코에서는 주택 시장의 회복과 수출 지향적인 가전제품 제조가 다양한 소비 거점을 창출하고 있습니다. 다국적 기업들은 이러한 지역에 기술 서비스 팀을 배치하고, 열대 기후의 성능 기준에 맞추어 제품을 맞춤화함으로써 장기적으로 응집제의 잠재 시장을 확대되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.28According to Mordor Intelligence, the coalescing agent market size is expected to grow from USD 1.18 billion in 2025 to USD 1.24 billion in 2026 and is forecast to reach USD 1.57 billion by 2031 at 4.86% CAGR over 2026-2031.
This report is Segmented by Type (Hydrophilic, Hydrophobic), Chemistry (Esters, Ketones, Alcohols, Diols and Glycol-Ethers, Other Chemistries), Application (Paints and Coatings, Adhesives and Sealants, Inks, Personal Care, Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Coalescing Agents Market Trends and Insights
Expansion of Industrial Coating Lines in Developing Economies
Record infrastructure outlays across China, India, and Southeast Asia are lifting industrial coating throughput and creating a volume pull for the coalescing agents market. New ethylene and propylene crackers, such as SABIC's USD 6.4 billion Fujian project with 1.8 million t/y capacity, guarantee backward integration for acrylic esters and glycol-ether derivatives essential to additive production. As water-borne formulations become mandatory in factory-applied metal, plastic, and wood coatings, demand concentrates on hydrophobic grades that accelerate film formation at ambient humidity. Regional petrochemical self-sufficiency also curbs import dependency, enabling local suppliers to shorten lead times while tailoring products to divergent national VOC caps. Collectively, these factors improve supply security and strengthen APAC's positional advantage within the broader coalescing agents market.
Uptake of Low-Temperature Film-Formation Additives in Automotive Refinish
Electric-vehicle platforms and stringent air-district rules push refinish shops toward lower bake profiles to conserve energy and protect sensitive battery components. The South Coast Air Quality Management District's revised Rule 1151, effective May 2025, tightens VOC ceilings across primer, base-coat, and clear-coat systems, accelerating the switch to high-boiling, low-odor coalescing agents that deliver proper film coalescence below 60 °C. Large refinish paint makers are incorporating ester blends that remain in the film long enough to promote latex fusion yet volatilize before service, helping body shops meet cycle-time KPIs. Global uptake is rapid because identical low-temperature needs exist in plastics finishing, aerospace touch-ups, and composite repair. This cross-sector adoption enlarges the coalescing agents market and mitigates cyclical swings tied solely to automotive volumes.
REACH and EPA Restrictions on High-VOC Ester Alcohols
EU REACH dossiers and the U.S. National VOC Emission Standards are progressively blacklisting high-reactivity ester alcohols, obliging formulators to re-screen raw materials and re-qualify end-use coatings Compliance timelines consume R&D budgets and slow product launches, especially for SMEs. Because acceptable substitutes often cost more and may require additional surfactant packages to stabilize latex particles, overall formulation economics tighten. Regional rule deviations further limit economies of scale, fragmenting inventories and adding logistics complexity that restrains the coalescing agents market.
Other drivers and restraints analyzed in the detailed report include:
- Tightening Indoor-Air-Quality Norms in Building Codes
- Commercialization of Reactive (Zero-VOC) Coalescing Agents
- Volatility in Glycol-Ether Feedstock Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The hydrophobic category retained 60.10% of the coalescing agents market share in 2025, benefiting from proven adhesion and water-resistance properties in heavy-duty coatings. Construction equipment, offshore platforms, and marine topcoats all specify hydrophobic blends due to prolonged exposure to moisture and solvents. Yet formulators increasingly complement these agents with ancillary wetting aids to manage gloss uniformity at higher solid contents. Margins remain attractive because large-volume paint makers favor long-term contracts that guarantee steady off-take.
Hydrophilic grades, while smaller today, log a 5.51% CAGR through 2031 on the back of stringent indoor-air-quality targets. Their molecular affinity to water packages allows use levels 10-15% lower than hydrophobic counterparts, trimming total VOC grams per liter. Cosmetic emulsion producers leverage these agents to stabilize oil-in-water formulations, improving sensory attributes without synthetic surfactants. As R&D refines film-formation profiles, uptake will accelerate in interior latex paints and next-generation adhesives, further diversifying the coalescing agents market.
Complete Report Scope:
- By Type
- Hydrophilic
- Hydrophobic
- By Chemistry
- Esters
- Ketones
- Alcohols
- Diols and Glycol-ethers
- Other Chemistries (Lactates, Citrates, Siloxanes)
- By Application
- Paints and Coatings
- Adhesives and Sealants
- Inks
- Personal Care
- Other Applications (Plastics and Polymers, Oil-and-Gas Separators, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 38.40% of coalescing agents market size in 2025. New ethylene and acrylic ester capacity clusters in China's coastal provinces and in Vietnam's Long Son complex assure raw-material supply and reduce freight expense. Regional governments continue to harmonize VOC measures with OECD benchmarks, propelling water-borne coating adoption. This policy push, combined with consumer upgrading and e-commerce packaging growth, yields a 5.29% CAGR through 2031, the fastest worldwide.
North America accounts for roughly one-quarter of demand, underpinned by mature but innovation-rich coatings and personal-care sectors. The EPA's aerosol-coating deadline extension to January 2027 offers breathing room for formulation trials, stabilizing near-term offtake. Meanwhile, the shift to electric vehicle assembly lines raises consumption of low-temperature coalescing blends in refinish and plastic interior parts. Feedstock pricing volatility remains the primary regional headwind, prompting downstream users to negotiate shorter contracts.
Europe mirrors North American technology adoption yet grapples with elevated natural-gas costs that feed into acrylic-acid and glycol-ether production. Producers offset cost inflation by emphasizing zero-VOC innovations and bio-feedstock chain-of-custody certifications. Regulatory clarity on post-consumer plastic recycling targets stimulates R&D partnerships that position European firms at the vanguard of circular chemistry, maintaining steady contributions to the coalescing agents market.
Latin America, the Middle East, and Africa together represent a high-growth frontier. Petrochemical build-outs in Saudi Arabia and Abu Dhabi underpin resin-grade solvent availability, inviting downstream additive ventures. In Brazil and Mexico, housing rebound and export-oriented appliance manufacturing add diverse consumption points. Multinationals deploy technical service teams in these regions to tailor products to tropical climate performance norms, thereby expanding the addressable coalescing agents market over the long term.
- Arkema
- BASF
- Cargill, Incorporated.
- Cristol
- Dow
- Eastman Chemical Company
- Elementis PLC
- Evonik Industries AG
- Indorama Ventures
- Perstorp
- Runtai Chemical Co., Ltd.
- Shell Plc
- Stepan Company
- Synthomer plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Industrial Coating Lines in Developing Economies
- 4.2.2 Uptake of Low-Temperature Film-Formation Additives in Automotive Refinish
- 4.2.3 Tightening Indoor-Air-Quality Norms in Building Codes
- 4.2.4 Commercialisation of Reactive (Zero-VOC) Coalescing Agents
- 4.2.5 Increasing Demand for Specialty and High Performance Inks and Coatings
- 4.3 Market Restraints
- 4.3.1 REACH And EPA Restrictions on High-VOC Ester Alcohols
- 4.3.2 Volatility in Glycol-Ether Feedstock Pricing
- 4.3.3 Self-Coalescing Polymer Dispersion Technologies
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Hydrophilic
- 5.1.2 Hydrophobic
- 5.2 By Chemistry
- 5.2.1 Esters
- 5.2.2 Ketones
- 5.2.3 Alcohols
- 5.2.4 Diols and Glycol-ethers
- 5.2.5 Other Chemistries (Lactates, Citrates, Siloxanes)
- 5.3 By Application
- 5.3.1 Paints and Coatings
- 5.3.2 Adhesives and Sealants
- 5.3.3 Inks
- 5.3.4 Personal Care
- 5.3.5 Other Applications (Plastics and Polymers, Oil-and-Gas Separators, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 Cargill, Incorporated.
- 6.4.4 Cristol
- 6.4.5 Dow
- 6.4.6 Eastman Chemical Company
- 6.4.7 Elementis PLC
- 6.4.8 Evonik Industries AG
- 6.4.9 Indorama Ventures
- 6.4.10 Perstorp
- 6.4.11 Runtai Chemical Co., Ltd.
- 6.4.12 Shell Plc
- 6.4.13 Stepan Company
- 6.4.14 Synthomer plc
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Rising Focus on Eco-friendly Products


