

|
시장보고서
상품코드
2114962
실란 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Silanes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
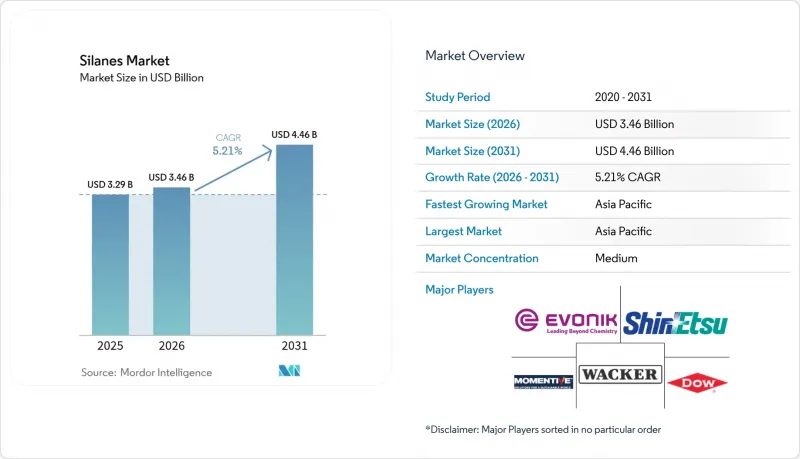
에 의하면, 실란 시장 규모는 2025년에 32억 9,000만 달러로 평가되었고, 2026년 34억 6,000만 달러에서 2031년까지 44억 6,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 5.21%를 나타낼 전망입니다.
본 보고서는 기능기별(비닐, 아미노, 에폭시, 메르캅토, 알콕시, 기타), 용도별(커플링제, 접착 촉진제, 수분 흡수제, 기타), 최종 사용자 산업별(페인트 및 코팅, 고무 및 플라스틱, 전자기기, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 실란 시장 동향 및 인사이트
도료 및 산업용 코팅 수요 급증
2024년, 도료 및 코팅은 실란 시장 수요의 30.22%를 차지했습니다. 이 점유율은 신흥국에서의 인프라 프로젝트 확대와 휘발성 유기 화합물(VOC)에 대한 규제 강화를 반영한 것입니다. 수성 배합에서는 유기 바인더와 무기 기질 간의 견고한 접착력을 확보하기 위해 실란 커플링제에 대한 의존도가 높아지고 있으며, 이러한 수요는 해양 환경이나 가혹한 사용 환경에서 더욱 두드러지고 있습니다. 캘리포니아주가 VOC(휘발성 유기 화합물) 규제 강화를 제안함에 따라 배합 재검토 주기가 가속화되어, 전 세계 코팅 배합 제조업체들이 저메탄올 함유 실란 등급을 채택하고 있습니다. 이러한 첨단 실란 화학 기술을 통해 코팅의 내구성을 유지하면서 제조업체가 변화하는 규제를 준수할 수 있도록 지원하고 있습니다. 그 결과 발생하는 파급 효과로 인해 실란 시장의 장기적인 수요 전망이 견고해지고 있습니다.
전자 기기의 소형화와 5G용 반도체 패키징
7nm 이하의 로직 및 메모리 노드의 등장으로 칩과 패키징 간의 상호작용에 따른 응력이 변화함에 따라, 초박형 확산 배리어에 대한 요구 수준이 높아지고 있습니다. 유기 실란계 접착 촉진제는 구리 배선 및 패시베이션 층을 보호하여, 팬아웃 웨이퍼 레벨 패키징에서 I/O 밀도를 향상시킬 수 있게 합니다. 아시아태평양의 파운드리 확장에 따라 반도체 등급 소재 수요량이 증가하고 있는 반면, 북미의 디바이스 제조업체들은 지정학적 리스크를 완화하기 위해 현지 조달을 확대되고 있습니다. 이러한 기술적 의존 관계로 인해 전자기기 부문은 실란 시장의 지속적인 성장 동력이 되고 있습니다.
VOC 및 메탄올 함량에 관한 REACH의 엄격한 규제
유럽화학물질청(ECHA)은 환상 실록산인 D4, D5, D6을 ‘분해가 어렵고 생물 축적성이 있는’ 물질로 분류하고 있으며, 공급업체들은 2026년 6월 시행일까지 제품 라인을 전면적으로 재검토해야 합니다. 제조업체는 분석적 타당성 확인, 안전 데이터 시트(SDS) 관리 업데이트, 공장 개보수에 투자해야 하며, 이로 인해 밸류체인 전반에 걸쳐 규정 준수 비용이 증가하게 됩니다. 대형 기존 기업들은 이러한 비용을 감당할 수 있겠지만, 소규모 배합 제조업체들은 사업을 축소할 가능성이 있어, 그 결과 실란 시장의 단기적인 생산 능력 증가는 둔화될 것으로 보입니다.
부문 분석
비닐실란은 실리카 강화 타이어 및 유리 섬유 복합재료에서 매우 중요한 역할을 하고 있기 때문에 2025년에는 세계 수요의 38.72%를 차지했습니다. 비닐 실란은 고무 매트릭스와 중합하면서 충전재 표면에 그래프트 결합하는 능력을 통해 낮은 구름 저항과 높은 젖은 노면 그립 성능을 보장합니다. 주요 타이어 제조업체들이 실리카 기반 트레드 배합을 유지하는 가운데, 비닐계 화학 물질에 기인한 실란 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 한편, 전자 기기 및 부식 방지 부문에서는 온화한 조건에서 높은 반응성이 요구되기 때문에 머캅토실란은 2031년까지 6.65%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 듀얼 실란으로 사전 개질된 충전재에 대한 조사에서는 우수한 가교 밀도가 확인되었으며, 하이브리드 화학이 향후 수요를 재구성할 가능성이 있음을 시사하고 있습니다. 아미노, 에폭시, 알콕시 계열은 복합재료 및 접착 촉진 용도에서 틈새 수요를 지속적으로 확보하며 실란 시장의 기능적 다양성을 뒷받침하고 있습니다.
환경에 대한 관심이 높아지는 가운데, 모든 관능기에 대해 저VOC 및 메탄올 프리 등급을 위한 연구 개발이 추진되고 있습니다. 비닐 기술 분야에서는 잔류 염소를 저감하는 촉매의 단계적 개량이 진행되고 있는 반면, 메르캅토 계열에서는 보다 깨끗한 경화 부산물을 얻기 위한 황의 최적화가 모색되고 있습니다. 또한, 각 공급업체들은 혼합 주기를 단축하고 용제 노출을 최소화하는 사전 가수분해 농축액의 개발도 추진하고 있습니다. 이러한 공정 혁신을 통해 고객의 생산성이 향상되고 성능 격차가 축소됨에 따라, 실란 시장이 성숙해가는 과정에서도 각 기능 계열이 계속해서 중요한 역할을 수행할 수 있을 것으로 보장됩니다.
지역별 분석
2025년, 아시아태평양은 세계 수요의 46.10%를 차지했으며, 이는 중국의 광범위한 전자기기, 자동차, 건설 밸류체인을 반영합니다. 이 지역의 실란 시장 규모는 생산 능력 확대가 첨단 제조를 위한 지역적 정책 인센티브와 부합함에 따라 2031년까지 연평균 성장률(CAGR) 6.48%로 확대될 것으로 예측됩니다. Wacker사가 난징, 장자강, 상하이에 여러 거점을 두고 있다는 사실은 현지 생산, 물류, 애플리케이션 개발 지원의 필요성을 뒷받침합니다. 인도의 건축자재 시장 확대와 재생에너지 목표 달성은 추가적인 성장의 호재가 되는 한편, 일본과 한국에서는 반도체 및 전기차 배터리 부품용 프리미엄 등급 제품에 대한 수요가 지속되고 있습니다.
북미는 성숙한 시장이지만, 전략적으로 중요한 거점으로 남아 있습니다. 워싱턴주에 건설될 7,200톤 규모의 실란 공장에 대해 Group14사에 2억 달러의 연방 자금이 투입된 것은 국내 공급망을 강화하려는 정부의 이니셔티브을 여실히 보여줍니다. 자동차의 전동화, 항공우주용 복합재료, 재해 방지 인프라의 의무화가 맞물려 특수 실란에 대한 수요를 뒷받침하고 있습니다. 또한, 이 지역에서는 VOC(휘발성 유기 화합물) 및 유해 물질에 대한 규제가 엄격하기 때문에 저배출형 배합제 공급업체가 우대받고 있으며, 실란 시장에서 제품의 차별화가 촉진되고 있습니다.
유럽에서는 REACH 규제에 대응하여 제품 포트폴리오가 재편되고, 크롬 프리 및 메탄올 저감 등급의 채택이 촉진되는 가운데 완만한 성장이 나타나고 있습니다. 에보닉(Evonik)이나 모멘티브(Momentum) 등 연구 개발과 제조를 일체화한 제조업체들은 공장 개보수를 활용하여, 더욱 엄격한 규제 하에서도 시장 접근성을 확보하고 있습니다. 남미와 중동 및 아프리카에서는 인프라 정비와 산업화가 진행됨에 따라 새로운 기회가 생겨나고 있습니다. 시카(Sika)가 2024년에 인도와 중국에서 전개할 신규 공장 및 기술 센터 네트워크는 전 세계의 공정 노하우를 활용하면서도 현지 성능 기준에 부합할 수 있는 지역 플랫폼 로드맵을 제공합니다. 수입 의존도와 물류의 복잡성으로 인해 현지 생산이 성숙 단계에 도달할 때까지는 도입률이 제한될 가능성이 있으며, 실란 시장 내에서는 지역별로 상이한 성장 양상이 나타날 것으로 예측됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.28According to Mordor Intelligence, the silanes market size was valued at USD 3.29 billion in 2025 and estimated to grow from USD 3.46 billion in 2026 to reach USD 4.46 billion by 2031, at a CAGR of 5.21% during the forecast period (2026-2031).
This report is Segmented by Functional Group (Vinyl, Amino, Epoxy, Mercepto, Alkoxy, Others), Application (Coupling Agents, Adhesion Promoters, Moisture Scavengers, and More), End-User Industry (Paints and Coatings, Rubber and Plastics, Electronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Silanes Market Trends and Insights
Surging Paints and Industrial Coatings Demand
Paints and coatings represented 30.22% of the silanes market demand in 2024, a share that reflects infrastructure projects across emerging economies and stricter rules on volatile organic compounds. Water-borne formulations increasingly rely on silane coupling agents for strong adhesion between organic binders and inorganic substrates, a need magnified in marine and heavy-duty environments. California's architectural-coatings proposal to tighten VOC limits has accelerated reformulation cycles, prompting coating formulators worldwide to adopt low-methanol silane grades. Advanced silane chemistries thus preserve coating durability while helping producers comply with evolving regulations. The resulting pull-through effect fortifies long-range demand visibility for the silanes market.
Electronics Miniaturisation and 5G Semiconductor Packaging
Logic and memory nodes below 7 nm have shifted chip-package interaction stresses, raising the bar for ultra-thin diffusion barriers. Organosilane adhesion promoters safeguard copper interconnects and passivation layers, enabling higher I/O density in fan-out wafer-level packaging. Semiconductor-grade material volumes are climbing in tandem with Asia-Pacific's foundry expansions, while North American device makers increase local sourcing to mitigate geopolitical risk. This technical dependence embeds electronics as a durable growth locomotive for the silanes market.
Stringent REACH Limits on VOC and Methanol Content
The European Chemicals Agency has classified cyclic siloxanes D4, D5, and D6 as persistent and bioaccumulative, compelling suppliers to overhaul product lines ahead of the June 2026 enforcement date. Manufacturers must invest in analytical validation, updated safety-data-sheet management, and plant upgrades, elevating compliance costs across the value chain. Although larger incumbents can absorb these expenses, smaller formulators may curtail operations, thereby moderating short-term capacity additions to the silanes market.
Other drivers and restraints analyzed in the detailed report include:
- Light-weighting in Electric-Vehicle Tires and Green Tires
- Water-borne Adhesive Adoption in Construction
- Tetrachlorosilane Handling Hazards and Logistics Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vinyl silanes captured 38.72% of global demand in 2025, owing to their pivotal role in silica-reinforced tires and glass-fibre composites. Their ability to graft onto filler surfaces while polymerising with rubber matrices ensures low rolling resistance and high wet-grip performance. The silanes market size attributed to vinyl chemistry is projected to advance steadily as mainstream tire producers uphold silica-based tread formulations. In parallel, mercapto silanes are forecast to post the highest 6.65% CAGR through 2031 as electronics and anti-corrosion sectors seek elevated reactivity under mild conditions. Research on dual-silane pre-modified fillers reveals superior crosslink density, indicating that hybrid chemistries could reshape future demand. Amino, epoxy, and alkoxy families continue to secure niche volumes across composites and adhesion-promotion uses, underpinning functional diversity in the silanes market.
Growing environmental focus is driving R&D into low-VOC and methanol-free grades across all functional groups. Vinyl technology benefits from incremental catalyst refinements that cut residual chlorine, while mercapto routes explore sulfur optimization for cleaner curing by-products. Suppliers also advance pre-hydrolysed concentrates that shorten mixing cycles and minimise solvent exposure. Such process innovations elevate customer productivity and tighten performance spreads, ensuring that each functional family retains relevance as the silanes market matures.
Complete Report Scope:
- By Functional Group
- Vinyl
- Amino
- Epoxy
- Mercepto
- Alkoxy
- Others (Isocyanate, Acryloxy, etc.)
- By Application
- Coupling Agents
- Adhesion Promoters
- Moisture Scavengers
- Hydrophobing and Dispersing Agents
- Silicate Stabilizers
- Anti-corrosion and Surface Treatments
- By End-user Industry
- Paints and Coatings
- Rubber and Plastics
- Electronics
- Chemicals
- Other End-user Industries (Energy, Agrochemicals, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 46.10% of global demand in 2025, reflecting China's extensive electronics, automotive, and construction value chains. The silanes market size in the region is projected to compound at 6.48% CAGR through 2031 as capacity additions align with regional policy incentives for advanced manufacturing. Wacker's multi-site footprint in Nanjing, Zhangjiagang, and Shanghai underscores the need for local production, logistics, and application-development support. India's building-materials expansion and renewable-energy targets add further upside, while Japan and South Korea sustain premium-grade uptake for semiconductor and EV battery components.
North America remains a mature yet strategically important hub. Federal funding of USD 200 million to Group14 for a 7,200 metric-ton silane plant in Washington illustrates government efforts to strengthen domestic supply chains. Automotive electrification, aerospace composites, and resilient-infrastructure mandates collectively nurture specialized silane demand. The region's regulatory rigor regarding VOC and toxic-substance control also rewards suppliers of low-emission formulations, fostering product differentiation in the silanes market.
Europe exhibits moderate growth as REACH compliance reshapes product portfolios and spurs adoption of chrome-free and methanol-reduced grades. Producers with integrated R&D and manufacturing, such as Evonik and Momentive, leverage site upgrades to secure market access under stricter rules. South America and the Middle East & Africa present nascent opportunities as infrastructure and industrialisation advance. Sika's 2024 network of new plants and technology centers in India and China provide a roadmap for regional platforms that can mirror local performance norms while leveraging global process know-how. Import dependence and logistics complexity could nevertheless temper adoption rates until local manufacturing matures, creating segmented expansion profiles within the silanes market.
- AB Specialty Silicones
- Air Liquide
- BRB International
- Chemcon Speciality Chemicals
- Dow
- Evonik Industries AG
- Gelest Inc.
- Hexion Inc.
- Linde plc
- Matheson Tri-Gas Inc.
- Momentive
- Shin-Etsu Chemical Co., Ltd.
- Wacker Chemie AG
- WinDow Silicone.
- Zhejiang XinAn Chemical Industrial Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging paints and industrial coatings demand
- 4.2.2 Electronics miniaturisation and 5G semiconductor packaging
- 4.2.3 Light-weighting in electric vehicles tyres and green tires
- 4.2.4 Water-borne adhesive adoption in construction
- 4.2.5 Organofunctional silanes in green hydrogen electrolyser seals
- 4.3 Market Restraints
- 4.3.1 Stringent REACH limits on VOC and methanol content
- 4.3.2 Tetrachlorosilane handling hazards and logistics costs
- 4.3.3 Semiconductor-grade silane price volatility
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Functional Group
- 5.1.1 Vinyl
- 5.1.2 Amino
- 5.1.3 Epoxy
- 5.1.4 Mercepto
- 5.1.5 Alkoxy
- 5.1.6 Others (Isocyanate, Acryloxy, etc.)
- 5.2 By Application
- 5.2.1 Coupling Agents
- 5.2.2 Adhesion Promoters
- 5.2.3 Moisture Scavengers
- 5.2.4 Hydrophobing and Dispersing Agents
- 5.2.5 Silicate Stabilizers
- 5.2.6 Anti-corrosion and Surface Treatments
- 5.3 By End-user Industry
- 5.3.1 Paints and Coatings
- 5.3.2 Rubber and Plastics
- 5.3.3 Electronics
- 5.3.4 Chemicals
- 5.3.5 Other End-user Industries (Energy, Agrochemicals, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Thailand
- 5.4.1.6 Indonesia
- 5.4.1.7 Vietnam
- 5.4.1.8 Malaysia
- 5.4.1.9 Philippines
- 5.4.1.10 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Turkey
- 5.4.3.9 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Egypt
- 5.4.5.7 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AB Specialty Silicones
- 6.4.2 Air Liquide
- 6.4.3 BRB International
- 6.4.4 Chemcon Speciality Chemicals
- 6.4.5 Dow
- 6.4.6 Evonik Industries AG
- 6.4.7 Gelest Inc.
- 6.4.8 Hexion Inc.
- 6.4.9 Linde plc
- 6.4.10 Matheson Tri-Gas Inc.
- 6.4.11 Momentive
- 6.4.12 Shin-Etsu Chemical Co., Ltd.
- 6.4.13 Wacker Chemie AG
- 6.4.14 WinDow Silicone.
- 6.4.15 Zhejiang XinAn Chemical Industrial Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


