

|
시장보고서
상품코드
2115001
폴리우레아 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Polyurea - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
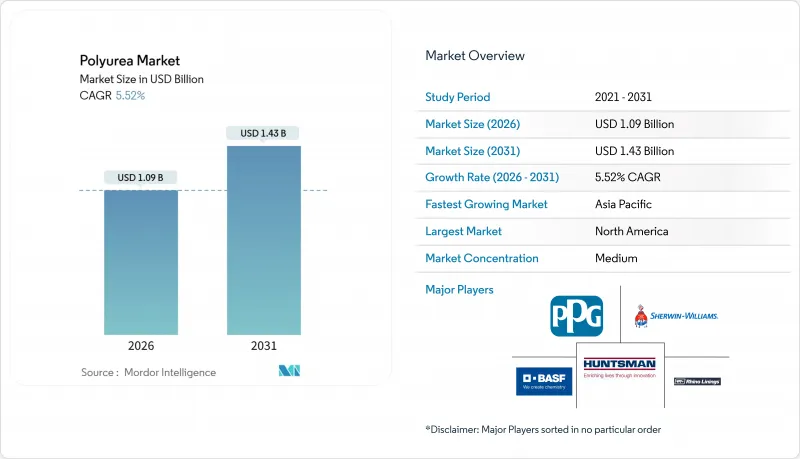
에 의하면, 폴리우레아 시장 규모는 2026년에 10억 9,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 5.52%로 성장을 지속하여, 2031년까지 14억 3,000만 달러에 이를 전망입니다.
본 보고서는 화학 구조(방향족 및 지방족), 유형(핫 폴리우레아 및 콜드 폴리우레아), 제품 형태(코팅, 라이닝, 실란트), 최종 이용 산업(건설, 페인트 및 코팅,자동차, 산업용 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(미 달러) 기준으로 제시되어 있습니다.
세계 폴리우레아 시장 동향 및 인사이트
인프라 개보수에 따른 수요 증가
노후화된 사회 인프라로 인해 소유주들은 폴리우레아를 채택하고 있습니다. 그 이유는 공사가 며칠이 아닌 몇 시간 이내에 재개될 수 있기 때문입니다. 두바이의 2025년 하타담 파이프라인 보수 공사에서는 24킬로미터 길이의 터널 내부에 폴리우레아를 내장하여 서비스의 연속성을 유지했습니다. 영국의 템즈 워터(Thames Water)사는 화학 기술을 활용하여 밀집된 도시 지역의 통로에 있는 밸브실을 방수 처리함으로써 굴착 범위를 최소화했습니다. 미국에서는 교량, 배수로, 터널 정비에 있어 여전히 2조 6,000억 달러의 자금 부족에 직면해 있습니다. 폴리우레아는 차선 폐쇄 없이 자산의 수명을 20년에서 30년으로 연장하며, 자재비 상승분을 3배 이상 상회하는 경우가 많은 간접 비용을 절감합니다. 또한, 습한 표면에 대한 적응성과 저온 경화가 가능하기 때문에 시공 가능한 계절의 폭이 넓어져, 한랭지 시장에서 매우 중요한 장점이 되고 있습니다. 각 도시가 경기 부양 자금을 교량 상판 오버레이 공사의 신속한 시행에 투입하는 가운데, 폴리우레아는 공사 완료 다음 날 통행 재개라는 요건을 충족하는 유일한 코팅재로 자리매김하고 있습니다.
석유 및 가스 중류 사업자의 부식 방지 지출 급증
1970년부터 1985년까지 부설된 중류 파이프라인망은 유지 관리 측면에서 중대한 전환점에 접어들고 있습니다. 폴리우레아 코팅막은 특히 원주 용접부나 복잡한 형상에서 용착 에폭시 피복재보다 확실하게 핀홀을 제거하고 음극 박리를 방지합니다. TIB Chemicals사의 ‘PROTEGOL’ 폴리우레탄 파이프라인 코팅은 북미의 개보수 공사에서 현장 적용의 성공을 입증하며, 폴리우레아와 사워 가스의 화학적 호환성을 뒷받침했습니다. 현재 사업자들은 가동 중단 시간을 단축하기 위해 인라인 검사, 그릿 블라스팅 및 폴리우레아 상도 도포 작업을 단일 작업 단계로 통합하여 실시했습니다. API 1169 검사 기준에서는 외부 보호를 위한 ‘이음매 없는 코팅막’에 대한 언급이 증가하고 있으며, 이 표현은 암묵적으로 폴리우레아 시스템을 권장하는 것입니다. 폴리우레아는 파이프의 주변 온도에서 수 초 이내에 경화되는 특성이 있어, 작업 팀은 같은 교대 근무 시간 내에 트렌치를 다시 메울 수 있으며, 에폭시에 비해 복구 비용을 20% 절감할 수 있습니다.
이소시아네이트 및 아민 원자재 가격 변동
BASF는 인플레이션과 물류 측면의 압박을 상쇄하기 위해 2024년 7월 북미 가격을 파운드당 0.10달러 인상한다고 발표했습니다. 원료 자산을 자체적으로 보유하지 않은 소규모 배합 제조업체는 비용을 고객에게 전가하거나 이익률을 희생하는 것 중 하나를 선택할 수밖에 없어, 아크릴계 막재가 여전히 안정적인 입지를 유지하고 있는 주택용 방수 분야에서 채택이 주춤하고 있습니다. 시공 업체들은 60일간 가격 동결을 요구하고 있지만, 많은 공급업체들이 이에 응할 수 없어 입찰 절차가 복잡해지고 있습니다. 또한, 이러한 가격 변동으로 인해 운전 자금도 압박받고 있습니다. 시공 업체들은 가격을 고정하기 위해 원자재를 사전에 구매해야 하며, 시공 측에서도 자금이 묶여 있기 때문입니다.
부문 분석
2025년, 방향족 등급은 폴리우레아 시장에서 66.89%의 점유율을 차지했으며, 지방족 계열 제품에 비해 20-30%의 원자재 비용 절감 효과를 누렸습니다. 방향족계 배합은 자외선 노출이 제한적이기 때문에 탱크, 2차 격리 구조물 및 지하 매설 콘크리트의 내장재로 사용되고 있습니다. 저렴한 비용 덕분에 총 설치 가격이 경쟁력을 유지하고 있으며, 이는 북미와 유럽의 광범위한 유틸리티에서 필수적인 요소입니다. 그러나 자외선에 의해 방향족계는 황변이나 초킹 현상이 발생하기 때문에 자산 소유자는 탑코트를 더 두껍게 도포하거나 외벽의 미관 저하를 감수해야 합니다.
지방족 폴리우레아는 색상 안정성이 요구되는 주차장 데크, 교량, 건물 외장 등 덕분에 연평균 성장률(CAGR) 6.12%로 성장하고 있습니다. PPG가 2024년 7월에 출시한 ‘DuraNEXT’에는 코일 코팅된 금속의 광택을 유지하는 UV 경화형 클리어 코트가 추가되어, 실외용 등급 제품군에 대한 수요가 입증되었습니다. 방향족·지방족 하이브리드 블렌드는 10-15%의 비용 프리미엄으로 충분한 색상 유지력을 실현하여, 10년 단위의 재도장 주기를 희망하는 교량 소유주에게 타협점이 될 수 있는 선택지를 제공합니다. 아시아의 신규 생산 능력 가동에 따라 알킬 이소시아네이트의 비용 절감이 예상되며, 방향족이 주도권을 쥐는 요인이 되고 있는 가격 차이는 점차 축소될 것으로 전망됩니다.
2025년, 핫 폴리우레아 시스템은 폴리우레아 시장 규모의 59.51%를 차지했습니다. 이는 고압 장치를 사용하여 시간당 1,000제곱피트 이상을 도포할 수 있고, 이음매 없는 마감을 실현할 수 있기 때문입니다. 해상 풍력 발전용 블레이드의 침식 방지 실드, 교량 데크의 코팅, 벌크 탱크의 라이닝에서는 코팅의 응집성이 절대적으로 요구되므로 핫 스프레이가 지정되어 있습니다. 성분의 온도는 65-75°C로 유지되어 점도를 낮추고, 25 MPa를 초과하는 인장 강도를 발휘하는 고분자량 프리폴리머를 미분화합니다.
콜드 포어 시스템은 사용 편의성을 강점으로 삼아 연평균 성장률(CAGR) 6.67%로 성장을 지속하고, 있습니다. 다성분 혼합 장비가 없는 시공 업체는 전기차(EV)용 배터리 팩, 2차 격리 구조물 또는 HVAC 덕트에 대해 수작업으로 흙손 도포나 저압 스프레이 시공을 수행할 수 있습니다. 헌츠맨(Huntsman)사의 ‘POLYRESYST S4010C’ 콜드큐어는 5분 이내에 탈형이 가능하여 자동차 인라인 코팅을 실현합니다. 단점으로는 여전히 표면 마감 및 기계적 특성이 다소 떨어지는 점이 꼽히지만, 지속적인 연구 개발을 통해 그 격차는 점차 좁혀지고 있습니다. 낮은 설비 투자 비용은 특히 인도, 인도네시아, 브라질에서 매력적입니다. 이들 국가에서는 인프라 예산의 제약으로 인해, 제한된 설비 투자 범위 내에 들어맞는 기술이 우선적으로 채택되고 있습니다.
지역별 분석
북미는 2025년 시장 가치의 40.92%를 차지하고 있으며, 이는 성숙한 시공업체 네트워크와 가동 중단 비용 계산상 속경화형 화학제품이 유리하게 작용하는 높은 인건비에 힘입은 것입니다. ‘인프라 투자 및 고용법’에 따라 교량 및 고속도로 보수에 1,100억 달러가 배정되어, 데크 오버레이 및 신축 이음매용 실란트에 대한 안정적인 수요가 확보되고 있습니다. 캐나다의 지방 자치단체 인프라 은행도 칼버트 라이닝 공사에 자금을 지원하고 있으며, 한편 멕시코에서는 산업 단지의 급속한 성장으로 인해 전자 및 자동차 산업 집적지에서의 내화학성 바닥재 수요가 증가하고 있습니다. BASF, 코베스트로, 헌츠맨, PPG는 텍사스주, 루이지애나주, 온타리오주 전역에 통합 수지 제조 시설을 운영하고 있으며, 프리폴리머와 경화제를 적시(JIT)로 출하할 수 있어 대부분의 프로젝트에서 리드타임을 3일로 단축하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 7.93%로 가장 빠른 매출 성장을 보이고 있습니다. 중국의 ‘일대일로’ 회랑, 인도의 전용 화물 철도 시스템, 그리고 한국의 200억 달러 규모 전기차 배터리 공급망 구축이 대규모 코팅 예산을 견인하고 있습니다. BASF가 2025년에 차오징(Caojing)의 수지 생산 능력을 연간 1만 8,800톤으로 확대할 계획인 것은 해당 지역공급 기반을 강화하는 것입니다. 델리, 첸나이, 광저우에서 진행 중인 정부 주도의 지하철 확장 프로젝트에서는 강우로 인한 지반 침하 문제를 해결하기 위해 터널 방수재로 폴리우레아가 지정되었습니다. 동남아시아의 건설업체들은 여전히 장비 가격에 민감하기 때문에 콜드 포어형 제품의 채택이 확대되고 있습니다. 지역의 특수 자재 공급업체들은 일본 무역회사와 제휴하여 시공업체 육성 및 시방서 작성을 가속화하고 있습니다.
유럽은 VOC 규제와 노후화된 인프라의 개보수 주기를 배경으로, 성숙해 가고 있지만 수익성이 높은 시장을 유지하고 있습니다. 독일 아우토반 교량의 개보수 및 북유럽 국가들의 기후 변화 적응 프로그램에서는 내동결성 데크 코팅재로 폴리우레아가 채택되고 있습니다. 스페인과 이탈리아의 선박 개보수 시장은 견조한 양상을 보이고 있으며, 조선소들은 팬데믹으로 인한 가동 중단으로 수익을 잃은 크루즈선의 턴어라운드 기간 단축을 위해 투자를 진행하고 있습니다. 중동 국가들에서는 해수 담수화 플랜트의 내부 라이닝 및 탱크 팜에 폴리우레아가 채택되고 있으며, 사우디아라비아의 아람코(Aramco)와 UAE의 ADNOC은 이미 스프레이 시스템의 시범 운영을 진행하고 있습니다. 남미에서는 칠레의 구리 광산 확장 및 브라질의 해양 개발과 관련된 지역적 수요가 나타나고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.26According to Mordor Intelligence, the polyurea market size is estimated at USD 1.09 billion in 2026, and is expected to reach USD 1.43 billion by 2031, at a CAGR of 5.52% during the forecast period (2026-2031).
This report is Segmented by Chemical Structure (Aromatic and Aliphatic), Type (Hot Polyurea and Cold Polyurea), Product Form (Coatings, Linings, and Sealants), End-Use Industry (Construction, Paints and Coatings, Automotive, Industrial, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Polyurea Market Trends and Insights
Growing Demand from Infrastructure Rehabilitation
Aging civil infrastructure drives owners to polyurea because projects can reopen within hours, not days. Dubai's 2025 Hatta Dam pipeline restoration lined 24 kilometers of tunnels with polyurea and maintained service continuity. Thames Water in the United Kingdom used chemistry to waterproof valve chambers in dense urban corridors and limit excavations. The United States still faces a USD 2.6 trillion funding gap for bridges, culverts, and tunnels; polyurea extends asset life by two to three decades without lane closures, reducing indirect costs that often exceed material premiums threefold. The formulation's tolerance for damp surfaces and low-temperature cures widens the seasonal work window, which is critical in cold-climate markets. As cities earmark stimulus funds for fast-track bridge deck overlays, polyurea is positioned as the only membrane that meets overnight-reopening requirements.
Surge in Corrosion-Control Spending by Oil and Gas Midstream Operators
Midstream pipeline networks installed between 1970 and 1985 are reaching critical maintenance thresholds. Polyurea membranes eliminate pinholes and prevent cathodic disbondment more reliably than fusion-bonded epoxy wraps, especially on girth welds and complex geometries. TIB Chemicals' PROTEGOL polyurethane pipeline coatings demonstrated field success on North American retrofits and underscored polyurea's chemical compatibility with sour gas. Operators now bundle inline inspection, grit blasting, and polyurea over-sprays into single mobilizations to reduce downtime. API 1169 inspection standards increasingly reference seamless membranes for external protection, a wording that implicitly favors polyurea systems. Because polyurea cures within seconds at ambient pipe temperature, crews can backfill trenches on the same shift, cutting restoration expenses by 20% relative to epoxy.
Volatility in Isocyanate and Amine Feedstock Prices
BASF announced a USD 0.10/lb price hike for North America in July 2024 to offset inflation and logistics pressures. Smaller formulators without integrated feedstock assets either pass costs to customers or forfeit margin, slowing adoption in residential waterproofing, where acrylic membranes remain stable. Contracting firms ask for 60-day price holds that many suppliers cannot honor, complicating tender processes. Volatility has also squeezed working capital because contractors must pre-buy raw materials to lock pricing, tying up cash on the application side as well.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption in EV Battery-Pack Protection
- Mainstream Shift from Epoxy/Polyurethane to Fast-Return Polyurea Coatings
- Short Pot-Life Raises Applicator Skill and Equipment Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aromatic grades delivered 66.89% polyurea market share in 2025 and benefitted from raw-material savings of 20-30% versus aliphatic analogs. Aromatic formulations line tanks, secondary containments, and buried concrete because UV exposure is limited. Their lower cost keeps total installed pricing competitive, which is essential for large-surface municipal projects in North America and Europe. However, ultraviolet light yellows and chalks aromatics, so asset owners must overspray topcoats or accept aesthetic degradation on facades.
Aliphatic polyurea is growing at a 6.12% CAGR thanks to parking decks, bridges, and external building skins that require color stability. PPG's July 2024 DuraNEXT launch added UV-curable clearcoats that maintain gloss on coil-coated metal, confirming demand for exterior-grade clusters. Hybrid aromatic-aliphatic blends deliver adequate color retention at a 10-15% cost premium, offering a middle path for bridge owners who want a decade-long repaint window. Cost declines for aliphatic isocyanates are projected as new Asian capacity comes online, gradually narrowing the price gap that underpins aromatic leadership.
Hot polyurea systems held 59.51% of the polyurea market size in 2025 because high-pressure rigs can apply more than 1,000 ft2 per hour with seamless results. Offshore wind blade erosion shields, bridge-deck membranes, and bulk tank linings specify hot-spray because membrane cohesion must be absolute. Component temperatures run at 65-75 °C to cut viscosity and atomize heavy pre-polymers that deliver tensile strengths above 25 MPa.
Cold-pour systems are posting a 6.67% CAGR on the promise of ease of use. Contractors without plural-component equipment can hand-trowel or low-pressure-spray EV battery packs, secondary containments, or HVAC ducts. Huntsman's POLYRESYST S4010C cold-cure provides sub-5-minute demolding, enabling inline automotive coating. The downside remains surface finish and slightly lower mechanical properties, yet incremental research and development is closing the gap. Lower rig investment is especially attractive in India, Indonesia, and Brazil, where infrastructure budgets reward technologies that fit within modest capex envelopes.
Complete Report Scope:
- By Chemical Structure
- Aromatic
- Aliphatic
- By Type
- Hot Polyurea
- Cold Polyurea
- By Product Form
- Coatings
- Linings
- Sealants
- By End-use Industry
- Construction
- Paints and Coatings
- Automotive
- Industrial
- Maritime
- Other End User Industries (Energy and Power, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America controlled 40.92% of the 2025 value, supported by mature applicator networks and high labor costs that tilt cost-of-downtime equations in favor of rapid-cure chemistries. The Infrastructure Investment and Jobs Act directs USD 110 billion toward bridge and highway repair, ensuring steady demand for deck overlays and expansion-joint sealants. Canada's municipal infrastructure bank also funds culvert relining, while Mexico's industrial-park boom pushes demand for chemical-resistant floors in electronics and automotive corridors. BASF, Covestro, Huntsman, and PPG run integrated resin facilities across Texas, Louisiana, and Ontario, allowing just-in-time shipment of pre-polymers and curatives, which reduces lead times to three days for most projects.
Asia-Pacific is generating the fastest revenue expansion at a 7.93% CAGR through 2031. China's Belt and Road corridor, India's dedicated freight rail system, and Korea's USD 20 billion EV battery supply-chain buildout are channeling large coating budgets. BASF's 2025 move to raise Caojing resin capacity to 18,800 tons per year underpins regional supply. Government-sponsored metro expansions in Delhi, Chennai, and Guangzhou have specified polyurea for tunnel waterproofing owing to rainfall-induced ground settlement events. Southeast Asian contractors remain equipment-price sensitive, so cold-pour variants see heightened uptake. Regional specialty suppliers are partnering with Japanese trading houses to train applicators and accelerate specification writing.
Europe maintains a mature yet profitable market, rooted in VOC caps and refurbishment cycles for legacy infrastructure. Germany's autobahn bridge retrofits and the Nordic region's climate-adaptation programs employ polyurea for frost-resistant deck coatings. Maritime refurbishment in Spain and Italy is steady as shipyards invest in quicker turnaround for cruise vessels that lost revenue during pandemic shutdowns. Middle East states are adopting polyurea for desalination plant linings and tank farms; Saudi Arabia's Aramco and ADNOC in the UAE are already piloting spray systems. South America shows localized demand tied to Chilean copper-mine expansion and Brazilian offshore developments.
- Advanced Polymers Solutions
- Armorthane Inc.
- BASF SE
- Bayer MaterialScience (Covestro legacy)
- Carlisle Companies (Accella/Arma)
- Covestro AG
- Dorf Ketal Chemicals
- Elastothane Ltd.
- Huntsman International LLC
- Nukote Coating Systems
- Polycoat Products
- PPG Industries Inc.
- Rhino Linings Corporation
- Satyen Polymers (TEVO)
- Sherfab
- Specialty Products Inc.
- SPI Performance Coatings (UK)
- Teknos Group
- The Sherwin-Williams Company
- VIP Coatings
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand from infrastructure rehabilitation
- 4.2.2 Surge in corrosion-control spending by oil and gas midstream operators
- 4.2.3 Rapid adoption in EV battery-pack protection
- 4.2.4 Mainstream shift from epoxy / polyurethane to fast-return polyurea coatings
- 4.2.5 Regulatory push for VOC-free protective coatings
- 4.3 Market Restraints
- 4.3.1 Volatility in isocyanate and amine feedstock prices
- 4.3.2 Short pot-life raises applicator skill and equipment cost
- 4.3.3 Emerging PFAS-like substance bans impacting certain chain extenders
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Chemical Structure
- 5.1.1 Aromatic
- 5.1.2 Aliphatic
- 5.2 By Type
- 5.2.1 Hot Polyurea
- 5.2.2 Cold Polyurea
- 5.3 By Product Form
- 5.3.1 Coatings
- 5.3.2 Linings
- 5.3.3 Sealants
- 5.4 By End-use Industry
- 5.4.1 Construction
- 5.4.2 Paints and Coatings
- 5.4.3 Automotive
- 5.4.4 Industrial
- 5.4.5 Maritime
- 5.4.6 Other End User Industries (Energy and Power, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Advanced Polymers Solutions
- 6.4.2 Armorthane Inc.
- 6.4.3 BASF SE
- 6.4.4 Bayer MaterialScience (Covestro legacy)
- 6.4.5 Carlisle Companies (Accella/Arma)
- 6.4.6 Covestro AG
- 6.4.7 Dorf Ketal Chemicals
- 6.4.8 Elastothane Ltd.
- 6.4.9 Huntsman International LLC
- 6.4.10 Nukote Coating Systems
- 6.4.11 Polycoat Products
- 6.4.12 PPG Industries Inc.
- 6.4.13 Rhino Linings Corporation
- 6.4.14 Satyen Polymers (TEVO)
- 6.4.15 Sherfab
- 6.4.16 Specialty Products Inc.
- 6.4.17 SPI Performance Coatings (UK)
- 6.4.18 Teknos Group
- 6.4.19 The Sherwin-Williams Company
- 6.4.20 VIP Coatings
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


