

|
시장보고서
상품코드
2115006
도데칸이산(DDDA) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Dodecanedioic Acid (DDDA) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
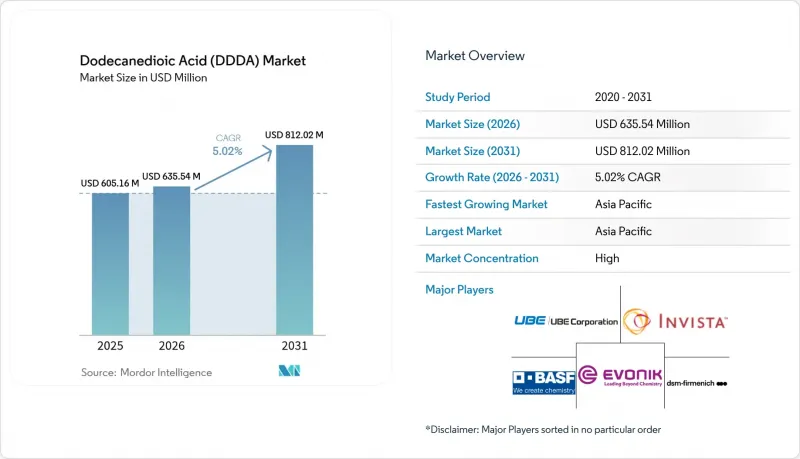
에 의하면, 2026년 도데칸이산 시장 규모는 6억 3,554만 달러로 추정되고, 2025년 6억 516만 달러에서 성장하여 2031년에는 8억 1,202만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 5.02%를 나타낼 전망입니다.
본 보고서는 제조 공정별(석유화학계, 바이오), 용도별(수지, 분체 도장, 접착제, 윤활제, 기타 용도), 최종 사용자 산업별(자동차 및 운송, 전기 및 전자, 산업용 기계, 건축 및 건설, 헬스케어·퍼스널케어), 그리고 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다.
세계의 도데칸이산(DDDA) 시장 동향 및 인사이트
자동차 경량화에 따른 고성능 나일론-12 및 나일론-6,12 수요 증가
자동차 제조업체들은 차량 총중량 감축 목표를 더욱 엄격하게 설정하고 있으며, 그 결과 고성능 폴리아미드, 특히 나일론-12 및 나일론-6,12의 사용량이 증가하고 있습니다. BASF가 헥사메틸렌디아민의 신규 생산 능력 확대에 2억 6,000만 달러를 투자하고 있으며, INVISTA가 HMD(헥사메틸렌디아민) 자산의 재가동을 추진하고 있는 것은 현재 진행 중인 공급망 투자를 상징하는 사례입니다. 자동차 제조업체들은 충돌 안전성을 저해하지 않으면서 2030년까지 차량의 공차 중량을 7-10% 감축하는 것을 목표로 하고 있으며, DDDA를 기반으로 한 폴리아미드 배합재를 공급하는 통합 화학 공급업체들이 우선적인 파트너로 부상하고 있습니다. 이러한 요인으로 인해 예측 연평균 성장률(CAGR)은 1.7포인트 상승했으며, 연료 라인, 브레이크 호스, 배터리 인클로저 등의 용도에서 구체적인 수요 증가가 예상됩니다.
분체 도장이 채택되는 가전 및 가정용 전기제품의 확대
각 가전 브랜드는 VOC(휘발성 유기 화합물) 배출량 감축과 더 얇고 긁힘에 강한 마감 처리를 실현하기 위해 용제형 도료에서 분체 도장으로 전환하고 있습니다. DDDA는 초박형 아크릴 분체 도막을 지지하는 경화제로 기능하며, 제조업체가 소형화 및 지속가능성 목표를 달성할 수 있도록 지원합니다. 유럽 및 북미의 규제 압력에 더해, 아시아태평양의 전자 산업 거점이 누리는 생산 규모 우위가 맞물리면서 특수 DDDA 등급에 대한 수요가 증가하고 있습니다. 분체 도장된 가전제품과 스마트폰이 결합되어 전체 연평균 성장률(CAGR)을 0.8포인트 끌어올리고 있습니다.
DDDA 취급 및 독성 위험성
DDDA는 REACH 규정에 따라 ‘심각한 눈 자극 물질’로 분류되며, 2025년 개정안에 따라 문서화 및 현장 감사 요건이 더욱 엄격해질 예정입니다. 전용 EH&S(환경·건강·안전) 인프라를 갖추지 않은 중소기업은 규정 준수 비용 증가에 직면하게 되며, 제품 승인 주기가 최대 18개월까지 길어질 가능성이 있습니다. 이 물질은 급성 독성이 낮고 생분해성도 양호하지만, 눈 보호 프로그램, 자동 적재 시스템, 지속적인 모니터링과 같은 의무적인 위험 관리 조치로 인해 운영 비용이 증가합니다. 이러한 제약 요인으로 인해 예상 성장률은 0.9퍼센트 포인트 하락할 것으로 보입니다.
부문별 분석
사이클로도데카트리에네를 통한 석유화학 경로는 북미 및 중동의 천연가스 경제성 우위에 힘입어 2025년 도데칸이산 시장 점유율의 60.58%를 차지했습니다. 바이오 경로는 절대 생산량은 적지만, 자동차 및 전자 분야에서 지속가능성을 중시하는 프리미엄 수요를 흡수하여 연평균 성장률(CAGR) 8.60%를 나타낼 것으로 예측됩니다. 유전자 변형된 Wickerhamiella sorbophila 균주를 활용하는 바이오 생산자들은 2024년 이후 전환 비용을 약 3분의 1로 절감하며, 시장 점유율 확대를 위한 기반을 다지고 있습니다.
현재의 경쟁 환경은 양극화되어 있는 것으로 보입니다. 대량 생산되고 비용에 민감한 수지 및 접착제용 등급은 계속해서 석유화학제품이 공급하는 반면, 저탄소 고순도 바이오 등급은 전기차용 윤활유, 항공우주용 포토폴리머, 고급 분체 도장 분야에서 사양 채택이 진행되고 있습니다. 따라서 자본 배분 결정은 지역의 에너지 가격, 규제 동향, 그리고 고객의 지속가능성 관련 공약에 따라 좌우됩니다. 두 가지 생산 경로를 모두 갖춘 기업은 원료 스프레드나 탄소 가격 제도에 큰 변화가 발생할 경우, 수익성이 더 높은 생산 경로로 전환할 수 있는 유연성을 확보하고 있습니다.
지역별 분석
2025년, 아시아태평양은 도데칸이산 시장에서 52.86%의 점유율을 차지하며 주도적인 위치를 차지했고, 2031년까지 연평균 성장률(CAGR) 5.28%로 확대될 것으로 예측됩니다. 중국의 방대한 화학 제조거점과 일본의 첨단 소재 생태계가 결합되어, 이 지역에서는 지속적인 생산 능력 확대가 예상됩니다. 각 지역의 기업들은 통합된 석유화학 단지, 전자기기 및 자동차 수출 거점과의 근접성, 숙련된 노동력 확보와 같은 이점을 누리고 있으며, 이를 통해 원료 수입의 변동이 부분적으로 상쇄되고 있습니다.
북미는 석유화학 루트에 유리한 셰일 가스의 비용 경쟁력을 바탕으로 규모는 작지만 견고한 시장 점유율을 확보하고 있습니다. 미국 국방부가 8,620만 달러 규모의 세바신산 리쇼어링 보조금을 지급한 것은 해당 지역 공급 안정성에 대한 우려를 부각시키고 있으며, 주요 밸류체인에서 후방 통합을 촉진할 가능성이 있습니다. 또한 생산자들은 대량 생산품이 아닌 고부가가치의 틈새 등급에 설비 투자를 집중하고 있으며, 이는 차별화된 제품으로의 전략적 전환을 반영하고 있습니다. 시장 진입은 연구 개발(R&D) 수익을 보호하는 종합적인 규제 및 지적 재산권 체제에 의해 뒷받침되고 있습니다.
유럽은 성숙하고 혁신 주도적인 시장 환경을 보이고 있습니다. 강화된 REACH 규정 개정, 에너지 비용 상승, 그리고 ‘그린 딜’에 따른 바이오 함유율 의무화가 맞물리면서 제조업체들은 바이오 제조 공정 및 특수 용도로 유도되고 있습니다. BASF의 프랑스 거점에서의 설비 갱신은 구조적인 비용 압박에도 불구하고, 현지 공급 탄력성에 대한 회사의 노력을 보여줍니다. 성장 속도는 아시아태평양에 비해 완만하지만, 이 지역은 첨단 폴리아미드, 전기차용 유체 및 순환 경제 이니셔티브 분야에서 기술적 리더십을 유지하고 있습니다. 남미 및 중동 및 아프리카는 합산 시장 점유율은 미미하지만, 산업화 및 인프라 구축과 관련된 기회가 곳곳에 산재해 있습니다. 다만, 환율 변동 및 정치적 리스크가 우려 요인으로 작용하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.28According to Mordor Intelligence, dodecanedioic acid market size in 2026 is estimated at USD 635.54 million, growing from 2025 value of USD 605.16 million with 2031 projections showing USD 812.02 million, growing at 5.02% CAGR over 2026-2031.
This report is Segmented by Production Process (Petro-Chemical, Bio-Based), Application (Resin, Powder Coating, Adhesives, Lubricants, Other Applications), End-User Industry (Automotive and Transportation, Electrical and Electronics, Industrial Machinery, Building and Construction, Healthcare and Personal Care), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa).
Global Dodecanedioic Acid (DDDA) Market Trends and Insights
Growth in High-Performance Nylon-12 & Nylon-6,12 Demand from Automotive Lightweighting
Automakers are setting tighter fleet-weight targets that translate into higher usage of high-performance polyamides, notably nylon-12 and nylon-6,12. BASF's USD 260 million commitment to new hexamethylenediamine capacity and INVISTA's recommissioning of HMD assets are emblematic of the supply-chain investments now underway. Vehicle manufacturers aim to trim 7-10% curb weight by 2030 without compromising crashworthiness, and integrated chemical suppliers offering DDDA-based polyamide formulations emerge as preferred partners. The driver adds 1.7 percentage points to forecast CAGR, with tangible demand growth visible in fuel-line, brake-hose, and battery-enclosure applications.
Expansion of Powder-Coated Consumer Electronics & Appliances
Consumer-electronics brands are migrating from solvent-borne to powder coatings to cut VOC emissions and secure thinner, scratch-resistant finishes. DDDA serves as a curing agent that supports ultra-thin acrylic powder layers, helping manufacturers meet miniaturization and sustainability targets. Regulatory pressure in Europe and North America complements the production-scale advantages enjoyed by Asia-Pacific electronics hubs, lifting demand for specialized DDDA grades. Powder-coated appliances and smartphones together propel a 0.8 percentage-point boost to overall CAGR.
Handling & Toxicological Hazards of DDDA
DDDA is classified as a serious eye irritant under REACH, and the 2025 revision tightens documentation and on-site audit requirements. Smaller firms without dedicated EH&S infrastructure face higher compliance costs, potentially lengthening product-approval cycles by up to 18 months. While the substance exhibits low acute toxicity and good biodegradability, mandatory risk management measures-eye-protection programs, automated loading systems, and continuous monitoring-raise operating expenses. The restraint subtracts 0.9 percentage points from projected growth.
Other drivers and restraints analyzed in the detailed report include:
- EV-Thermal-Management Lubricants Adopting DDDA-Based Esters
- Bio-Route Process Cost Decline via Synthetic Biology Breakthroughs
- Feedstock Price Volatility (Sebacic Acid / Cyclododecane)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The petro-chemical pathway via cyclododecatriene held 60.58% of the dodecanedioic acid market share in 2025, supported by advantaged natural-gas economics in North America and the Middle East. Bio-based routes, while smaller in absolute tonnage, are forecast to post an 8.60% CAGR, capturing sustainability-driven premiums in automotive and electronics. Bio-producers leveraging engineered Wickerhamiella sorbophila strains have trimmed conversion costs by roughly one-third since 2024, setting the stage for further share accretion.
Competitive positioning now appears bifurcated: high-volume, cost-sensitive resin and adhesive grades continue to be met by petro-chemical output, while low-carbon, high-purity bio-grades win specification in EV lubricants, aerospace photopolymers and premium powder coatings. Capital allocation decisions therefore hinge on regional energy prices, regulatory trajectories and customer sustainability pledges. Firms with dual-route capabilities achieve optionality to swing production toward the more profitable pathway whenever feedstock spreads or carbon-pricing schemes shift materially.
Complete Report Scope:
- By Production Process
- Petro-chemical (cyclododecatriene route)
- Bio-based (sebacic-acid and microbial routes)
- By Application
- Resin
- Powder Coating
- Adhesives
- Lubricants
- Other Applications (Pharmaceutical, Cosmetics, etc.)
- By End-User Industry
- Automotive and Transportation
- Electrical and Electronics
- Industrial Machinery
- Building and Construction
- Healthcare and Personal Care
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated the dodecanedioic acid market in 2025 with a 52.86% share and is expected to rise at a 5.28% CAGR to 2031. China's vast chemical-manufacturing base, coupled with Japan's advanced-materials ecosystem, positions the region for sustained capacity additions. Regional players benefit from integrated petro-chemical complexes, proximity to electronics and automotive export hubs, and skilled labor availability, partly offsetting feedstock-import volatility.
North America secured a smaller but resilient share, anchored by shale-gas cost advantages that favor petrochemical routes. The U.S. Department of Defense's USD 86.2 million sebacic-acid reshoring grant underscores regional supply-security concerns and may catalyze backward integration in key value chains. Producers are also channeling capex into high-value niche grades rather than bulk tonnage, reflecting a strategic shift toward differentiated products. Market participation is underpinned by comprehensive regulatory and intellectual-property frameworks that safeguard returns on R&D.
Europe represents a mature but innovation-driven landscape. Stringent REACH updates, higher energy costs, and the Green Deal's bio-content mandates collectively nudge manufacturers toward bio-based pathways and specialty applications. BASF's French site upgrades demonstrate commitment to local supply resilience despite structural cost pressures. While growth is slower than in Asia-Pacific, the region maintains technological leadership in advanced polyamides, EV fluids and circular-economy initiatives. South America and the Middle East & Africa together account for a modest share yet present pockets of opportunity linked to industrialization and infrastructure builds, tempered by currency volatility and political risk.
- Arkema
- BASF
- China Petroleum & Chemical Corporation
- DSM
- Evonik Industries AG
- Haihang Industry
- INVISTA
- Merck KGaA
- Shandong Guangtong New Materials Co.,Ltd.
- Tokyo Chemical Industry (India) Pvt. Ltd.
- UBE Corporation
- Verdezyne
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in high-performance Nylon-12 and Nylon-6,12 demand from automotive lightweighting
- 4.2.2 Expansion of powder-coated consumer electronics and appliances
- 4.2.3 EV-thermal-management lubricants adopting DDDA-based esters
- 4.2.4 Bio-route process cost decline via synthetic biology breakthroughs
- 4.2.5 Adoption in aerospace 3-D printing photopolymers
- 4.3 Market Restraints
- 4.3.1 Handling and toxicological hazards of DDDA
- 4.3.2 Feedstock price volatility (sebacic acid / cyclododecane)
- 4.3.3 Supply-chain risk from cyclododecane outage incidents
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Production Process
- 5.1.1 Petro-chemical (cyclododecatriene route)
- 5.1.2 Bio-based (sebacic-acid and microbial routes)
- 5.2 By Application
- 5.2.1 Resin
- 5.2.2 Powder Coating
- 5.2.3 Adhesives
- 5.2.4 Lubricants
- 5.2.5 Other Applications (Pharmaceutical, Cosmetics, etc.)
- 5.3 By End-User Industry
- 5.3.1 Automotive and Transportation
- 5.3.2 Electrical and Electronics
- 5.3.3 Industrial Machinery
- 5.3.4 Building and Construction
- 5.3.5 Healthcare and Personal Care
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 China Petroleum & Chemical Corporation
- 6.4.4 DSM
- 6.4.5 Evonik Industries AG
- 6.4.6 Haihang Industry
- 6.4.7 INVISTA
- 6.4.8 Merck KGaA
- 6.4.9 Shandong Guangtong New Materials Co.,Ltd.
- 6.4.10 Tokyo Chemical Industry (India) Pvt. Ltd.
- 6.4.11 UBE Corporation
- 6.4.12 Verdezyne
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


