

|
시장보고서
상품코드
2115058
자동차용 패스너 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Fasteners - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 자동차용 패스너 시장 규모는 2025년 588억 9,000만 달러에서 2026년에는 613억 7,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 4.21%로 성장을 지속하여, 2031년까지 754억 2,000만 달러에 이를 것으로 예측됩니다.
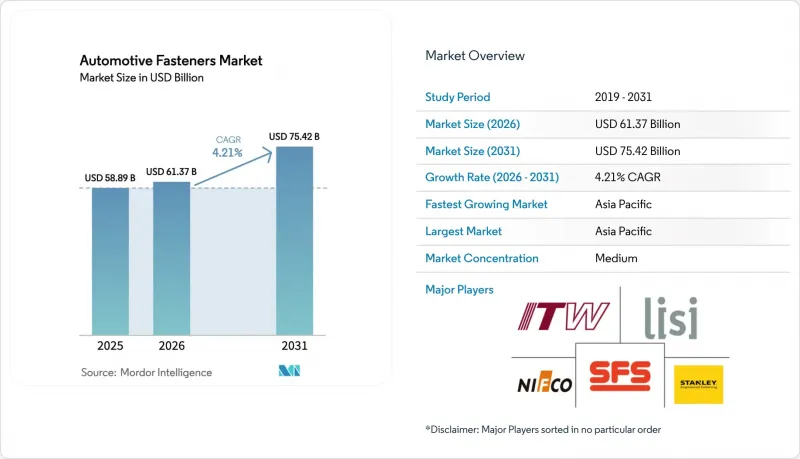
본 보고서는 패스너의 유형(나사식 등), 차량의 유형(이륜차 등), 구동 방식(내연기관 차량 등), 기능(탈부착 가능·불가능), 재질, 코팅/마감, 용도, 유통 채널 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(단위)으로 제시됩니다.
세계 자동차용 패스너 시장 동향 및 인사이트
경량화가 첨단 패스너 수요를 가속화
미국 기업의 평균 연비 기준(CAFE) 개정 및 유럽연합(EU)의 2025년 차량군 평균 CO2 배출량 목표에 따라, 자동차 제조업체들은 차량 중량을 대폭 줄여야 하는 압박을 받고 있습니다. 이러한 경량화에 대한 집중으로 인해, 차량 중량에서 차지하는 비율은 작지만 무시할 수 없는 비중을 차지하는 패스너에 관심이 쏠리고 있습니다. 알루미늄 볼트는 강철 볼트에 비해 대폭적인 경량화가 가능하지만, 갈바닉 부식을 방지하기 위해 절연 슬리브나 아연-니켈 도금이 필요합니다. 이러한 추가 조치로 인해 패스너 1개당 비용이 소폭 상승합니다. 한편, 등급 8.8의 강철 패스너보다 상당히 고가인 티타늄 패스너는 포뮬러 E 경주 분야에서 시작해 하이엔드 고급 전기차(EV)로 점차 보급되고 있습니다. 여기서 매력은 높은 비용을 정당화할 만큼의 대폭적인 경량화에 있습니다. 게다가 패스너에 대한 요구 사항도 복잡해지고 있습니다. 이전에는 몇 가지 유형의 강철 볼트 크기만으로도 충분했던 화이트 바디에도, 현재는 더욱 다양한 SKU가 요구되고 있습니다. 여기에는 알루미늄, 스테인리스 스틸 및 코팅 강판로 제작된 옵션이 포함됩니다. 이러한 확대로 인해 2차 공급업체의 운전 자본 수요가 현저히 증가하고 있으며, 그에 대한 요구 사항도 크게 높아지고 있습니다.
세계 자동차 생산의 회복
2024년, 경차 생산 대수는 대폭적인 회복세를 보였으며, 2026년까지 추가적인 성장이 예상됩니다. 이러한 회복은 최근의 반도체 부족 사태를 겪은 후, 자동차용 패스너 시장의 기본 수요가 회복되고 있음을 보여줍니다. 이 기간 동안 중국이 주요 견인자로 부상했으며, 인도와 동남아시아도 패스너 수요 증가에 중요한 역할을 했습니다. 이 지역들을 합치면 수요 증가분의 상당 부분을 차지하고 있습니다. 인도의 인프라 부양책과 캘리포니아주의 배기가스 규제의 뒷받침을 받아 상용차 생산은 특히 대형차 부문에서 두드러진 성장세를 보였습니다. 이러한 급증은 신속한 납기를 자랑하는 아시아 공급업체들에게 혜택을 가져다주며, 사전 비축에 의존하는 유럽 제조업체들에 비해 명확한 우위를 점하게 하고 있습니다. 유럽의 생산은 안정적인 수준을 유지하고 있지만, 전 세계 생산 대수 증가 추세는 긍정적인 요인으로 작용하고 있습니다.
EV 아키텍처로 인해 차량당 패스너 수가 감소
배터리식 전기차(BEV)에서는 엔진 블록, 변속기, 배기 시스템, 연료 탱크 등의 부품이 필요하지 않습니다. 이러한 변화로 인해 기존의 내연기관 차량에 비해 차량당 패스너 수가 대폭 감소하고 있습니다. 예를 들어, 테슬라의 ‘모델 Y’는 가솔린 차량의 크로스오버 모델보다 패스너 사용 수가 적어 현저한 감소를 보이고 있습니다. 게다가 구조형 배터리 설계로 인해 필요한 패스너 수는 더욱 줄어들고 있습니다. BEV에서 고강도 등급 10.9 볼트의 가치는 상승하고 있어 생산량 감소를 일부 상쇄하고 있지만, 자동차용 패스너 시장 전체에 미치는 영향은 여전히 부정적입니다.
부문 분석
나사식 패스너는 2025년 매출의 53.41%를 차지하며, 섀시, 파워트레인, 인테리어 시스템에서의 다용도성을 입증하고 있습니다. 토크-투-일드 볼트나 셀프록 너트 등 특수 용도 및 안전상 중요한 부품은 엄격한 충돌 시험 기준으로 인해 안전벨트 앵커나 배터리 팩 고정 시 필수 불가결한 요소가 되었기 때문에 2031년까지 연평균 성장률(CAGR) 4.23%를 나타낼 것으로 전망됩니다. 범용 나사 부품은 BEV(배터리 전기자동차)에서 생산 대수의 점진적인 감소에 직면하고 있지만, 하이브리드 차량 및 기존 내연기관 차량의 절대적인 수요로 인해 이 부문의 자동차용 패스너 시장 규모는 여전히 큰 임베디드입니다.
특수 패스너는 나사 고정제나 캡티브 와셔를 결합함으로써 보증 청구 및 생산 라인에서의 재작업 비용을 절감하여 2-5배 높은 가격을 실현하고 있습니다. 나사가 없는 클립이나 리벳은 내장 트림에 필수적이지만, 고급차의 바디 인 화이트(백차체)에서 접착제가 선호됨에 따라 그 성장세는 둔화되고 있습니다. 특수 제품에 부과되는 프리미엄 가격은 플랫폼이 표준화된 조달 환경에서도 이익률을 지켜주고 있습니다.
2025년에는 승용차가 전체 생산 대수의 67.73%를 차지하고, 이는 패스너의 높은 사용 밀도와 전 세계적으로 6,800만 대의 생산 대수를 반영한 것입니다. 한편, 이륜차의 경우 인도와 중국에서 스쿠터의 전동화가 진행됨에 따라 배터리 케이스 및 모터 마운트용 나사산 볼트가 추가되면서, 2031년까지 연평균 성장률(CAGR) 4.37%로 가장 높은 성장세를 기록할 전망입니다. 소형 상용차와 대형 트럭은 합쳐서 전체의 18%를 차지하고 있으며, 라스트 마일 배송의 전기화가 이를 뒷받침하고 있습니다.
전기 스쿠터 1대당 평균 패스너 사용 수는 지수적으로 증가하는 반면, 전기 승용차는 내연기관(ICE) 모델에 비해 220-280개의 볼트가 줄어듭니다. 모듈식 적재함 설계를 채택한 차량 운영 업체들은 3-5개의 적재량 등급에 걸쳐 패스너 SKU를 표준화하고 있으며, 이를 통해 부품 재고를 최대 5분의 2까지 줄이고 있습니다.
2025년에도 내연기관(ICE) 차량이 패스너 수요의 81.15%를 차지하고 있지만, 중국과 EU의 제로 배출 규제로 인해 BEV(배터리식 전기자동차)는 연평균 성장률(CAGR) 4.35%로 성장할 전망입니다. BEV는 차량당 패스너 사용량은 적지만, 등급 10.9 볼트나 스테인리스 볼트로의 전환에 따라 차량당 가치는 상승하고 있습니다. 하이브리드 차량은 과도기의 틈새 시장을 차지하고 있으며, 내연기관(ICE)용 패스너의 대부분을 유지하면서 배터리 관련 접합부를 40-60곳 새로 추가하고 있습니다.
예를 들어, 테슬라의 4680 배터리 팩에서는 수소 취성을 방지하기 위해 25 Nm의 토크로 조여진 M8 아연-니켈 도금 볼트 112개가 사용되고 있으며, 이는 사용 개수가 감소하더라도 고부가가치의 비즈니스 기회가 존재함을 보여줍니다.
지역별 분석
아시아태평양은 2025년에 전 세계 수요의 37.86%를 차지하고, 2031년까지 연평균 성장률(CAGR) 4.31%로 성장할 것으로 전망됩니다. 중국의 막대한 자동차 생산량과 인도의 급속한 성장이 맞물려 이 지역의 자동차 산업 강점이 두드러지고 있습니다. 동남아시아에서는 자동차 생산이 증가하고 있으며, 각 OEM 업체들이 조달 전략을 중국에서 전환함에 따라 새로운 패스너 공장 유치지로 주목받고 있습니다. 특히 주목할 점은 중국의 국내 공급업체들이 현재 현지 OEM 수요의 거의 절반을 충족시키고 있으며, 유럽의 동종 업체에 비해 신속한 납기와 경쟁력 있는 가격을 자랑한다는 것입니다. 인도의 급성장하는 전기 이륜차 시장은 자동차용 패스너 분야에서 아시아의 우위를 더욱 공고히 하고 있습니다.
2025년에 세계 수요의 상당 부분을 차지했던 유럽에서는 생산 정체와 프리미엄 브랜드의 접착 접합으로의 전환을 요인으로 성장률이 둔화되었습니다. 자동차 생산량이 많은 독일에서는 업계를 선도하는 KAMAX사와 Bossard사가 공급하는 고강도 등급의 패스너를 중심으로 대량의 패스너가 소비되었습니다. ‘폐차 지침(ELV 지침)’의 개정에 따라 탈착 가능한 접합부가 계속해서 권장되고 있어, 차체 공장의 생산량이 감소하고 있음에도 불구하고 나사식 패스너 수요는 지지를 받고 있습니다. 한편, 스텔란티스의 STLA 플랫폼 하에서 기존 브랜드를 통합함에 따라 SKU 수가 대폭 축소되어 공급업체 목록이 더욱 합리화되었습니다.
2025년 세계 수요의 큰 비중을 차지할 북미는 2031년까지 꾸준한 성장을 이룰 전망입니다. 미국 내 경트럭 및 SUV 생산은 견조한 모습을 보이고 있으며, ‘인플레이션 억제법’의 국내 조달 요건으로 인해 패스너 수주는 일리노이 툴 웍스(Illinois Tool Works)나 스탠리 엔지니어드 패스닝(Stanley Engineered Fastening)과 같은 국내 공급업체로 유도되고 있습니다. 또한, 반덤핑 관세 도입으로 인해 중국산 수입이 베트남이나 멕시코로 전환되면서 결과적으로 입고 비용이 상승하고 있습니다. 멕시코의 자동차 생산 급증은 패스너의 신규 생산 능력에 대한 막대한 투자를 불러오고 있지만, 캐나다 온타리오주에 위치한 공장은 효율적인 국경을 넘는 공급망에 크게 의존하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.26According to Mordor Intelligence, the automotive fasteners market size is expected to grow from USD 58.89 billion in 2025 to USD 61.37 billion in 2026 and is forecast to reach USD 75.42 billion by 2031 at a 4.21% CAGR over 2026-2031.
This report is Segmented by Fastener Type (Threaded and More), Vehicle Type (Two-Wheelers and More), Propulsion (ICE Vehicles and More), Function (Detachable and Non-Detachable), Material, Coating/Finish, Application, Distribution Channel, and Geography. Market Forecasts are Provided in Value (USD) and Volume (Units).
Global Automotive Fasteners Market Trends and Insights
Lightweighting Accelerating Demand for Advanced Fasteners
In response to the U.S. Corporate Average Fuel Economy (CAFE) updates and the European Union's 2025 fleet-average CO2 targets, automakers are under pressure to significantly reduce vehicle weight. This focus on weight reduction has brought attention to fasteners, which contribute a small but notable percentage of a vehicle's curb weight. While aluminum bolts offer substantial weight savings compared to steel, they require isolation sleeves or zinc-nickel coatings to prevent galvanic corrosion. These additional measures slightly increase the cost of each fastener. On the other hand, titanium fasteners, which are considerably more expensive than Grade 8.8 steel, are making their way from the world of Formula E racing to high-end luxury electric vehicles (EVs). Here, the appeal lies in the significant weight reduction that justifies the higher cost. Furthermore, the complexity of fastener requirements has increased: a body-in-white that previously relied on a few steel bolt sizes now demands a wider variety of SKUs. These include aluminum, stainless steel, and coated steel options. This expansion has led to a notable rise in working capital needs for tier-2 vendors, with requirements increasing considerably .
Recovery of Global Vehicle Production
In 2024, light-vehicle output experienced a significant rebound and is projected to grow further by 2026. This resurgence signals a restoration of baseline demand in the automotive fasteners market, following the semiconductor shortfall of recent years. During this period, China emerged as a major contributor, with India and Southeast Asia also playing substantial roles in driving demand for fasteners. Together, these regions accounted for a considerable share of the increased demand. Buoyed by an infrastructure stimulus in India and emissions mandates in California, commercial-vehicle production saw notable growth, particularly in heavy-duty segments. This surge benefits Asian suppliers, who boast rapid delivery windows, giving them a distinct advantage over European mills that rely on pre-positioned inventory. While Europe's production remained steady, the global momentum in unit builds serves as a supportive tailwind .
EV Architecture Reducing Fastener Count Per Vehicle
Battery-electric vehicles (BEVs) shed components like engine blocks, transmissions, exhaust systems, and fuel tanks. This change results in a significant reduction in the number of fasteners per unit when compared to traditional internal-combustion vehicles. For instance, Tesla's Model Y employs fewer fasteners than a gasoline crossover, marking a notable reduction. Additionally, structural battery designs further decrease the number of fasteners required. While the value of high-strength Grade 10.9 bolts in BEVs has increased, partially compensating for the reduced volume, the overall impact on the automotive fasteners market remains negative.
Other drivers and restraints analyzed in the detailed report include:
- Growing Electronics Content Requiring Micro-Fasteners
- Modular Vehicle Architectures Boosting Platform-Based Demand
- Adhesive Bonding and Laser Welding Substitution
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Threaded fasteners held 53.41% of 2025 revenue, underlining their versatility in chassis, powertrain, and interior systems. Specialty and safety-critical units, including torque-to-yield bolts and self-locking nuts, will post a 4.23% CAGR to 2031 as stringent crash-test protocols make them indispensable for seat-belt anchorages and battery-pack retention. Commodity threaded parts face gradual volume erosion in BEVs, yet their absolute demand in hybrids and traditional internal-combustion cars keeps the automotive fasteners market size substantial for this segment.
Specialty fasteners command 2-5X higher prices by integrating thread-locking compounds or captive washers that cut warranty claims and line rework. Non-threaded clips and rivets, while essential in interior trim, grow slower as adhesives gain favor in premium body-in-white. The premium attached to specialty items shields margins even in a platform-standardized procurement environment.
Passenger cars consumed 67.73% of all units in 2025, reflecting higher fastener intensity and global builds of 68 million vehicles. Two-wheelers, however, will log the fastest 4.37% CAGR through 2031 as India and China electrify scooter fleets, adding threaded bolts for battery enclosures and motor mounts. Light commercial vehicles and heavy trucks together account for 18% of volume, supported by last-mile delivery electrification.
Average fastener content per electric scooter is climbing exponentially, while electric passenger cars lose 220-280 bolts versus ICE models. Fleet operators adopting modular cargo bed designs standardize fastener SKUs across 3-5 payload classes, lowering parts inventories by up to two-fifths.
Internal-combustion vehicles still generated 81.15% of fastener demand in 2025, yet BEVs will expand at a 4.35% CAGR due to zero-emission rules in China and the EU. Although BEVs use fewer fasteners per vehicle, the shift toward Grade 10.9 bolts and stainless-steel variants lifts value per unit. Hybrid cars occupy a transitional niche, keeping most ICE fasteners while adding 40-60 new battery-related joints.
Tesla's 4680 pack, for instance, employs 112 M8 zinc-nickel-coated bolts torqued to 25 Nm to prevent hydrogen embrittlement, illustrating value-rich opportunities even as counts decline.
Complete Report Scope:
- By Fastener Type
- Threaded
- Non-threaded
- Specialty/Safety-critical
- By Vehicle Type
- Two-Wheelers
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Off-Highway Vehicles
- By Propulsion
- IC Engine Vehicles
- Battery Electric Vehicles
- Hybrid and Fuel-Cell Vehicles
- By Function
- Detachable
- Non-detachable
- By Material
- Steel
- Stainless Steel
- Aluminum
- Brass
- Plastics and Composites
- By Coating/Finish
- Zinc
- Phosphate
- Nickel and Chrome
- Organic and Dry Film
- By Application
- Body and Exterior
- Chassis and Suspension
- Powertrain and Engine
- Interior and Seating
- Electronics and Electrical
- By Distribution Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia Pacific held 37.86% of global demand in 2025 and is expected to grow at a 4.31% CAGR to 2031. China's significant automotive output, coupled with India's rapid growth, underscores the region's automotive prowess. Southeast Asia, with its growing vehicle production, is becoming a magnet for new fastener plants as OEMs pivot their sourcing strategies away from China. Notably, domestic suppliers in China are now meeting nearly half of local OEM demands, boasting swift delivery times and competitive pricing compared to their European counterparts. India's booming electric two-wheeler market has further solidified Asia's dominance in the automotive fasteners arena.
Europe, which represented a substantial portion of global demand in 2025, experienced a slower growth rate, attributed to production stagnation and a shift by premium brands towards adhesive bonding. In Germany, with its significant automotive output, a large volume of fasteners was consumed, predominantly high-strength grades supplied by industry leaders KAMAX and Bossard. The revision of the End-of-Life Vehicles Directive continues to favor detachable joints, bolstering the demand for threaded fasteners, even as body-shop volumes wane. Meanwhile, Stellantis's consolidation of legacy brands under the STLA platform has led to a notable reduction in SKUs and a more streamlined supplier roster.
North America, accounting for a significant share of global demand in 2025, is set to achieve steady growth through 2031. U.S. production of light trucks and SUVs has been robust, with the Inflation Reduction Act's content stipulations channeling fastener orders towards domestic suppliers like Illinois Tool Works and Stanley Engineered Fastening. Additionally, anti-dumping duties have shifted imports from China to Vietnam and Mexico, resulting in increased landed costs. Mexico's burgeoning automotive output has attracted significant investment in new fastener capacity, while Ontario's plants in Canada are heavily dependent on efficient cross-border supply chains.
- Illinois Tool Works Inc.
- LISI Group
- Nifco Inc.
- SFS Group AG
- Stanley Black & Decker Inc. (Stanley Engineered Fastening)
- Bulten AB
- KAMAX Holding GmbH & Co. KG
- Bossard Group
- Trifast plc (TR Fastenings Ltd.)
- Sundram Fasteners Limited
- ARaymond
- Shanghai Tianbao Fastener Manufacturing Co. Ltd.
- KOVA Fasteners Pvt. Ltd.
- The Phillips Screw Company
- Jiangsu Xing Chang Jiang International Co. Ltd.
- Penn Engineering & Manufacturing Corp.
- Aoyama Seisakusho Co. Ltd. (Indiana Automotive Fasteners)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Lightweighting Accelerating Demand for Advanced Fasteners
- 4.2.2 Recovery of Global Vehicle Production
- 4.2.3 Growing Electronics Content Requiring Micro-Fasteners
- 4.2.4 Modular Vehicle Architectures Boosting Platform-Based Demand
- 4.2.5 Ageing Vehicle PARC Driving Aftermarket Replacements
- 4.2.6 Re-Use and Circular-Economy Mandates Spurring Demand for Removable Fasteners
- 4.3 Market Restraints
- 4.3.1 EV Architecture Reducing Fastener Count Per Vehicle
- 4.3.2 Adhesive Bonding and Laser Welding Substitution
- 4.3.3 Raw-Material Price Volatility and Supply Disruptions
- 4.3.4 Trade-Defense Measures and Anti-Dumping Duties Disrupting Supply Chains
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Fastener Type
- 5.1.1 Threaded
- 5.1.2 Non-threaded
- 5.1.3 Specialty/Safety-critical
- 5.2 By Vehicle Type
- 5.2.1 Two-Wheelers
- 5.2.2 Passenger Cars
- 5.2.3 Light Commercial Vehicles
- 5.2.4 Medium and Heavy Commercial Vehicles
- 5.2.5 Off-Highway Vehicles
- 5.3 By Propulsion
- 5.3.1 IC Engine Vehicles
- 5.3.2 Battery Electric Vehicles
- 5.3.3 Hybrid and Fuel-Cell Vehicles
- 5.4 By Function
- 5.4.1 Detachable
- 5.4.2 Non-detachable
- 5.5 By Material
- 5.5.1 Steel
- 5.5.2 Stainless Steel
- 5.5.3 Aluminum
- 5.5.4 Brass
- 5.5.5 Plastics and Composites
- 5.6 By Coating/Finish
- 5.6.1 Zinc
- 5.6.2 Phosphate
- 5.6.3 Nickel and Chrome
- 5.6.4 Organic and Dry Film
- 5.7 By Application
- 5.7.1 Body and Exterior
- 5.7.2 Chassis and Suspension
- 5.7.3 Powertrain and Engine
- 5.7.4 Interior and Seating
- 5.7.5 Electronics and Electrical
- 5.8 By Distribution Channel
- 5.8.1 OEM
- 5.8.2 Aftermarket
- 5.9 By Geography
- 5.9.1 North America
- 5.9.1.1 United States
- 5.9.1.2 Canada
- 5.9.1.3 Rest of North America
- 5.9.2 South America
- 5.9.2.1 Brazil
- 5.9.2.2 Argentina
- 5.9.2.3 Rest of South America
- 5.9.3 Europe
- 5.9.3.1 Germany
- 5.9.3.2 United Kingdom
- 5.9.3.3 France
- 5.9.3.4 Italy
- 5.9.3.5 Spain
- 5.9.3.6 Rest of Europe
- 5.9.4 Asia Pacific
- 5.9.4.1 China
- 5.9.4.2 India
- 5.9.4.3 Japan
- 5.9.4.4 South Korea
- 5.9.4.5 Rest of Asia Pacific
- 5.9.5 Middle East and Africa
- 5.9.5.1 United Arab Emirates
- 5.9.5.2 Saudi Arabia
- 5.9.5.3 South Africa
- 5.9.5.4 Turkey
- 5.9.5.5 Rest of Middle East and Africa
- 5.9.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Illinois Tool Works Inc.
- 6.4.2 LISI Group
- 6.4.3 Nifco Inc.
- 6.4.4 SFS Group AG
- 6.4.5 Stanley Black & Decker Inc. (Stanley Engineered Fastening)
- 6.4.6 Bulten AB
- 6.4.7 KAMAX Holding GmbH & Co. KG
- 6.4.8 Bossard Group
- 6.4.9 Trifast plc (TR Fastenings Ltd.)
- 6.4.10 Sundram Fasteners Limited
- 6.4.11 ARaymond
- 6.4.12 Shanghai Tianbao Fastener Manufacturing Co. Ltd.
- 6.4.13 KOVA Fasteners Pvt. Ltd.
- 6.4.14 The Phillips Screw Company
- 6.4.15 Jiangsu Xing Chang Jiang International Co. Ltd.
- 6.4.16 Penn Engineering & Manufacturing Corp.
- 6.4.17 Aoyama Seisakusho Co. Ltd. (Indiana Automotive Fasteners)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


