|
시장보고서
상품코드
2116447
의약품 분석 시험 아웃소싱 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pharmaceutical Analytical Testing Outsourcing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
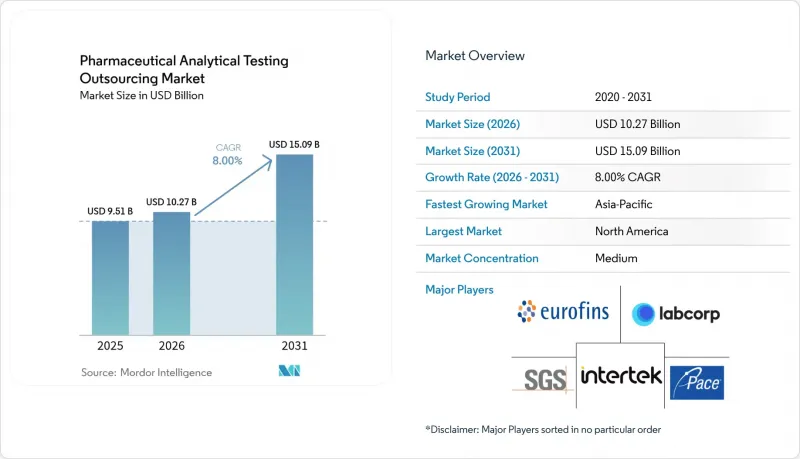
에 의하면, 의약품 분석 시험 아웃소싱 시장 규모는 2025년 95억 1,000만 달러에서 2026년에는 102억 7,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 8.00%로 성장을 지속하여, 2031년에는 150억 9,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 서비스별(바이오 분석 시험(임상시험 등) 등), 시험 유형별(화학 시험 등), 단계별(제1상 시험 등), 기술 플랫폼별(크로마토그래피 기반 등),아웃소싱 모델별(풀서비스 CRO 등), 최종 사용자별(가상/소규모 바이오테크 기업 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 의약품 분석 시험 아웃소싱 시장 동향 및 인사이트
전 세계 cGMP 시행 강화 및 감사 빈도 증가
FDA의 감시 강화가 규정 준수 전략의 재구성을 촉진하고 있습니다. FDA는 2024 회계연도에 561건의 양식 483을 발행했으며, 안정성 프로그램에 대한 지적 사항이 현저히 증가했습니다. 특히 인도 제조업체들은 검사 실적이 탁월한 외부 검사 기관에 샘플을 위탁하는 추세가 강해지고 있습니다. SGS 상하이는 2024년 FDA 검사에서 지적 사항 제로를 기록하며 전문 제공업체로서의 신뢰성 우위를 입증했습니다. 2024년에 도입된 FDA의 ‘품질 관리 성숙도(QMM) 프로토타입’이 기업들에게 적극적인 품질 검증을 촉구함에 따라 이러한 추세는 더욱 강화되고 있습니다.
바이오의약품으로의 전환이 복잡한 시험 수요를 확대
현재 생물학적 제제는 처방약 매출의 30%를 초과하며, 기존의 저분자 의약품 전문 검사 기관으로는 경제적으로 대응할 수 없는 세포 기반 효능, 면역원성, 바이러스 제거 등의 분석에 대한 수요가 높아지고 있습니다. 유로핀스와 SGS는 이러한 흐름에 발맞추기 위해 2024년에 각각 새로운 바이오의약품 센터를 개설했습니다. 유전자 편집 및 세포 치료제 파이프라인이 성숙해짐에 따라, 엔드투엔드 생물학적 분석 아웃소싱은 대형 제약사는 물론 가상 바이오테크 기업에게도 사업상 필수적인 요소가 되고 있습니다.
지적 재산권·데이터 보안 및 사이버 위험에 대한 우려
클라우드 도입으로 인해 공격 표면이 확대되는 가운데, 의약품 개발 기업들은 새로운 파트너를 선정할 때 과학적 전문성과 마찬가지로 사이버 보안을 중요하게 여기고 있습니다. 중국의 2024년 ‘반스파이법’은 데이터 처리에 대한 국가의 감독 범위를 확대함으로써 추가적인 불확실성을 초래하고 있으며, 일부 유럽 감사 기관은 현지 감사를 일시 중단하는 사태에 이르렀습니다.
부문 분석
2025년 매출의 43.78%를 바이오분석 시험이 차지하며, 의약품 분석 시험 아웃소싱 시장의 핵심으로서의 입지가 확인되었습니다. 2031년까지 이 부문의 연평균 성장률(CAGR) 12.56%는 단일클론 항체 및 세포 치료제 파이프라인에 따른 리간드 결합 분석, 세포 기반 기능 시험, 바이러스 벡터 특성 평가에 대한 수요가 급증하고 있음을 반영합니다. 방법 개발 및 검증은 계속해서 초기 단계 프로그램의 기반이 되고 있는 반면, 안정성 시험은 보관 기간 결정에 있어 필수적인 역할을 계속하고 있습니다. USP 1663/1664의 시행에 따라, 추출물 및 용출물 분석 업무는 두 자릿수 성장을 향해 나아가고 있습니다. 또한, 스폰서들이 일회성 샘플 분석이 아닌 통합적인 전략을 추구하는 가운데, 컨설팅 서비스도 호황을 누리고 있습니다.
각 제약 스폰서사는 동등한 수준의 사내 바이오애널리틱스 체계를 구축하는 데 수년이 소요되고 막대한 자본이 필요하다는 점을 인식하고 있으며, 그 자본을 차라리 임상 자산에 투자하고자 합니다. 유로핀이 2024년에 중견 바이오테크 기업과 체결한 제휴는 대형 CRO가 현재 프로토콜 설계, 분석법 이전, 규제 문서 작성을 일원화하여 제공하고 있는 실태를 보여줍니다. 그 결과, 바이오애널리틱스 워크플로는 FSP(고정 서비스 계약) 및 프로젝트 기반 프레임워크 모두에서 외부 위탁의 최우선 후보로 항상 꼽히고 있으며, 이를 통해 지적 재산 관리 및 임상 전략에 사내 자원을 할당할 수 있게 되었습니다.
기존의 화학 분석법(동정, 순도, 잔류 용매)은 2025년에도 여전히 30.80%의 점유율을 차지하고 있었으나, 그 성장은 정체 상태에 접어들었습니다. 대조적으로, 추출물·용출물(E&L)은 연평균 성장률(CAGR) 10.95%를 나타낼 것으로 전망되며, 이는 바이오의약품 프로그램에서 용기 및 밀폐 시스템에 대한 면밀한 검토가 얼마나 중요한 과제가 되고 있는지를 보여줍니다. 미생물학, 원료의 적격성 평가 및 용출 시험은 정제 및 제네릭 의약품에 있어 여전히 필수적이지만, 그 확대 속도는 의약품 분석 시험 아웃소싱 시장 전체에 비해 뒤처지고 있습니다.
LC-MS/MS 스크리닝 및 독성 위험 평가를 핵심으로 하는 인터텍의 30년에 걸친 E&L 실적은 현재 스폰서들로부터 높은 평가를 받고 있는 전문성을 상징합니다. 주사제 출시에서 첨가제, 올리고머 및 실리콘 잔류물의 정밀한 정량은 더 이상 선택 사항이 아니며, 화학 분석 실험실은 다각화를 도모하거나 상품화 위험에 직면하게 될 것입니다. 그 결과, 일부 중견 서비스 제공업체들은 높은 수익률을 자랑하는 바이오의약품 시험 분야에서 경쟁력을 유지하기 위해 GC-MS/MS와 같은 하이픈 기술에 대한 투자를 추진하고 있습니다.
지역별 분석
북미는 2025년 시장 가치의 36.90%를 차지하고 있으며, 그 배경에는 FDA의 엄격한 감독과 보스턴에서 샌디에이고에 이르기까지 펼쳐진 밀집된 CRO 생태계가 있습니다. 'BIOSECURE 법안'에 대한 심의가 계속되고 있는 만큼, 미국에 기반을 둔 스폰서들은 중국으로부터공급망을 재검토할 수밖에 없게 되었으며, 단위 비용이 높아지더라도 단기적으로는 미국 및 캐나다의 검사 기관에 대한 수요가 증가하고 있습니다. 캐나다 온타리오주와 퀘벡주를 연결하는 회랑 지역은 지리적 근접성과 GMP 규정 통합이라는 이점을 활용하고 있습니다. 한편, 멕시코의 바하칼리포르니아주 및 할리스코주의 클러스터는 이중언어 구사 인력과 경쟁력 있는 가격 책정을 통해 후기 단계의 안정성 시험을 흡수하고 있습니다.
유럽은 여전히 2위의 규모를 자랑합니다. 독일과 영국은 활발한 연구개발(R&D) 활동과 풍부한 임상 파이프라인을 통해 수요를 유지하고 있습니다. EMA의 ICH Q8-Q10 준수 관련 2025년 업데이트는 PAT를 활용한 분석 기술의 보급을 촉진하고 있으며, 유럽 대륙의 중소규모 제공업체들은 앞다투어 이를 도입하고 있습니다. 남유럽은 바이오시밀러 생산 확대를 통해 입지를 공고히 하고 있으며, 이탈리아 롬바르디아주에서는 습식 실험실 인력이 한 자릿수 중반의 비율로 증가하고 있습니다. 스위스와 북유럽 국가들은 특히 규제 당국의 기대와 선진적인 병원 네트워크가 부합하는 맞춤형 세포 치료 분석법 등 고부가가치 프로젝트를 계속해서 수주하고 있습니다.
아시아태평양은 명백한 성장 동력이며, 2031년까지 연평균 성장률(CAGR)은 10.12%로 예측됩니다. 중국은 여전히 가장 큰 실험실 인프라를 보유하고 있지만, 지정학적 압력으로 인해 미국 및 EU의 후원사들은 인도, 싱가포르, 호주로의 대체 공급원 확보를 추진하고 있습니다. 새로운 바이러스 벡터 연구소가 모여 있는 인도의 하이데라바드 유전체 밸리는 중국에서 철수하는 고객들이 남긴 계약을 확보하고 있습니다. 한편, 아세안(ASEAN) 규제 조화 운영위원회는 신청 서류 양식을 통일하여 말레이시아, 싱가포르, 필리핀에서의 시판 승인까지 소요되는 기간을 단축하고 있습니다. 일본과 한국은 고도로 복잡한 바이오의약품에 주력하며, 국내 자동화 및 로봇공학 분야의 리더십을 활용해 고부가가치 프로젝트 수주를 도모하고 있습니다.
그 밖의 남미, 중동 및 아프리카 지역은 현지 제조 인센티브가 확대됨에 따라 규모는 작지만 시장 점유율을 점차 확대되고 있습니다. 에콰도르가 2025년에 실시할 GMP 전면 개편은 연구소가 세계적 동등성을 입증할 수 있다면 규제 현대화가 국제적인 투자를 유치할 수 있다는 좋은 사례입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.28According to Mordor Intelligence, the pharmaceutical analytical testing outsourcing market size is expected to grow from USD 9.51 billion in 2025 to USD 10.27 billion in 2026 and is forecast to reach USD 15.09 billion by 2031 at 8.00% CAGR over 2026-2031.
This report is Segmented by Services (Bioanalytical Testing [Clinical and More] and More), Test Type (Chemistry Testing and More), Phase (Phase I and More), Technology Platform (Chromatography-Based and More), Outsourcing Model (Full-Service CRO, and More), End-User (Virtual / Small Biotech and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Pharmaceutical Analytical Testing Outsourcing Market Trends and Insights
Heightened Global cGMP Enforcement & Audit Frequency
Heightened FDA scrutiny is reshaping compliance strategies, as the agency issued 561 Form 483s in fiscal 2024 with a notable spike in stability-program findings. Manufacturers, especially in India, increasingly funnel samples to external labs with impeccable inspection records-SGS Shanghai recorded a 2024 FDA inspection with zero observations, reinforcing the credibility advantage of specialized providers The trend deepens as the FDA's Quality Management Maturity prototype, rolled out in 2024, nudges firms toward proactive quality validation.
Shift-To-Biologics Expanding Complex Testing Demand
Biologics now exceed 30% of prescription drug revenue, elevating demand for assays such as cell-based potency, immunogenicity, and viral clearance that conventional small-molecule labs cannot support economically. Eurofins and SGS have each opened new biologics centers in 2024 to catch this wave. As gene-editing and cell-therapy pipelines mature, end-to-end bioanalytical outsourcing becomes mission-critical for both large pharma and virtual biotech alike.
IP-Data-Security & Cyber-Risk Concerns
Drug developers rank cybersecurity alongside scientific capability when selecting new partners as cloud adoption widens the attack surface. China's 2024 Anti-Espionage Law adds further uncertainty by broadening state oversight of data handling, prompting some European auditors to pause on-site inspections.
Other drivers and restraints analyzed in the detailed report include:
- Cost-Savings & CAPEX Avoidance For Small Pharma
- Rising Adoption Of Quality-By-Design Protocols
- Skills Shortage Inflating CRO Wage Bills
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bioanalytical testing generated 43.78% of 2025 revenue, confirming its status as the linchpin of the pharmaceutical analytical testing outsourcing market. The segment's 12.56% CAGR through 2031 reflects skyrocketing demand for ligand-binding assays, cell-based functional tests, and viral-vector characterization that accompany monoclonal antibody and cell-therapy pipelines. Method development and validation continues to anchor early-phase programs, while stability testing stays indispensable for shelf-life decisions. USP 1663/1664 enforcement pushes extractables-and-leachables assignments toward double-digit growth, and consulting services flourish as sponsors seek integrated strategies rather than transactional sample runs.
Pharmaceutical sponsors acknowledge that building comparable in-house bioanalytical suites would consume years and capital they prefer to channel into clinical assets. Eurofins' 2024 tie-ups with mid-tier biotechs illustrate how large CROs now package protocol design, assay transfer, and regulatory writing under one roof. As a result, bioanalytical workflows consistently rank among the first candidates for externalization under both FSP and project-based frameworks, preserving internal bandwidth for intellectual-property management and clinical strategy.
Traditional chemistry assays-identity, purity, residual solvents-still held 30.80% share in 2025, but growth has plateaued. In contrast, extractables & leachables posted an 10.95% CAGR outlook, signaling how container-closure scrutiny has become mission-critical in biologics programs. Microbiology, raw-material qualification, and dissolution remain essential for tablets and generics, yet their expansion trails the overall pharmaceutical analytical testing outsourcing market.
Intertek's thirty-year E&L track record, built around LC-MS/MS screens and toxicological risk assessments, typifies the specialization now prized by sponsors. Precise quantification of additives, oligomers, and silicone residues is no longer optional in parenteral launches, making chemistry labs diversify or risk commoditization. Consequently, several mid-sized providers are investing in hyphenated techniques, such as GC-MS/MS, to stay relevant amid higher-margin biologics tests.
Complete Report Scope:
- By Services
- Bioanalytical Testing
- Clinical
- Non-clinical
- Method Development & Validation
- Extractables & Leachables
- Impurity Methods
- Technical Consulting
- Stability Testing
- Drug Substance
- Accelerated / Photostability
- Other Services
- Bioanalytical Testing
- By Test Type
- Chemistry Testing
- Microbiological Testing
- Extractables & Leachables
- Raw-Material & Excipient Testing
- Dissolution & Disintegration
- Other Test Types
- By Phase
- Discovery & Preclinical
- Phase I
- Phase II
- Phase III
- Commercial / QC Release
- By Technology Platform
- Chromatography-Based
- Mass Spectrometry
- Spectroscopy (UV/IR/NMR)
- Cell-Based Bioassays
- Molecular / Immunoassays (PCR, ELISA)
- By Outsourcing Model
- Full-Service CRO
- Functional Service Provider (FSP)
- Project-Based (a la carte)
- By End-User
- Pharmaceutical & Biopharmaceutical Companies
- Contract Development & Manufacturing Organizations (CDMOs/CMOs)
- Virtual / Small Biotech
- Academic & Research Institutes
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 36.90% of 2025 value, anchored by stringent FDA oversight and a dense CRO ecosystem that stretches from Boston to San Diego. Ongoing BIOSECURE Act deliberations compel US-based sponsors to re-map supply lines away from China, driving near-term traffic toward domestic and Canadian labs even at higher unit costs. Canada's Ontario-Quebec corridor benefits from proximity and aligned GMP rules, while Mexico's Baja and Jalisco clusters absorb late-phase stability studies thanks to bilingual workforces and competitive pricing.
Europe remains the second-largest region. Germany and the United Kingdom sustain demand through high R&D intensity and extensive clinical pipelines. EMA's 2025 update on ICH Q8-Q10 compliance spurs penetration of PAT-enabled analytics, which smaller continental providers race to adopt. Southern Europe gains ground via growing biosimilar output, with Italy's Lombardy region expanding wet-lab headcount by mid-single digits. Switzerland and the Nordics retain high-value project work, particularly bespoke cell-therapy assays where regulatory expectations align with their advanced hospital networks.
Asia-Pacific is the clear growth engine, projected at 10.12% CAGR to 2031. China continues to house the largest installed lab base, yet geopolitical pressures encourage US and EU sponsors to second-source in India, Singapore, and Australia. India's Hyderabad Genome Valley, home to new viral-vector labs, captures contracts vacated by clients exiting China. Meanwhile, ASEAN's Regulatory Harmonization Steering Committee smooths dossier formats, trimming launch timelines in Malaysia, Singapore, and the Philippines. Japan and South Korea focus on high-complexity biologics, leveraging domestic automation and robotics leadership to secure premium projects.
Other regions-South America, Middle East & Africa-comprise a smaller yet rising slice as local manufacturing incentives swell. Ecuador's 2025 GMP overhaul exemplifies how modernized rules can attract international inflows, provided labs can document global equivalence.
- SGS
- Eurofins
- LabCorp
- Pace Analytical Services
- Intertek Group
- Thermo Fisher Scientific
- WuXi App Tec
- Charles River
- Boston Analytical
- West Pharmaceutical Services
- Element Materials Technology
- Merck
- KCAS Bio
- BioAgilytix
- Anapharm Bioanalytics
- Syngene International
- ICON
- IQVIA Labs
- Alcami Corp
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Heightened Global Cgmp Enforcement & Audit Frequency
- 4.2.2 Shift-To-Biologics Expanding Complex Testing Demand
- 4.2.3 Cost-Savings & CAPEX Avoidance For Small Pharma
- 4.2.4 Rising Adoption Of Quality-By-Design Protocols
- 4.2.5 AI-Enabled Remote Audits Lowering Vendor-Qualification Costs
- 4.2.6 Regulatory Convergence In ASEAN & LATAM Creating New Volume
- 4.3 Market Restraints
- 4.3.1 IP-Data-Security & Cyber-Risk Concerns
- 4.3.2 Skills Shortage Inflating CRO Wage Bills
- 4.3.3 US BIOSECURE Act May Curb China-Based Labs
- 4.3.4 Capacity Crunch For Viral-Vector/Biologics Assays
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Services
- 5.1.1 Bioanalytical Testing
- 5.1.1.1 Clinical
- 5.1.1.2 Non-clinical
- 5.1.2 Method Development & Validation
- 5.1.2.1 Extractables & Leachables
- 5.1.2.2 Impurity Methods
- 5.1.2.3 Technical Consulting
- 5.1.3 Stability Testing
- 5.1.3.1 Drug Substance
- 5.1.3.2 Accelerated / Photostability
- 5.1.4 Other Services
- 5.1.1 Bioanalytical Testing
- 5.2 By Test Type
- 5.2.1 Chemistry Testing
- 5.2.2 Microbiological Testing
- 5.2.3 Extractables & Leachables
- 5.2.4 Raw-Material & Excipient Testing
- 5.2.5 Dissolution & Disintegration
- 5.2.6 Other Test Types
- 5.3 By Phase
- 5.3.1 Discovery & Preclinical
- 5.3.2 Phase I
- 5.3.3 Phase II
- 5.3.4 Phase III
- 5.3.5 Commercial / QC Release
- 5.4 By Technology Platform
- 5.4.1 Chromatography-Based
- 5.4.2 Mass Spectrometry
- 5.4.3 Spectroscopy (UV/IR/NMR)
- 5.4.4 Cell-Based Bioassays
- 5.4.5 Molecular / Immunoassays (PCR, ELISA)
- 5.5 By Outsourcing Model
- 5.5.1 Full-Service CRO
- 5.5.2 Functional Service Provider (FSP)
- 5.5.3 Project-Based (a la carte)
- 5.6 By End-User
- 5.6.1 Pharmaceutical & Biopharmaceutical Companies
- 5.6.2 Contract Development & Manufacturing Organizations (CDMOs/CMOs)
- 5.6.3 Virtual / Small Biotech
- 5.6.4 Academic & Research Institutes
- 5.6.5 Other End-Users
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 SGS SA
- 6.3.2 Eurofins Scientific
- 6.3.3 Labcorp
- 6.3.4 Pace Analytical Services
- 6.3.5 Intertek Group
- 6.3.6 Thermo Fisher Scientific
- 6.3.7 WuXi AppTec
- 6.3.8 Charles River Laboratories
- 6.3.9 Boston Analytical
- 6.3.10 West Pharmaceutical Services
- 6.3.11 Element Materials Technology
- 6.3.12 Merck KGaA
- 6.3.13 KCAS Bio
- 6.3.14 BioAgilytix
- 6.3.15 Anapharm Bioanalytics
- 6.3.16 Syngene International
- 6.3.17 ICON plc
- 6.3.18 IQVIA Labs
- 6.3.19 Alcami Corp
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment